Why should your hard-earned revenue pay off someone else’s property when it could be building your own legacy? You’ve likely watched commercial rents in Saint Augustine climb while feeling buried under the weight of complex bank jargon. It’s frustrating to feel like a visitor in your own workspace, especially when national banks treat your application like a number. Securing a small business commercial mortgage shouldn’t feel like a bureaucratic nightmare. We’re here to help you move past the confusion and find a path that works for your unique goals.
This guide simplifies the transition from tenant to owner, showing you exactly how to lock in long-term financial stability. Explore the current 2026 market rates and see how local expertise cuts through the red tape. Follow these clear steps to own your piece of the Ancient City. Stop renting your future and start building it today.
Key Takeaways
- Learn how a small business commercial mortgage uses your property as collateral to justify debt and build your company’s net worth.
- Discover the “Five Cs” lenders use to evaluate your creditworthiness and how to prepare your business tax returns for a smooth approval.
- Uncover the benefits of partnering with a local broker who shops your deal to multiple lenders to secure the best possible terms.
- Map out your transition from a tenant to a property owner to gain predictable costs and long-term stability in St. Johns County.
Understanding the Small Business Commercial Mortgage
A small business commercial mortgage is a specialized financing tool that transforms your monthly overhead into a long-term wealth-building asset by securing the property your business calls home. It’s a debt-based solution used to buy or refinance space for your operations. Unlike a home loan, the property itself acts as collateral, and your business income justifies the debt. Grasping commercial mortgage fundamentals helps you see how this process differs from residential lending. It’s a strategic move that turns a monthly expense into a permanent investment.
Why Commercial Ownership is a Smart Move for St. Augustine Businesses
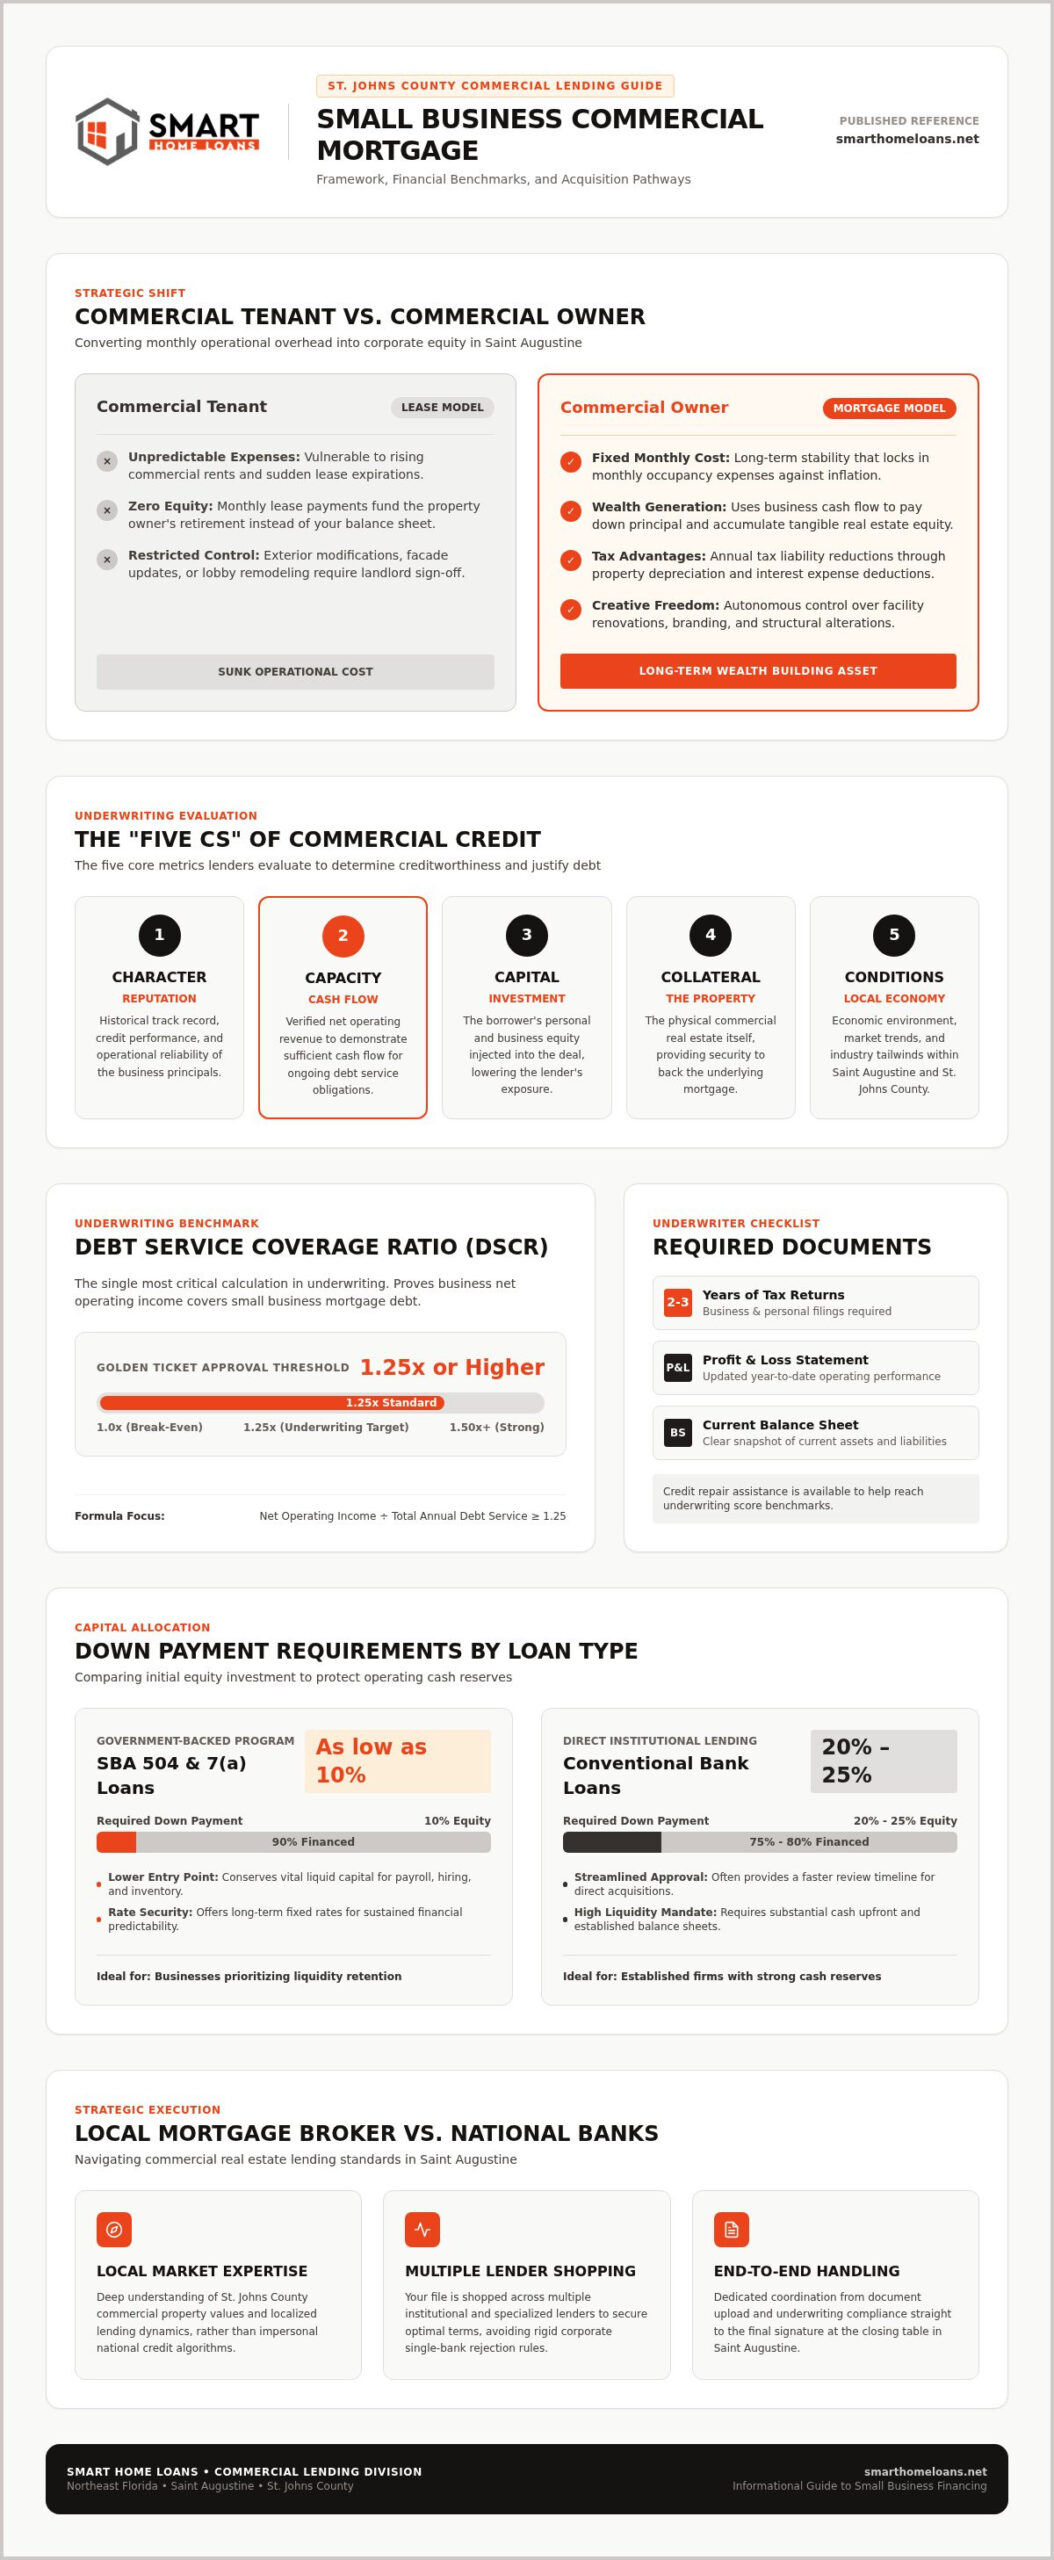
Investing in your own commercial real estate financing in Florida is a bold step toward independence. While renting might seem easier upfront, ownership offers rewards that a lease never will. You stop funding a landlord’s retirement and start building your own equity in St. Johns County. Consider these specific advantages:
- Tax Benefits: Ownership allows you to leverage depreciation and interest deductions. These can significantly lower your annual tax bill.
- Fixed Costs: Lock in your monthly housing expense. You won’t face the stress of sudden rent spikes or expiring lease terms.
- Creative Freedom: Want to paint the facade or remodel the lobby? You have the final say. There’s no need to wait for a landlord’s approval.
Saint Augustine is growing fast. Securing a small business commercial mortgage now ensures you aren’t priced out of the market later. It provides the financial foundation your business needs to thrive for decades. You’re not just buying a building; you’re claiming your piece of the Ancient City.
Qualifying for Your Small Business Commercial Loan in 2026
Lenders evaluate your application using a framework known as the “Five Cs.” This includes your Character (reputation), Capacity (cash flow), Capital (personal investment), Collateral (the property), and Conditions (the local economy). To tell this story effectively, you’ll need to provide at least two to three years of business and personal tax returns. This data helps them calculate your Debt Service Coverage Ratio (DSCR), which is the most critical number in the underwriting process. A ratio of 1.25 or higher is typically the golden ticket for approval. It proves your business generates enough net income to cover your new small business commercial mortgage payments comfortably.
Essential Documents and Credit Standards for Florida Borrowers
Success starts with a well-organized folder. You’ll need updated Profit & Loss statements and a current balance sheet to show your business is healthy. If your credit score isn’t quite ready for prime time, don’t lose hope. We offer credit repair for mortgage approval to help you reach the necessary benchmarks. While conventional loans often require a 20% to 25% down payment, the SBA 504 loan program provides a path with as little as 10% down. This lower entry point keeps more cash in your pocket for operations. If you’re unsure where you stand, let’s look at your options together. Securing a small business commercial mortgage is a team effort, and we’re ready to handle the heavy lifting for you.
Navigating the Commercial Lending Process with a Local Guide
Partnering with a local mortgage broker gives you an immediate edge that big national banks simply can’t match. We provide access to a wider variety of specialized loan products tailored for the unique market in Northeast Florida. Instead of being stuck with one set of rigid corporate rules, you get a dedicated advocate who understands the St. Johns County landscape. We shop your deal to multiple lenders to find the most competitive terms for your small business commercial mortgage. Our team handles the heavy lifting from the first document upload to the final signature at the closing table in Saint Augustine. We ensure every detail of your file aligns with current commercial real estate lending standards to prevent frustrating delays. For a deeper look at specific structures, check out our commercial mortgage loan pillar.
Choosing Between SBA Loans and Traditional Commercial Financing
Deciding on the right path depends on your business’s specific cash flow and your desired timeline. SBA 7(a) and 504 loans are ideal for owners seeking lower down payments and the security of long-term fixed rates. These programs often require as little as 10% down, which keeps your cash available for hiring or inventory. Traditional bank loans can be a faster route for established businesses with high liquidity and very strong balance sheets. While they might require more equity upfront, they often involve a more streamlined approval process for simple acquisitions. Consult with Sean at Smart Home Loans to determine which path fits your 2026 growth strategy. We’ll help you compare the interest rates and repayment terms so you can make an informed decision with confidence. Let us navigate the red tape while you focus on running your business.
Claim Your Piece of Saint Augustine’s Future
Transitioning from a tenant to a property owner is one of the most significant milestones for any entrepreneur. By securing a small business commercial mortgage, you stop chasing rising rents and start building actual wealth within your company. You’ve learned how to prepare your documents and why your debt service ratio matters for a smooth approval. Since 2018, we’ve provided local Saint Augustine expertise to help neighbors like you handle the red tape. We offer expert guidance through the commercial real estate financing in Florida process with a helpful, neighborly touch that puts your business first. Don’t let complex jargon or big bank hurdles stand in your way. Take the first step toward long-term financial stability today. Start your Saint Augustine commercial mortgage journey today. We’re ready to help you own your space.
Frequently Asked Questions
What is the typical down payment for a small business commercial mortgage?
A typical down payment for a small business commercial mortgage ranges from 10% to 25% of the purchase price. Programs like the SBA 504 loan allow for a lower 10% entry point for owner-occupied properties. Conventional bank loans usually require a higher 20% or 25% equity stake. We’ll help you find the specific program that keeps the most cash in your business.
Can I get a commercial mortgage if I have a low credit score?
Yes, you can still pursue a mortgage even if your credit isn’t perfect. While SBA lenders typically look for a score of at least 660, we offer integrated credit repair services to help boost your eligibility. We work as your local advocate to address past hurdles and build a stronger application. Don’t let a number stop you from reaching your business goals.
How is a commercial mortgage different from a small business loan?
A small business commercial mortgage is specifically used to purchase or refinance real estate where the property itself serves as collateral. General small business loans are often used for working capital, equipment, or inventory and may be unsecured. With a mortgage, the loan term is much longer, often up to 25 years, providing your business with predictable, long-term housing costs.
Is it better to rent or buy commercial property in Saint Augustine right now?
Buying is often the better move to protect yourself from Saint Augustine’s rising insurance costs and base rent increases. Even though Florida repealed the commercial rent sales tax in late 2025, property ownership offers long-term stability that a lease cannot match. With over 6 million annual visitors driving demand in the city core, owning your space ensures your business stays relevant.