What if the only thing standing between you and your Florida dream home isn’t the price tag, but a simple misunderstanding of the 2026 loan limits? You likely feel that securing jumbo loans Florida requires an impossible financial profile and endless paperwork. It’s natural to feel stressed by stricter credit scores and the high down payments expected in the luxury market.
We’re here to simplify the process and give you the confidence to move forward by mastering the new $832,750 threshold and the credit strategies you need to succeed. We’ll walk through the latest reserve requirements, explain the Monroe County exceptions, and show you how local expertise makes complex luxury appraisals feel easy. Let’s turn your vision into a reality.
Key Takeaways
- Understand the new 2026 baseline limit of $832,750 for most counties to determine if your mortgage fits the jumbo category.
- Identify the exact credit score and debt-to-income ratios you need to secure competitive terms on jumbo loans Florida.
- Learn how to prepare your cash reserves to meet the stricter requirements of high-value luxury lending.
- Explore the advantages of using a local broker to access multiple lending outlets and specialized market expertise.
Understanding 2026 Florida Jumbo Loan Limits
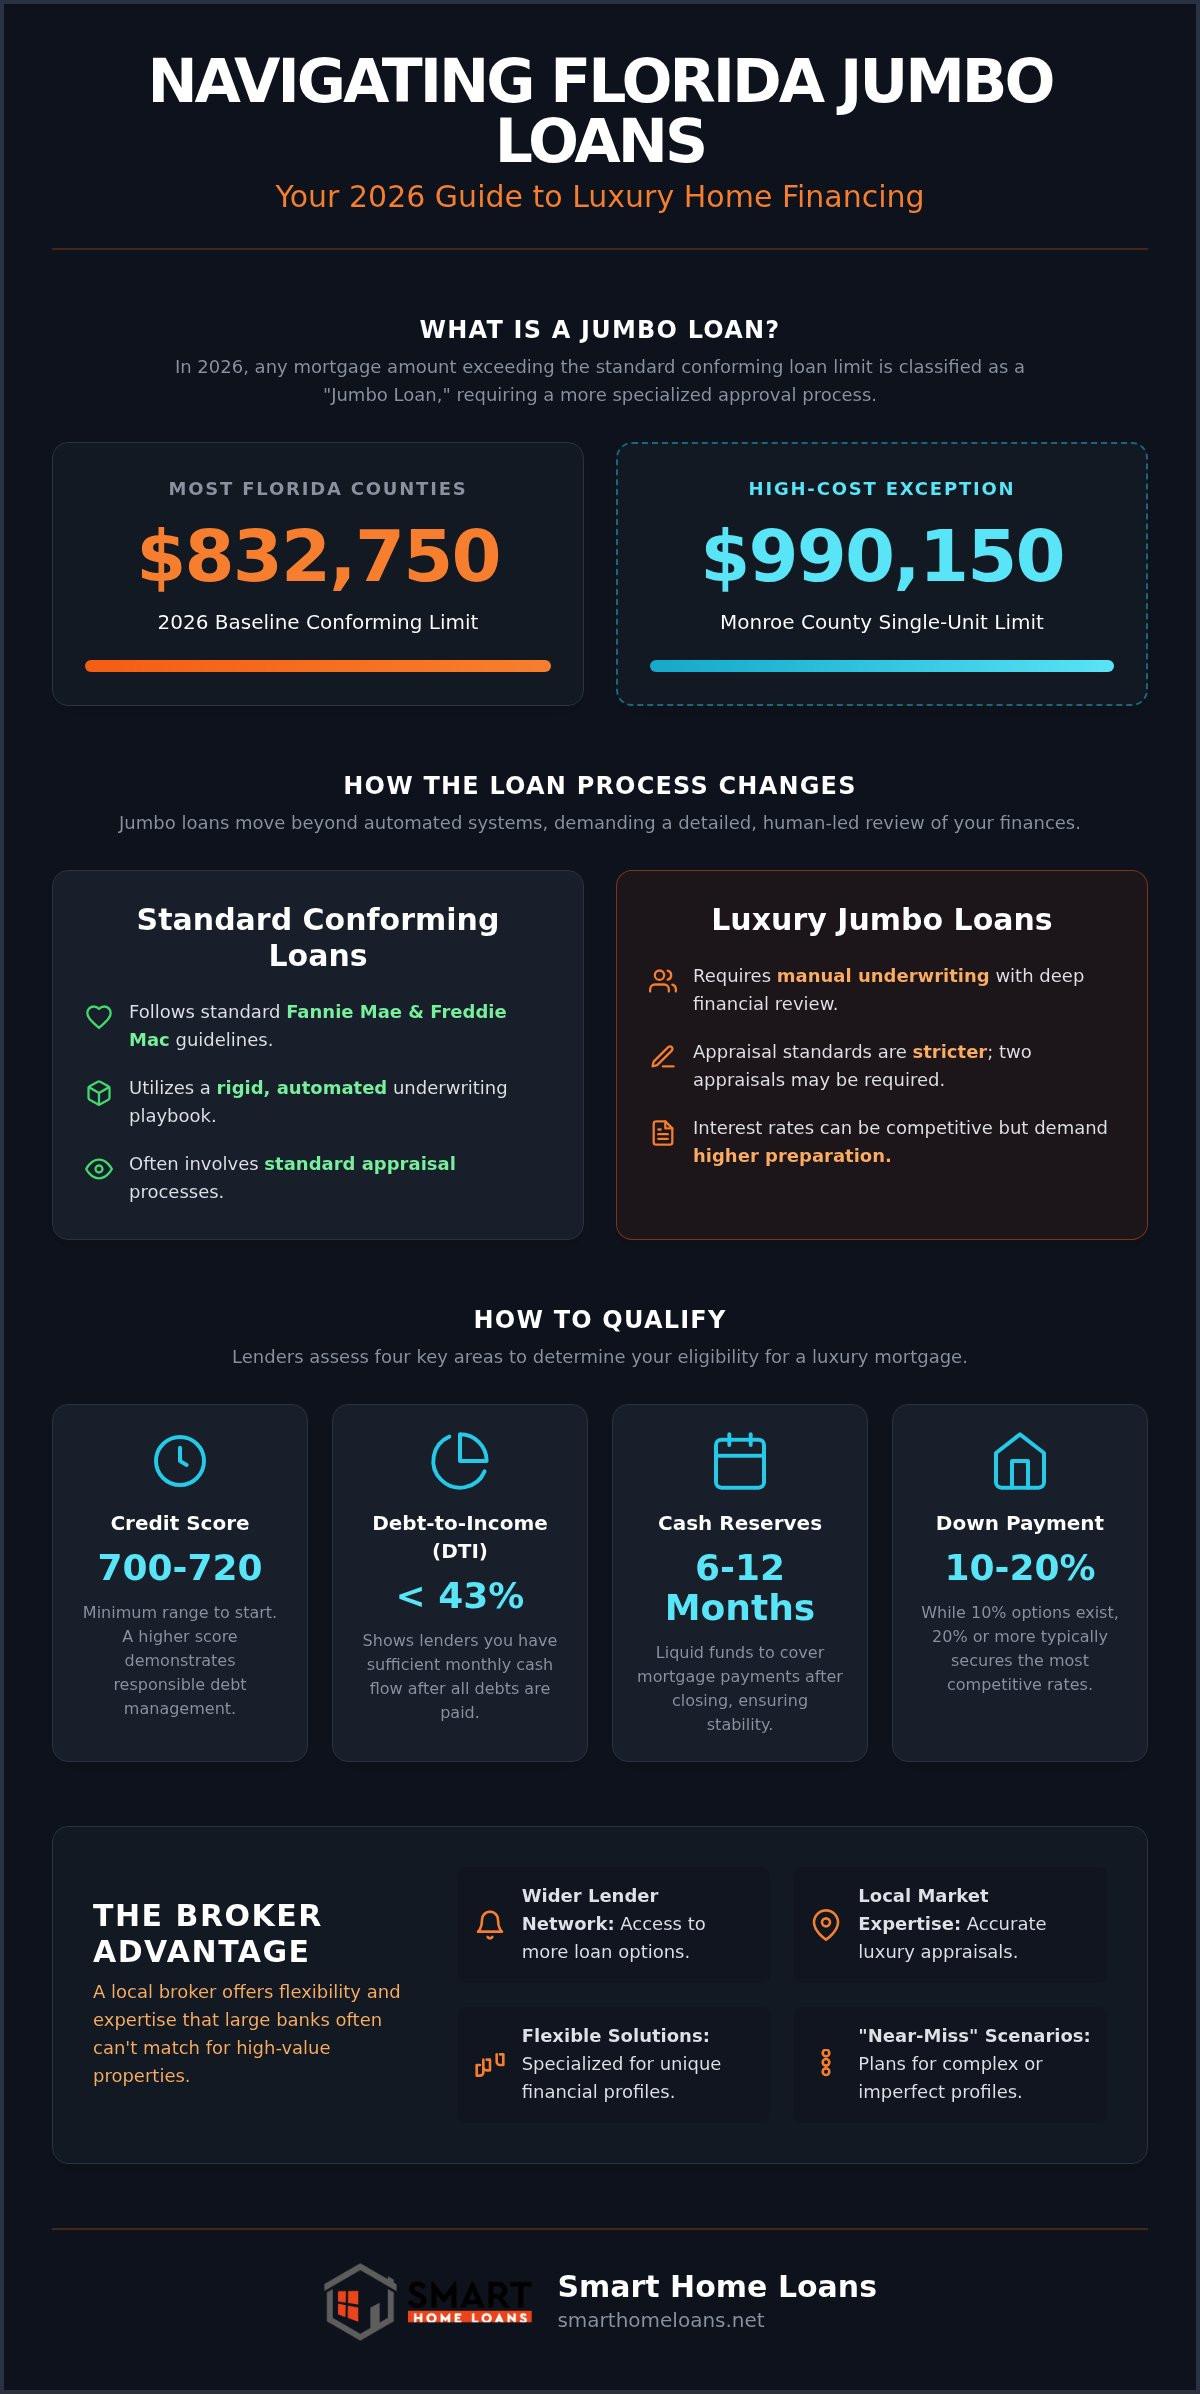
For 2026, the Federal Housing Finance Agency set the baseline conforming loan limit at $832,750 for most counties. Are you shopping for a home in Saint Augustine or Jacksonville? Any mortgage amount above this figure is classified as a non-conforming loan. When you pursue jumbo loans Florida, the distinction matters. It changes your path to approval. You’re no longer following standard Fannie Mae or Freddie Mac guidelines.
In luxury hotspots like Ponte Vedra Beach and Saint Augustine, property values often climb well past these limits faster than the national average. Understanding Jumbo Mortgages is the first step in securing your dream estate. While most of the state stays at the baseline, Monroe County is a unique high-cost exception. Limits there reach $990,150 for single-unit homes. Knowing your specific county limit helps you plan your down payment strategy effectively and avoid surprises at the closing table.
Conforming vs. Jumbo Loans: What Changes for You?
Standard conforming loans follow a rigid, automated playbook. Choosing jumbo loans Florida requires a more human approach. Lenders use manual underwriting to dive deep into your financial history. You’ll face stricter appraisal standards to verify the home’s luxury value. Interest rates also differ from government backed home loans Florida. Sometimes jumbo rates are even more competitive, but they always demand higher preparation.
How to Qualify for a Jumbo Mortgage in Florida
Do you have your financial house in order? Qualifying for jumbo loans Florida is a detailed process that rewards preparation. Most lenders look for a credit score between 700 and 720 to start. They want to see a history of responsible debt management. Your Debt-to-Income (DTI) ratio is also a critical factor. Aim to keep this under 43%. This percentage shows lenders you have plenty of breathing room in your monthly budget. If your score needs a boost, consider chatting with a local brokerage about credit optimization strategies.
Income verification is where the paperwork gets serious. Are you self-employed or a high-net-worth individual? Be ready to provide comprehensive tax returns and asset statements. Lenders need to see a stable, predictable income stream. You must also prove you have deep cash reserves. Most jumbo loans Florida programs require 6 to 12 months of mortgage payments sitting in liquid accounts. This ensures you can handle the loan even if your income fluctuates temporarily.
The Importance of Down Payments and Reserves
How much should you put down? While 10% options exist, a 20% down payment usually unlocks the most competitive rates. Remember the reserve rule. This is money that stays in your account after you close. It is not part of your down payment. For unique or high-value Florida estates, expect a request for two appraisals. This double-check protects everyone by confirming the home’s true market value before the deal is finalized.
Why Choose a Saint Augustine Broker for Your Jumbo Loan
Working with a big bank often feels cold and rigid. When you’re dealing with high-value property, you deserve a partner who understands the local landscape. At Smart Home Loans, we act as your dedicated advocate. We aren’t limited to a single set of rules. Instead, we access a wide network of luxury lenders to find the most flexible terms for jumbo loans Florida. This brokerage model is a game-changer for buyers who need specialized solutions.
Local expertise matters during the appraisal process. We know the Saint Augustine and Jacksonville markets intimately. This ensures your luxury estate is valued accurately, preventing deal-breaking surprises. You’ll work directly with Sean (NMLS ID 1734077). He provides the personalized support required to handle complex luxury closings with ease. We take the stress off your plate so you can focus on your new home.
Smart Home Loans: Your Luxury Financing Partner
What happens if your financial profile isn’t perfect? We specialize in “near-miss” scenarios. If a traditional bank said no because of a minor credit dip, we have a plan. You can use our integrated tools to improve credit score for home loan eligibility. This proactive approach helps you bridge the gap to jumbo loans Florida requirements. We value your time and provide punchy, direct communication. Our goal is to make your luxury financing journey simple and successful.
Secure Your Florida Luxury Home Today
Securing a high-value property in 2026 doesn’t have to be overwhelming. You now know the baseline limits and the exact financial markers lenders look for in the luxury market. Success starts with a clear plan for your credit score and cash reserves. By choosing a local expert, you gain access to customized luxury financing solutions that traditional banks often miss. We handle the stress of complex appraisals and strict underwriting so you can focus on your move.
Don’t let confusion over jumbo loans Florida requirements hold you back from your dream estate. Our team provides expert local guidance in Saint Augustine and access to specialized credit repair services to ensure you qualify. We’re here to turn your aspirations into a reality with speed and personalized care.
Start your Florida jumbo loan pre-approval with Smart Home Loans today. We are excited to help you move into your new home.
Frequently Asked Questions
What is the 2026 jumbo loan limit for St. Johns County, Florida?
In St. Johns County, including Saint Augustine, the 2026 jumbo loan threshold is $832,750 for a single-family home. Any mortgage amount exceeding this baseline is classified as a jumbo loan. This limit is set by the FHFA and applies to most of Florida. If you’re looking at luxury estates in Ponte Vedra, tracking this number helps you plan your financing strategy effectively.
Can I get a jumbo loan in Florida with only 10% down?
Yes, you can secure 10% down payment options for jumbo loans Florida through certain specialized lenders. While a 20% down payment is the standard for accessing the lowest interest rates and most flexible terms, lower entry points are available for qualified buyers. As a local brokerage, we can help you compare different programs to find a solution that balances your cash flow and long-term goals.
Do jumbo loans in Florida require private mortgage insurance (PMI)?
Many jumbo mortgage programs in Florida don’t require private mortgage insurance, even if you put down less than 20%. Because these loans aren’t government-backed, lenders set their own rules. Some institutions build the risk into the interest rate instead of charging a separate monthly PMI fee. This can simplify your monthly payment and help you qualify for a higher-value home in the Saint Augustine market.
What credit score is needed for a Florida jumbo mortgage in 2026?
Most lenders require a minimum credit score of 700 to 720 for luxury financing in 2026. Higher scores often unlock better interest rates and lower reserve requirements. If your score is slightly lower, our team offers dedicated credit repair services to help you reach the necessary threshold. Improving your score by just a few points can make a massive difference in your monthly mortgage payment.