What if a single number from your past didn’t have the power to stop your future in Saint Augustine? It’s stressful to watch your dream of homeownership feel like it’s slipping away because of a confusing credit report. You’ve likely felt that sting of worry when thinking about a loan denial or felt lost in the sea of different scoring models like FICO 10T. You aren’t alone in this. This guide shows you exactly how to fix credit to buy a house by providing a clear, supportive roadmap for 2026.
We’ll break down the new FHA and VA score minimums, explain how recent executive orders affect your application, and give you the confidence to start your journey today. Whether you’re eyeing a 580 score for FHA home loans or aiming higher, your path to a local home starts right here.
Key Takeaways
- Understand how your credit reputation directly impacts your 2026 monthly savings and interest rates.
- Use the “10% Rule” on credit card balances to make your financial profile shine for modern lenders.
- Learn how to fix credit to buy a house by identifying and removing “low-hanging fruit” errors from your reports.
- Leverage specialized credit repair and Saint Augustine market knowledge to simplify your path to homeownership.
Why Your Credit Score Matters More Than Ever in 2026
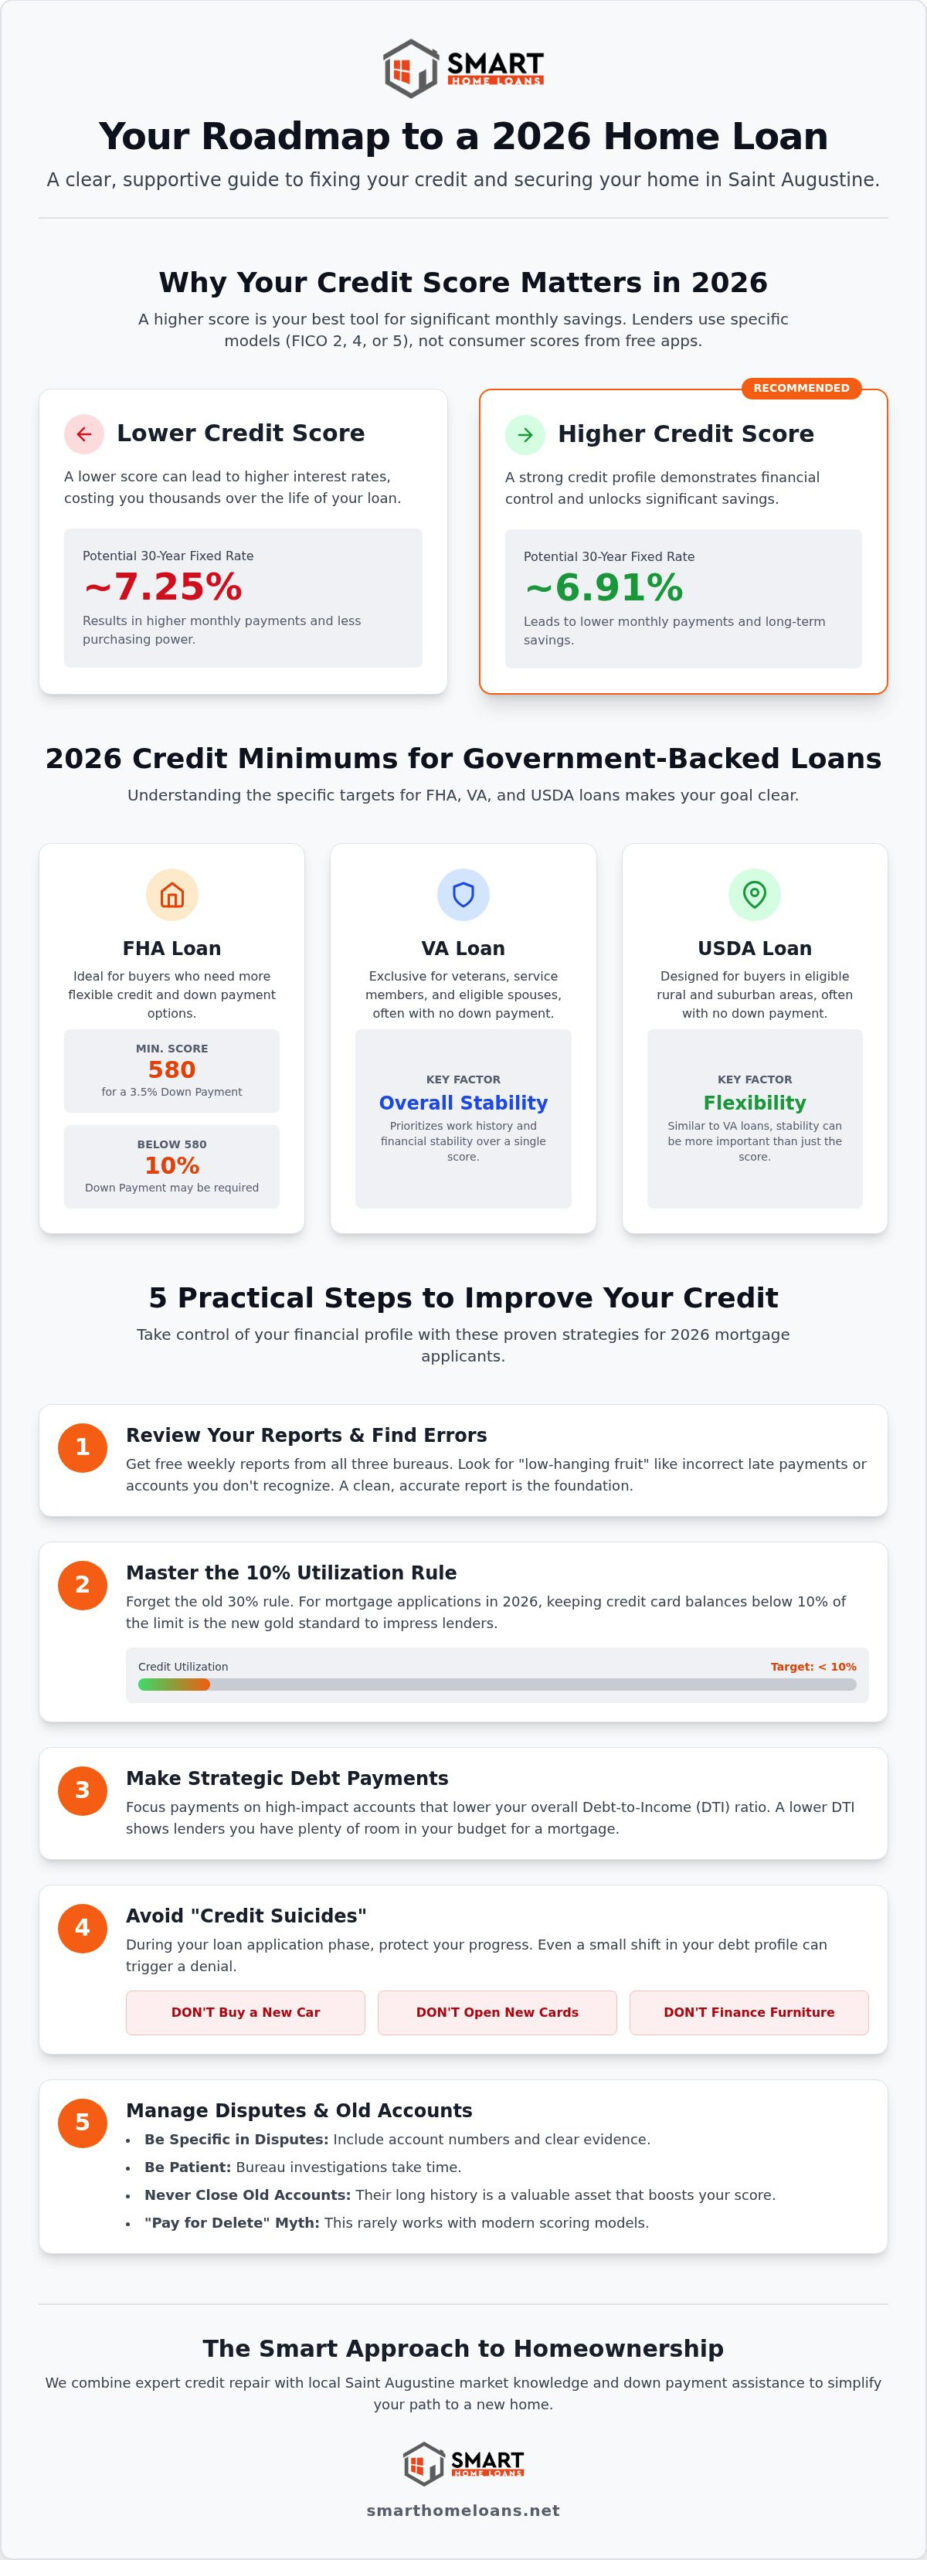
Think of your credit score as your financial reputation. In 2026, being “mortgage-ready” means more than just hitting a target number. It shows lenders you have control over your budget. With 30-year fixed rates currently between 6.91% and 7.25%, a higher score is your best tool for significant monthly savings. Start by understanding your credit score and how it differs from what you see on free apps. Lenders look at specific FICO models like FICO 2, 4, or 5. These are different from the consumer scores found on Credit Karma. It’s a different lens, but we can help you focus it.
A past financial mistake is just a chapter. It isn’t the whole book. If you’re researching how to fix credit to buy a house, you’ve already taken the hardest step. We see your potential, not just your past. We believe every neighbor in Saint Augustine deserves a fair shot at a front door key.
2026 Credit Minimums for FHA, VA, and USDA Loans
Government-backed loans are a fantastic resource for local families. For an FHA loan, a 580 score is the standard benchmark for a 3.5% down payment. If your score is lower, you might still qualify with a 10% down payment. VA and USDA loans provide even more flexibility for veterans and rural buyers. These programs often prioritize your overall stability and work history over a single digit. Check out our deep dive on an FHA Loan with Bad Credit in Florida: Your 2026 Path to Homeownership to see what’s possible. Learning how to fix credit to buy a house is much easier when you know exactly what the finish line looks like.
5 Practical Steps to Improve Your Credit Score for a Mortgage
Start by grabbing your free weekly credit reports from all three bureaus. Look for “low-hanging fruit” like incorrect late payments or accounts you don’t recognize. Understanding how credit scores work helps you spot these red flags quickly. Fixing small errors is often the fastest way to see a jump in your numbers. Learning how to fix credit to buy a house starts with a clean, accurate report.
Forget the old 30% rule for credit utilization. In 2026, the gold standard for mortgage applicants is keeping credit card balances below 10%. Focus your strategic debt payments on high-impact accounts that lower your Debt-to-Income (DTI) ratio. This makes you look much safer to lenders during the review process. A lower ratio shows you have plenty of room in your budget for a new Saint Augustine home.
Protect your progress by avoiding “credit suicides.” Don’t buy a new car, open new credit cards, or finance large furniture during this phase. Even a small shift in your debt profile can trigger a loan denial. If you feel overwhelmed, our credit repair experts can help you prioritize your next move with a personalized plan.
Disputing Errors and Managing Old Collections
When writing a dispute letter, be specific. Include account numbers and clear evidence for why the information is wrong. Results take time, so be patient while the bureaus investigate. Don’t fall for the “Pay for Delete” myth; it rarely works with today’s sophisticated scoring models. Finally, never close old accounts. Their long history is a valuable asset that keeps your score higher. Keeping them open shows you can manage credit over the long haul.
How Smart Home Loans Simplifies Your Path to Ownership
At Smart Home Loans, we believe your credit score shouldn’t be a wall. It’s a bridge we build together. Our dedicated Credit Repair services go beyond simple advice. We roll up our sleeves to help you resolve errors and build a stronger profile. We know Saint Augustine. We understand the Florida-specific lending rules that others might miss. This local expertise means we navigate the process faster and more effectively for you. You deserve a neighborly expert who cares about your success.
You aren’t just another file to us. We act as your advocate with lenders. We help explain the real story behind your score, showing them your true financial potential. If you’re looking for more details on specific programs, check out our Government Backed Home Loans Florida: Your 2026 Guide to FHA, VA, and USDA. Learning how to fix credit to buy a house is the first step, but having a proactive partner makes the journey much smoother.
Combining Credit Repair with Down Payment Assistance
Many buyers don’t realize they can fix their credit and look for assistance at the same time. Our team helps you find grants and programs right here in Saint Augustine to bridge the funding gap. This “Smart” approach secures Down Payment Assistance while we polish your credit reputation simultaneously. It’s about maximizing every opportunity available to you in 2026. Ready to get started? Start your journey today with a supportive credit review and see how close you really are to your dream home.
Your Saint Augustine Home is Closer Than You Think
Repairing your credit isn’t just about cleaning up the past. It’s about opening doors to your future. You’ve learned that keeping balances low and auditing your reports for errors can drastically shift your standing with lenders. Remember; a 580 score is often all it takes to unlock FHA options. Knowing exactly how to fix credit to buy a house gives you the power to stop waiting and start planning for your family’s next chapter.
Our team at Smart Home Loans provides specialized credit repair support and deep local Saint Augustine knowledge to guide you. We’re FHA and VA loan experts who see the person behind the paperwork. You don’t have to navigate these complex 2026 requirements alone. Ready to fix your credit and find your home? Let’s build your plan today. We’re here to be your neighborly advocate every step of the way. Your new front door is waiting for you.
Frequently Asked Questions
How long does it take to fix my credit to buy a house?
Most Saint Augustine buyers see significant results within three to six months. The exact timeline depends on whether you’re disputing errors or paying down high balances. Credit bureaus typically have 30 days to investigate disputes. Consistent, on-time payments will build your score over time. Start today and we’ll show you exactly how to fix credit to buy a house.
Can I buy a house with a 500 credit score in Florida?
Yes, you can qualify for an FHA loan with a 500 credit score, though it requires a 10% down payment. If you can reach a 580 score, that requirement drops to just 3.5%. Our Saint Augustine team specializes in these government-backed programs. Let us help you find down payment assistance to make the 10% requirement more manageable while you work on your scores.
Will checking my credit for a mortgage hurt my score?
A hard inquiry for a mortgage application might dip your score by a few points temporarily. However, credit models recognize mortgage shopping. If multiple lenders check your credit within a 14 to 45 day window, it usually counts as a single inquiry. Shop for your best rate without fear of a major score drop. We always prioritize your score’s health during the pre-approval process in Saint Augustine.
Is it better to pay off collections or save for a down payment first?
The right choice depends on the age of the debt and your specific loan goals. Paying off an old collection can sometimes temporarily lower your score by resetting the account’s “last activity” date. Saving that cash for a down payment might be more beneficial for Saint Augustine buyers. Let’s analyze your unique situation to determine the best way how to fix credit to buy a house.