What if the amount on your mortgage pre-approval letter is more than you’d feel comfortable spending? Mortgage pre-approval in Florida can help bring focus to your home search, but the amount you may be able to borrow is not the same as a monthly payment that fits your life. It’s common to have questions about pre-approval versus pre-qualification, credit checks, and which documents to gather.
This guide walks you through practical steps to prepare, understand the review, and use an approval amount as a planning tool rather than a spending target. You’ll learn what lenders may review, how to think about a comfortable budget, and what to do next as you prepare to look for a home in Florida. Smart Home Loans can also help you discuss mortgage options, including FHA, VA, and USDA loans.
Key Takeaways
- Learn what a lender’s preliminary review can tell you, and why it isn’t a final loan commitment.
- Use this mortgage pre-approval Florida guide to organize the financial records commonly needed to get started.
- See how loan-option discussions and the application process can help shape your next steps.
- Set a home-search budget around a comfortable monthly payment, and know when changes may call for a lender to revisit your file.
Mortgage pre-approval in Florida: what it means, and what it does not
A mortgage pre-approval is a lender’s preliminary review of your financial information to estimate how much you may be able to borrow. It gives you a more informed starting point for planning a home search, but it isn’t a final loan commitment. Depending on the lender and application, the review may consider your income, debts, assets, and credit. The estimate reflects the information available at that stage.
Pre-qualification is often an earlier estimate based on information you provide, which may receive less verification. Lenders don’t all use these terms in the same way, and the steps behind each can differ. Focus on what the lender actually reviewed rather than relying on the label on a letter. For a general overview of mortgage pre-approval, see Wikipedia’s explanation of the process and how it differs from pre-qualification.
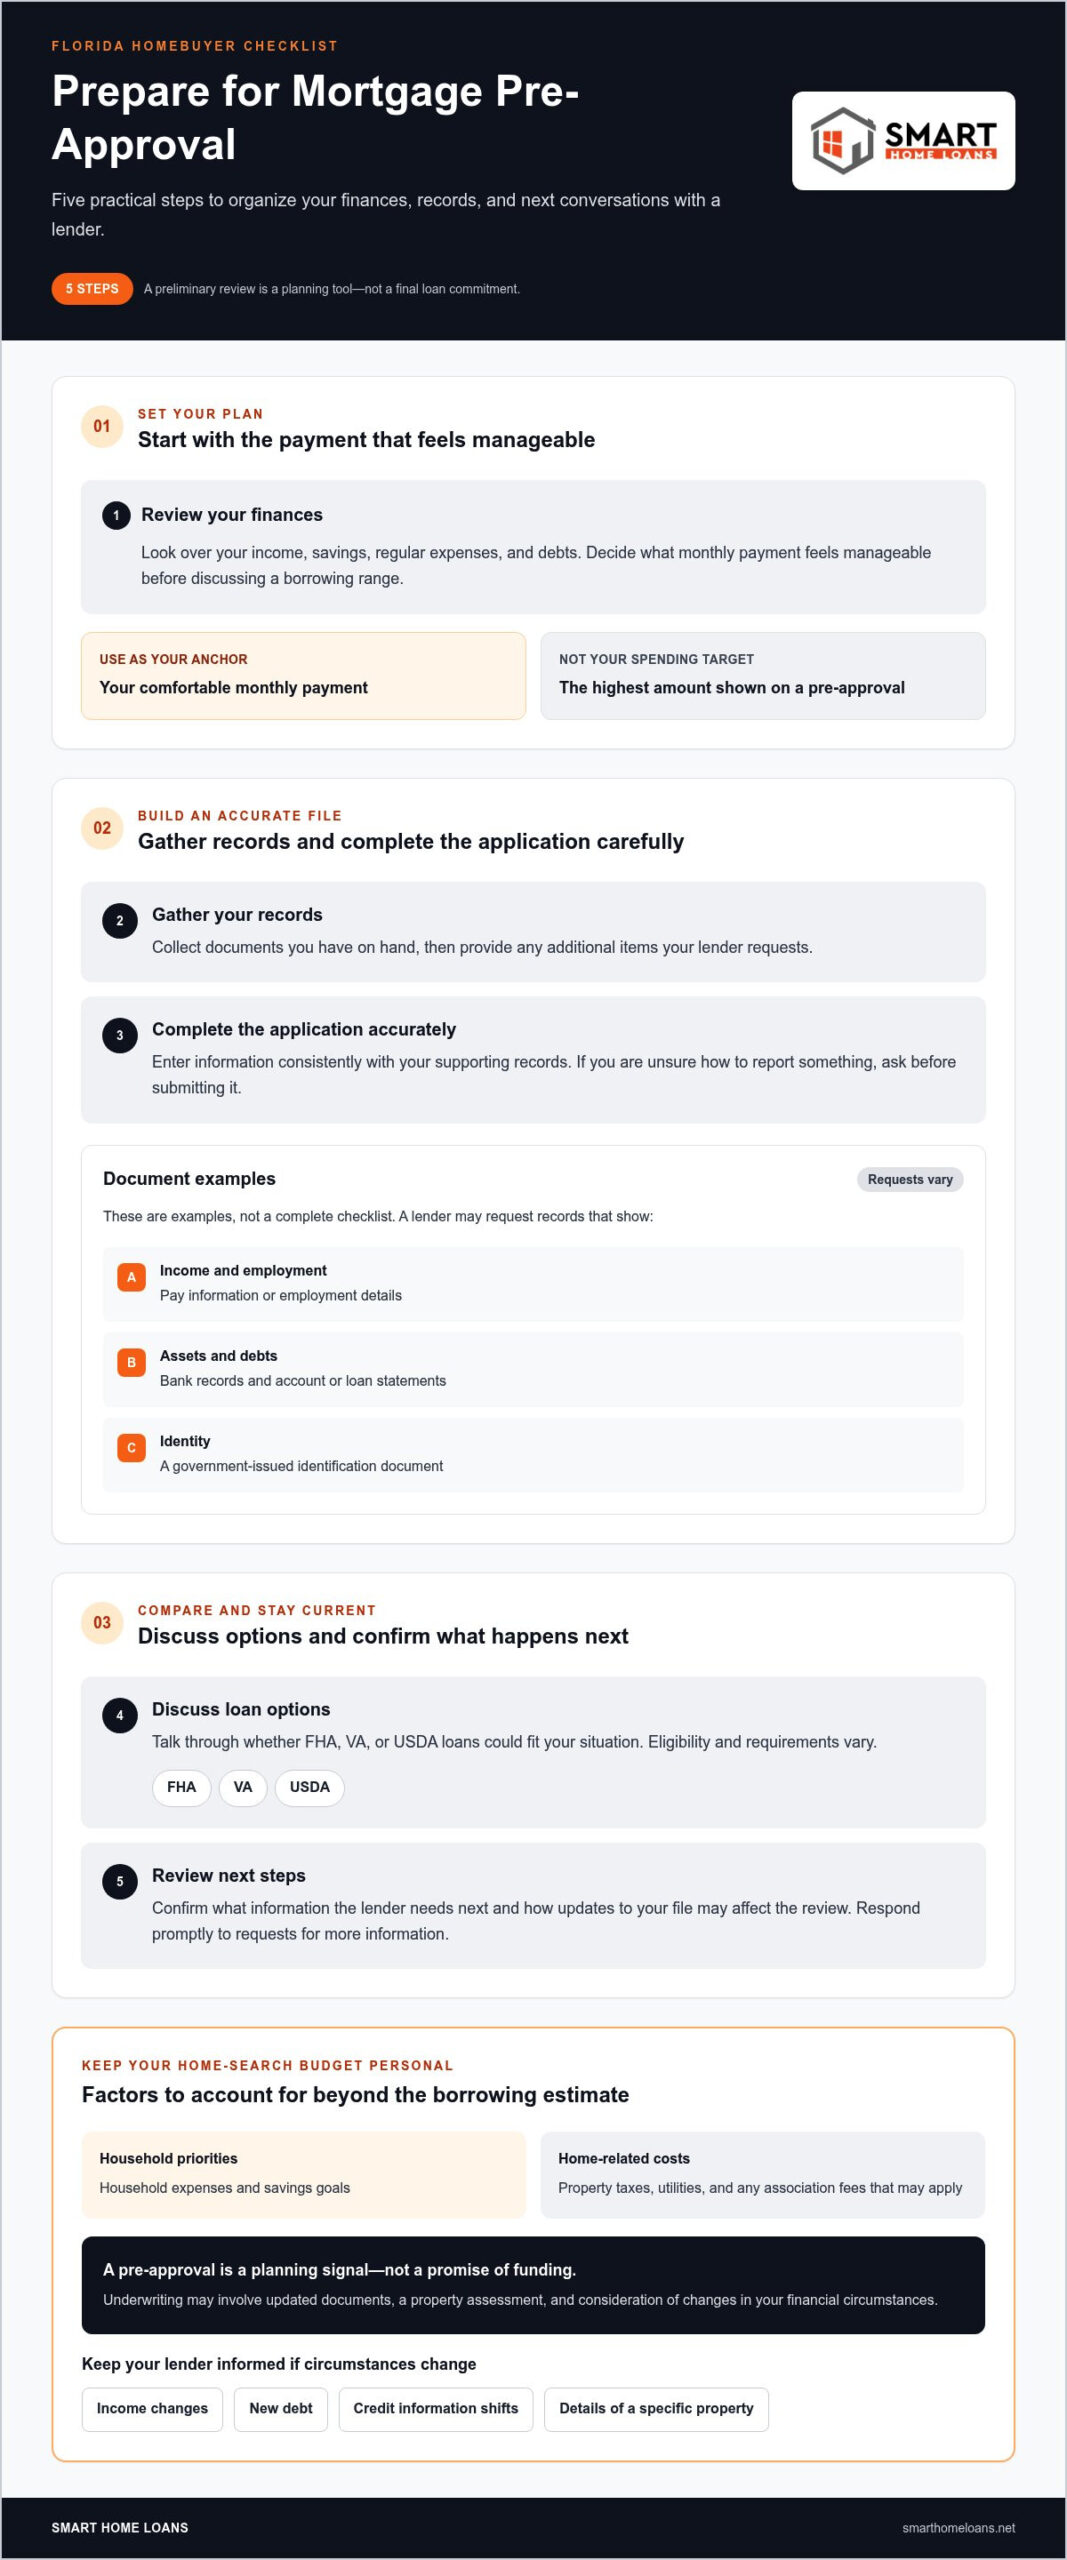
A mortgage pre-approval Florida homebuyers can use as a planning tool helps frame conversations about loan options and potential homes. It doesn’t set your personal spending limit. An estimated borrowing range may not account for household priorities such as childcare, savings goals, transportation, or the flexibility you want in your monthly budget. Set your home-search target around a payment you can manage, not simply the highest amount shown.
Does mortgage pre-approval guarantee a Florida home loan?
No. Treat pre-approval as a planning signal, not a promise of funding. Before making a final lending decision, underwriting may involve reviewing updated documents, assessing the property, and considering changes in your financial circumstances. A change in income, new debt, or details about a home you’re considering could affect the review. Keep your records accurate and tell your lender about material changes so your file can be reassessed as needed.
How to prepare for mortgage pre-approval in Florida
Preparing your financial information before applying can make it easier to complete the application and discuss your plans. Work through these steps:
- Review your finances. Look over income, savings, regular expenses, and debts. Decide what monthly payment feels manageable before discussing a borrowing range.
- Gather your records. Collect the documents you have on hand, then provide any additional items the lender requests.
- Discuss loan options. Talk through whether FHA, VA, or USDA loans could fit your situation. Eligibility and requirements vary.
- Complete the application. Enter information accurately and consistently. If you’re unsure how to report something, ask before submitting it.
- Review next steps. Confirm what information the lender needs next and how updates to your file may affect the review.
Relate your budget to the home you hope to buy. If you’re searching in Saint Augustine, consider the area and the kind of home you want when discussing a realistic price range. Smart Home Loans offers down payment assistance as part of its mortgage support. For information about Florida programs and eligibility, visit the Florida Housing Finance Corporation.
Which documents should you gather before applying?
Document requests vary, so use these as examples rather than a complete checklist. A lender may ask for records that show:
- Income and employment, such as pay information or employment details
- Assets and debts, such as bank records and account or loan statements
- Identity, such as a government-issued identification document
Check that the details in your application match your supporting records, and respond promptly to requests for more information. For an overview of how preparation fits into the broader Florida mortgage process from pre-approval to closing, review the steps ahead. Smart Home Loans can also help you discuss loan options as you prepare. Explore mortgage guidance for Florida buyers.
Plan next steps with your Florida mortgage pre-approval
Use the estimated borrowing range as a starting point, then set your home-search budget around a monthly payment you can comfortably manage. Consider your household expenses, savings goals, property taxes, utilities, and any association fees that may apply. Your target is personal, and you don’t have to shop at the top of the range.
Keep your lender updated as your search progresses. A change in income, new debt, a shift in credit information, or details about a specific property could affect the review. Before making a major financial change, consider how it could affect your homebuying plans and discuss it with your lender. For background on Florida’s mortgage-lending framework, consult the Florida Statutes Chapter 494.
Which loan path could fit your Florida home search?
FHA, VA, and USDA loans have different eligibility and property guidelines. Jumbo loans are another option for some financing needs, with criteria that differ from other loan types. The right path depends on your circumstances and the home you’re considering. Use your mortgage pre-approval Florida discussions to compare which options may fit your plans. Explore this Florida guide to government-backed home loans for more on FHA, VA, and USDA programs.
Smart Home Loans is a Saint Augustine mortgage brokerage that helps buyers discuss loan options and pre-approval as they plan a Florida home search. The brokerage offers FHA, VA, USDA, and jumbo loans, along with down payment assistance. To discuss your next steps, talk with Smart Home Loans.
Take your next step toward a Florida home
A home search is more purposeful when your financing plan reflects the life you want to build, not just a number on paper. Keep your priorities in view as you compare homes, and leave room to adjust if your plans or circumstances change. Mortgage pre-approval Florida buyers receive is a starting point for informed decisions, not a reason to rush toward the biggest possible purchase.
Sean manages Smart Home Loans under NMLS ID 1734077. If you’re preparing to buy in Saint Augustine or elsewhere in Florida, start a conversation about your mortgage options and pre-approval. Start your Florida mortgage pre-approval conversation.
Frequently Asked Questions
How long does mortgage pre-approval take in Florida?
There isn’t one timeline for mortgage pre-approval in Florida. The review may move faster when your application is complete and your records are organized, but timing depends on the lender’s process and whether more details are needed. Gather your documents before applying and respond promptly to requests to help keep the process moving.
Does getting pre-approved for a mortgage affect your credit score?
It can. A lender may make a credit inquiry when reviewing your application, and the effect depends on the inquiry and your credit profile. Ask whether the review involves a hard or soft inquiry before applying. If you’re comparing options, understand how each lender handles credit checks so you can make an informed choice.
How long does a mortgage pre-approval last?
The validity period depends on the lender, so check the date and any expiration details on your letter. If it expires before you find a home, the lender may need updated information to refresh the review. Tell your lender if your income, debts, or credit circumstances change while you’re searching in Saint Augustine or elsewhere in Florida.
Can I make an offer on a Florida home with a pre-approval letter?
Yes. Buyers commonly submit a pre-approval letter with an offer, but it doesn’t guarantee that the seller will accept the offer or that financing will be finalized. For a Saint Augustine home, coordinate the letter with your offer timing and the specific property details. Keep your lender informed as the purchase progresses so they can address any needed updates.