Could a VA home loan St. Augustine buyers may qualify for make buying a home feel more manageable? It can be a helpful option, but eligibility is only one part of a confident purchase. The home’s condition, appraisal, taxes, insurance, and other ongoing costs matter, too.
If you’re unsure about service eligibility, entitlement, or what a lender will need, start by getting a clear picture of each. This guide explains how VA financing works and what to prepare before discussing your options with a mortgage professional. You’ll learn what to consider when evaluating a St. Augustine property, how local costs can affect your budget, and how to move from comparing possibilities to a financing plan. Smart Home Loans offers VA loans for buyers in Saint Augustine.
Key Takeaways
- Understand how a VA-backed purchase loan works and how a lender reviews eligibility, entitlement, and financing options.
- For a VA home loan St. Augustine purchase, weigh your financial readiness alongside the property’s condition and fit.
- Know what a VA appraisal evaluates and why it serves a different purpose than a separate home inspection.
- Prepare income, asset, debt, and service documentation, then include local property costs in your offer planning.
How a VA Home Loan Can Support Your St. Augustine Purchase
A VA-backed purchase loan is made by a private lender, with the Department of Veterans Affairs guaranteeing part of the loan. That backing can make financing more accessible for eligible borrowers, but it doesn’t guarantee approval or determine every loan term. The lender reviews your finances and the property before deciding whether the transaction meets its requirements. For background on the VA loan program, you can also explore its history and purpose.
Depending on your eligibility, entitlement, lender review, and the home’s appraised value, VA financing may allow you to buy without a down payment. That isn’t automatic. Your finances and the details of the transaction matter. Smart Home Loans offers VA loans to help St. Augustine buyers consider their financing options.
Who may qualify for VA home loan financing?
Service history affects eligibility. Common pathways include 90 continuous days of active duty, 181 days of peacetime active duty, or six years in the National Guard or Reserves. Requirements can depend on your service circumstances. A Certificate of Eligibility (COE) documents whether you meet VA program requirements. A lender can help review the documentation needed to obtain it.
Entitlement is the amount of VA backing available for your loan, not an approval. Even with a COE and available entitlement, the lender separately reviews your credit, income, debts, and assets. The home’s value matters, too: the appraisal helps assess whether the property supports the proposed financing. Eligibility, entitlement, underwriting, and property value all shape the final picture, so treat the COE as a starting point, not a promise of financing.
What St. Augustine VA Buyers Should Evaluate Before Making an Offer
A strong offer starts with more than the home price. For a VA home loan St. Augustine purchase, consider your financial readiness, the property’s condition, and the full monthly budget together. The VA home loan benefits page explains official program details. A mortgage review can help connect those details to your purchase plans.
| What to review | Questions to consider |
|---|---|
| Borrower preparation | Are your income, assets, debts, and service documents organized for lender review? |
| Property suitability | Does the home’s visible condition and location fit your needs and budget? |
| Financing and carrying costs | How might the appraisal, St. Johns County property taxes, and insurance costs affect your plan? |
Local costs can vary from one property to another. Review property tax information for the specific address and account for insurance as you compare homes. The location, roof condition, and potential flood exposure may also affect your estimate of ongoing expenses. Include these costs in your budget before settling on an offer amount.
How do the VA appraisal and home inspection differ?
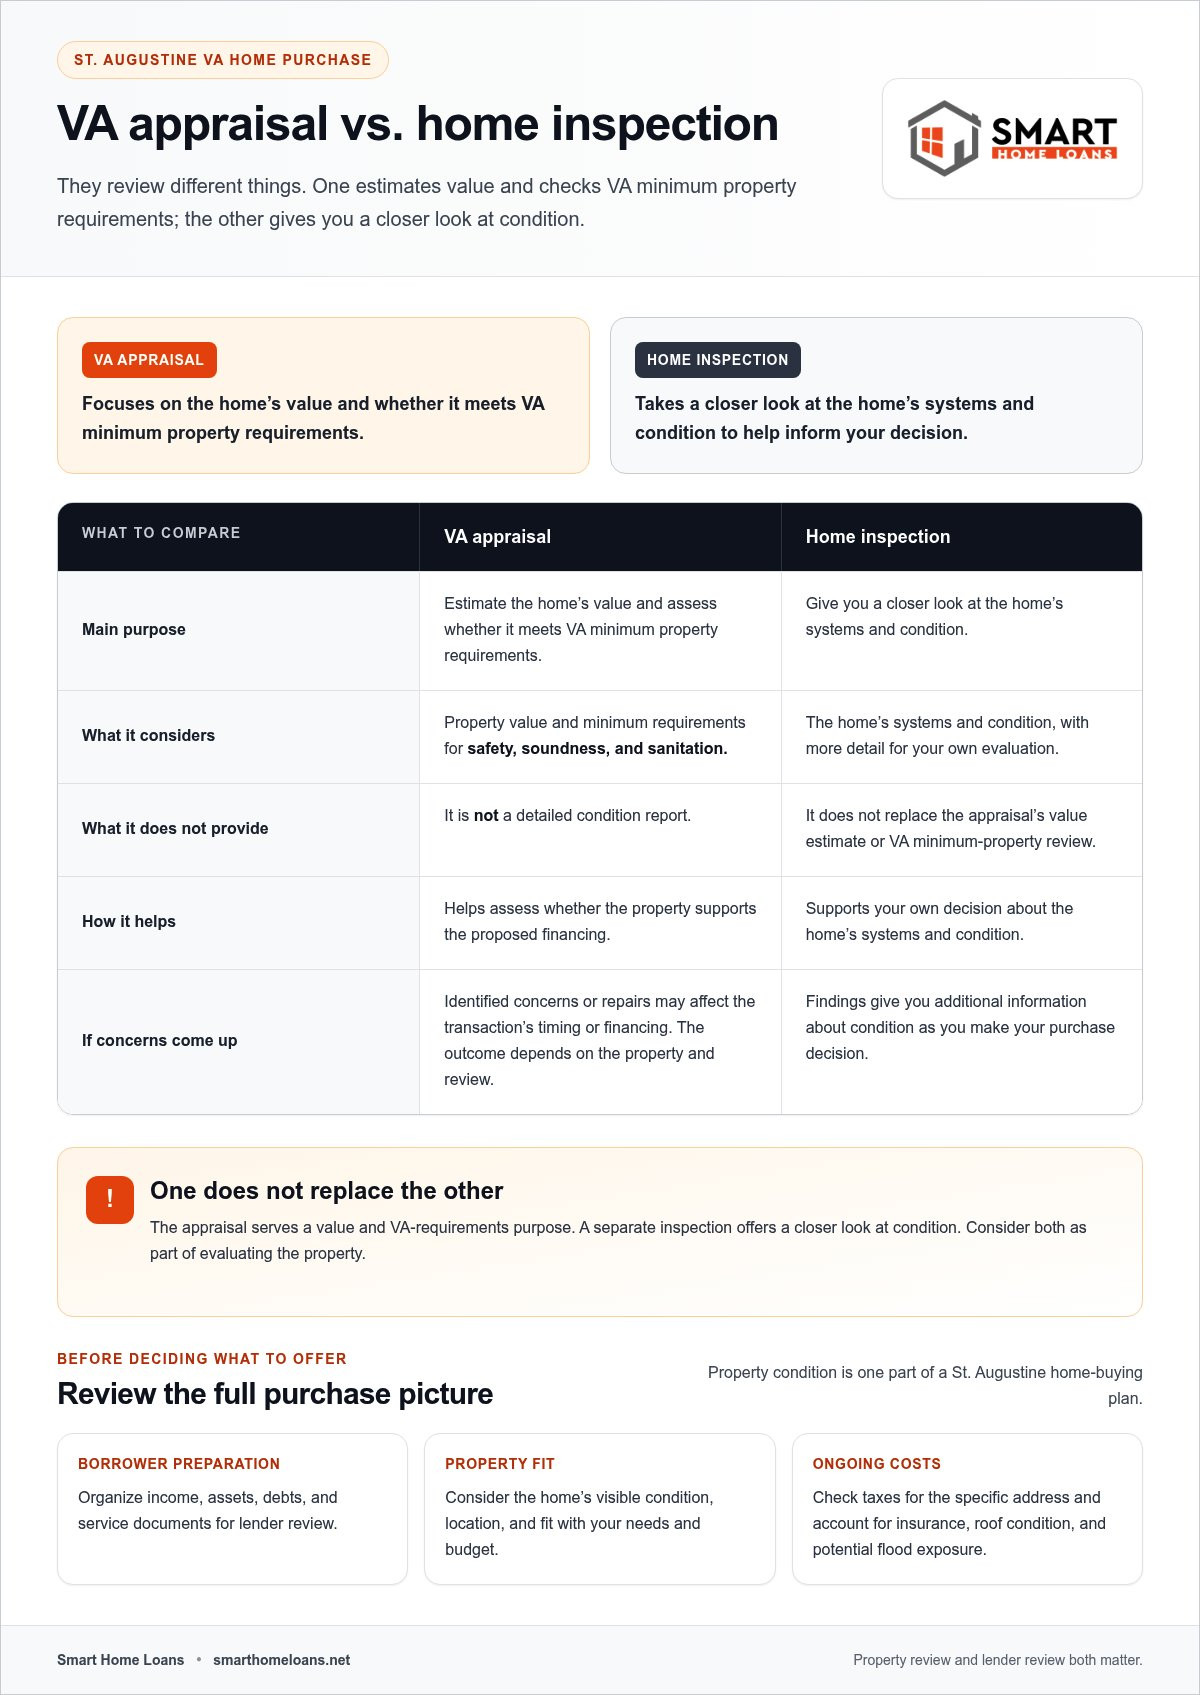
A VA appraisal estimates the home’s value and checks whether it meets the VA’s minimum property requirements for safety, soundness, and sanitation. It isn’t a detailed condition report. A separate home inspection gives you a closer look at the home’s systems and condition to support your own decision. One doesn’t replace the other. If the appraisal identifies concerns or repairs, they may affect the transaction’s timing or financing. The outcome depends on the property and review.
Review borrower readiness, property fit, and financing together before deciding what to offer. Learn about VA mortgage financing as you plan your St. Augustine purchase.
Your Next Steps for a VA Home Loan in St. Augustine
Turn what you’ve learned into a practical plan. Start with the steps below, then use what you gather to guide a financing conversation and shape an offer strategy that fits your goals.
- Review eligibility: Gather service information and check your Certificate of Eligibility status. The U.S. Department of Veterans Affairs explains VA home loan benefits and program steps.
- Organize your finances: Collect income, asset, and debt information so a lender can review your financial picture.
- Discuss the transaction: Share your target areas, property needs, and comfortable monthly budget. Include expected property costs as you compare options and review Florida’s mortgage process.
- Prepare an offer strategy: Use the financing discussion and your property priorities to decide what fits before pursuing a specific home.
What should you prepare before discussing your VA financing?
Bring available service documentation and a snapshot of your income, assets, and debts. Note the St. Augustine areas you’re considering, the features you need, and a monthly payment range that feels manageable. These details support an informed initial review, not a promise of approval.
Pre-approval is an early financing assessment, not a final loan commitment. The lender’s review continues as your application and property details develop.
A VA home loan St. Augustine plan should reflect both your finances and the home you hope to buy. Smart Home Loans offers VA financing for buyers in Saint Augustine, helping you understand your next steps.
Take the Next Step With a Clear Financing Plan
A confident purchase starts with knowing what to review. Check your VA eligibility and entitlement, prepare your financial documents, and consider how the home’s condition, appraisal, taxes, and insurance fit your budget. Together, these factors help shape a realistic plan, while lender review and property details determine the financing outcome.
If a VA home loan St. Augustine purchase is on your mind, Smart Home Loans offers VA loans to Saint Augustine buyers. Sean manages the brokerage and can be your point of contact as you discuss your financing goals and next steps.
Bring your questions, service records, and a sense of what you want in a home. Talk with Smart Home Loans about your St. Augustine VA home purchase and take the next step with a clearer financing plan.
Frequently Asked Questions
Who is eligible for a VA home loan in St. Augustine?
Eligibility generally depends on your military service history and VA program requirements. Common service pathways include 90 continuous days of active duty, 181 days of peacetime active duty, or six years in the National Guard or Reserves. A Certificate of Eligibility (COE) documents your program eligibility. A lender separately reviews credit, income, debts, and assets, so a COE isn’t a loan approval.
Can you buy a home in St. Augustine with a VA loan and no down payment?
Potentially, if you’re eligible, have full VA entitlement, and meet lender requirements for the transaction. The home’s appraised value and your overall application matter, too. No down payment isn’t guaranteed for every purchase, and other costs may still affect your budget. Review the full financing picture with a mortgage professional before deciding what you can comfortably offer on a St. Augustine home.
Does a VA loan require a home inspection in Florida?
A VA appraisal is required for the loan, but it isn’t the same as a buyer’s home inspection. The appraisal estimates value and checks whether the property meets VA minimum property requirements. A separate inspection gives you a closer look at the home’s condition and can help inform your decision. For a Florida property, consider both steps as you assess the home and potential repair needs.
How do you get started with a VA home loan in St. Augustine?
For a VA home loan St. Augustine purchase, start by reviewing your eligibility and Certificate of Eligibility status. Then gather service records and information about your income, assets, and debts. Share your target areas, property priorities, and comfortable monthly budget with a mortgage professional. Smart Home Loans offers VA loans in Saint Augustine and can help you understand financing options. An early review isn’t a final approval.