What if qualifying for a VA benefit is only the first step toward buying a home in Florida? A veteran home loan Florida buyers can use may offer valuable financing options, but VA eligibility and mortgage approval are separate decisions. Knowing what each step involves can help you prepare before you start house hunting.
If you’re unsure how to get your Certificate of Eligibility, concerned about your credit, income, or savings, or trying to estimate the full cost of a home in Saint Augustine, you’re not alone. Start by gathering the information a lender will review, then build your budget around the home and its ongoing costs.
This guide explains how VA home financing works, what can affect approval, and which financial and property details to prepare. You’ll also learn how Florida property taxes, homeowners insurance, and your choice of home fit into affordability planning, plus how Smart Home Loans can help you explore VA financing in Saint Augustine.
Key Takeaways
- A veteran home loan Florida plan starts with understanding the difference between meeting VA service requirements, getting a Certificate of Eligibility, and qualifying with a lender.
- Prepare for five checks: service eligibility, your COE, finances, the property, and lender review.
- Review your income, credit, savings, and recurring debts together. No single detail tells the whole story.
- Organize your documents, discuss financing, choose a suitable primary residence, and be prepared for appraisal and property review.
Veteran Home Loans in Florida: How VA Financing Works
A VA-backed mortgage is a home loan made through a lender with a VA guarantee. The guarantee helps protect the lender if the borrower can’t repay. The lender reviews the application and makes the mortgage decision. Understanding this distinction is a useful first step when exploring a veteran home loan Florida buyers can use.
Military service may make you eligible for the VA benefit, but eligibility alone doesn’t approve a mortgage. A Certificate of Eligibility (COE) documents that you meet the VA’s service requirements. The lender separately reviews your finances and the home to decide whether the loan meets its requirements. For a broader comparison of FHA, VA, and USDA options, see this government-backed home loan guide.
What do VA eligibility and entitlement mean?
Eligibility relates to your military service and whether you can use the benefit. Your COE is evidence of that eligibility, not mortgage approval. Entitlement is the amount of the VA guarantee available for your loan. It can affect how the benefit applies, including whether a no-down-payment option may be possible. Entitlement details vary by borrower and loan history, so consult current VA guidance for your circumstances.
Qualified borrowers may be able to buy with no down payment, subject to available entitlement, lender requirements, and property conditions. That doesn’t mean every eligible applicant will qualify for every home. The lender still evaluates the full application. The VA loan program offers background on how the benefit works. For decisions about your own eligibility or entitlement, use current VA guidance and discuss your application with a lender.
How to Qualify for a Veteran Home Loan in Florida: Five Checks
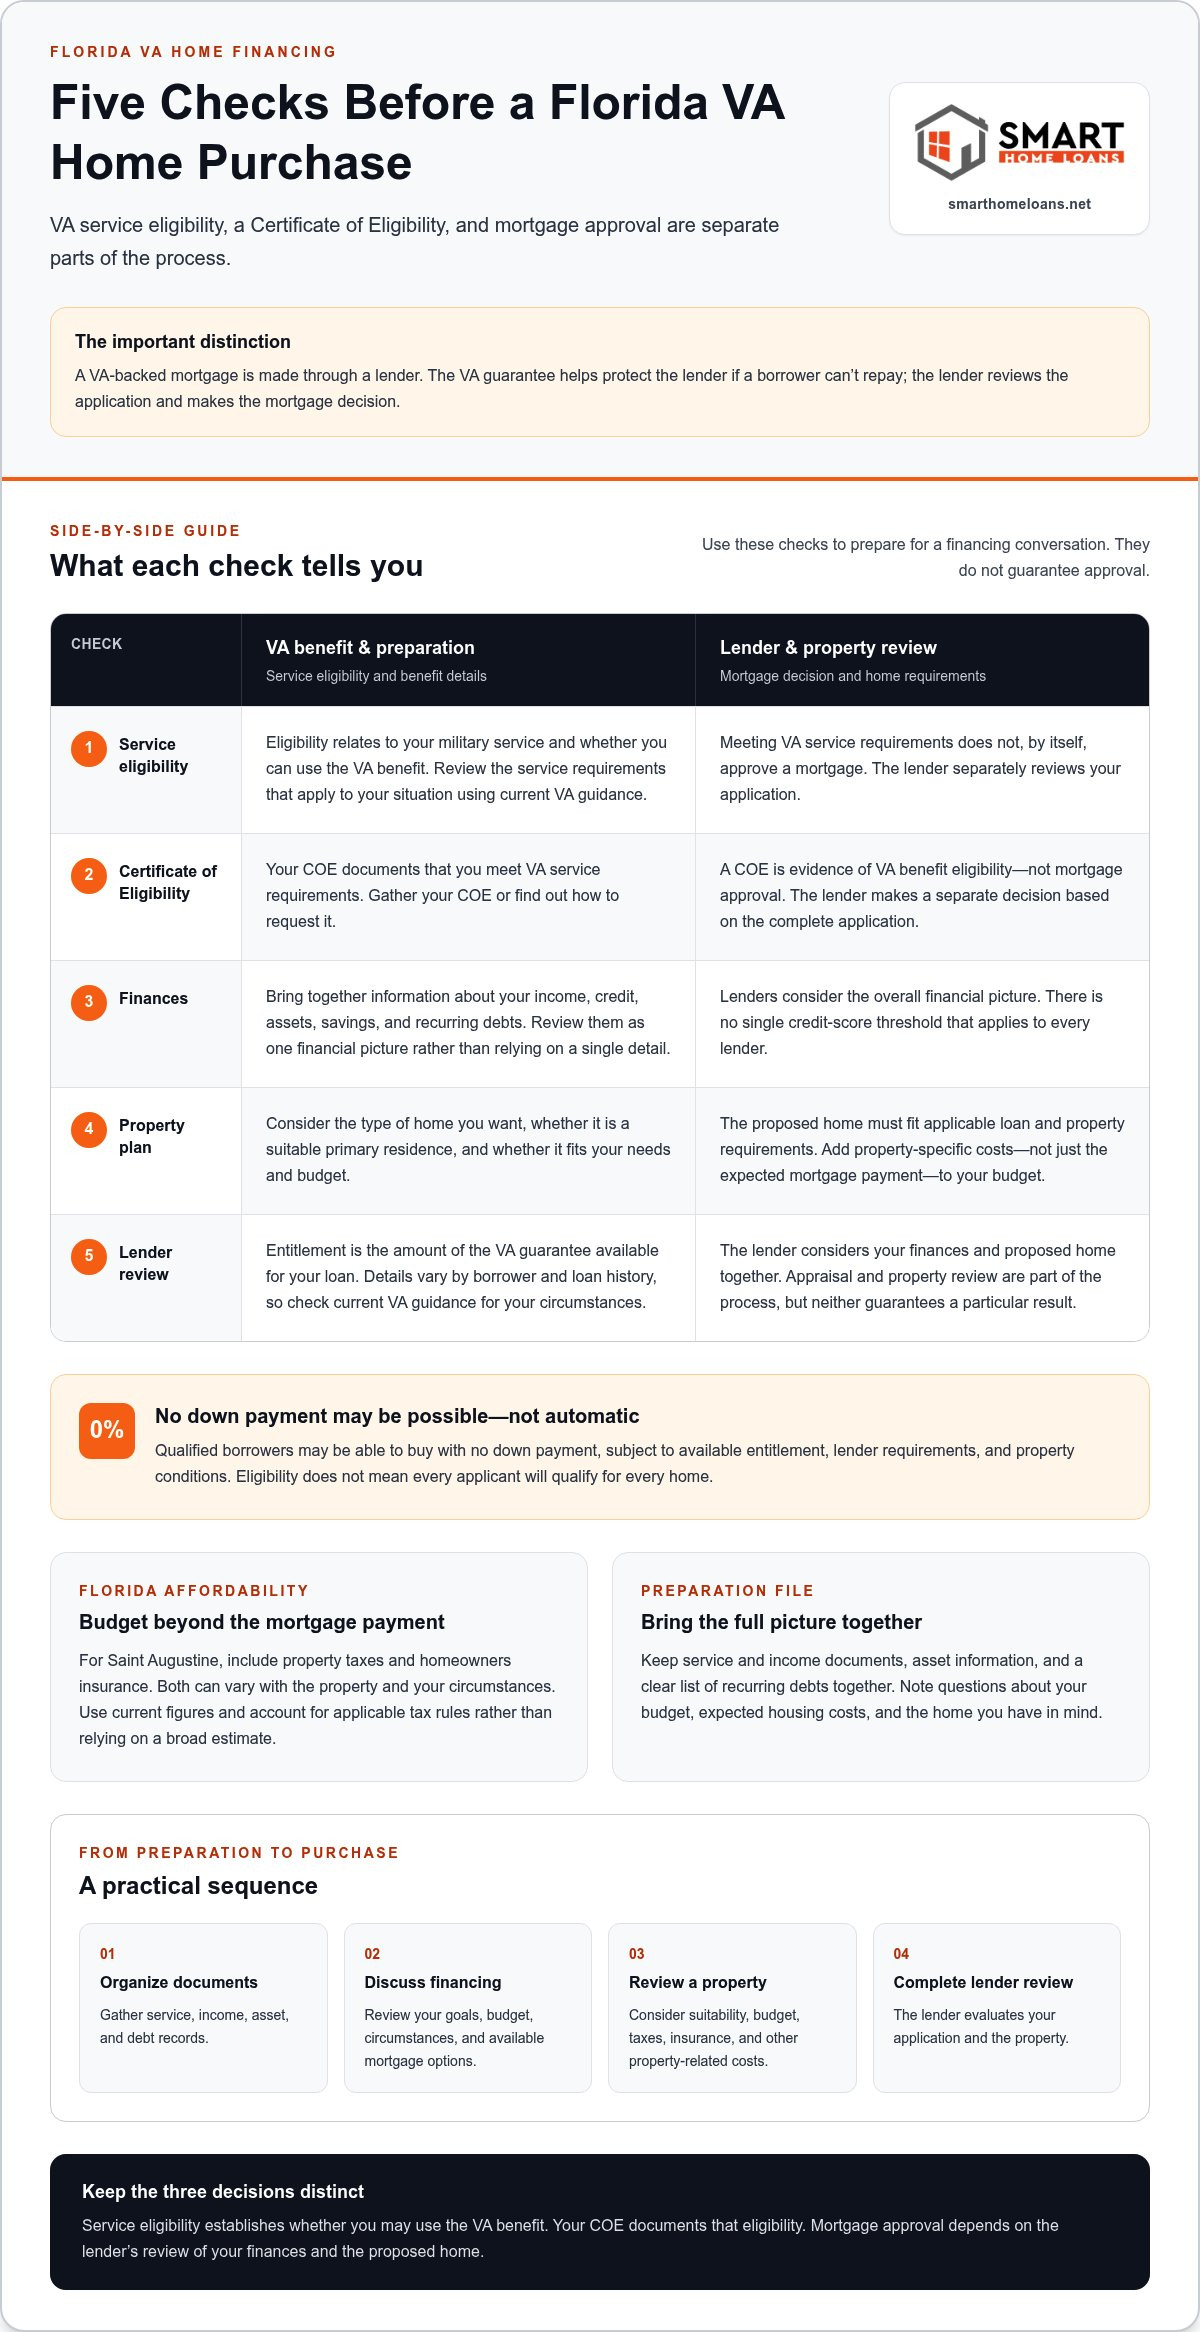
Use these five checks to organize your plans for a veteran home loan Florida buyers may pursue. They can help you prepare for a financing conversation, but they don’t guarantee approval.
- Service eligibility: Review the service requirements that apply to your situation using current VA housing assistance benefits guidance.
- Certificate of Eligibility: Gather your COE or find out how to request it. The document establishes VA benefit eligibility, while the lender makes a separate mortgage decision.
- Finances: Prepare to discuss income, credit, assets, savings, and recurring debts. Lenders consider the overall financial picture, and there’s no single credit-score threshold that applies to every lender.
- Property plan: Think about the type of home you’re seeking and whether it fits the loan’s requirements. Add property-specific costs to your budget, not just the expected mortgage payment.
- Lender review: The lender considers your finances and proposed home together. Approval depends on the complete application and applicable requirements.
What should Florida veteran buyers prepare before applying?
Gather service and income documents, information about your assets, and a clear list of recurring debts. Having these details together makes it easier to discuss your credit, income, assets, debts, and proposed home as one financial picture. Write down questions about your budget and the costs you expect for the home, too.
For Saint Augustine buyers, include property taxes and homeowners insurance in your budget. Both can vary with the property and your circumstances, so use current figures and account for applicable tax rules rather than relying on a broad estimate. A mortgage discussion can help you organize questions around the home you have in mind. Discuss your Florida home loan plans as you prepare.
From VA Loan Preparation to a Florida Home Purchase: Your Next Steps
A clear sequence can make the move from preparation to a home purchase more manageable. First, organize your service, income, asset, and debt documents. Then discuss your goals, budget, and financing options with a mortgage professional before focusing on a property.
- Organize your documents. Keep financial and service records together. Make a list of questions about your budget, expected housing costs, and plans for buying.
- Discuss financing. Review your circumstances and available mortgage options. A guide to VA loans can help you understand common features and prepare questions.
- Review a suitable property. Consider whether the home fits your needs and budget, including property-related costs such as taxes and insurance.
- Complete lender review. The lender evaluates your application and the property. Appraisal and property review are part of this process, but neither guarantees a particular result.
How can a mortgage broker help you move forward?
A mortgage broker can help connect your goals and financial circumstances with available mortgage options and guide your financing discussion as you prepare. Smart Home Loans offers VA loans and serves homebuyers in Saint Augustine. For a broader look at the application stages, read the Florida mortgage process guide. It explains how early preparation fits into the wider path toward closing.
Every buyer’s situation is different. If you’re considering a veteran home loan Florida purchase, reviewing your documents, budget, and plans for a primary residence can help you identify practical next steps. Talk with Smart Home Loans about your Florida home loan.
Take Your Next Step Toward a Florida Home
A veteran home loan Florida plan starts with understanding the difference between VA eligibility, your Certificate of Eligibility, and lender approval. Next, prepare your financial documents and estimate the full cost of a property, including applicable taxes and insurance.
Take it one step at a time: organize your information, discuss financing, review a suitable home, and work through the lender’s application and property review. VA eligibility can open a path to financing, but approval depends on the complete application and property review.
Smart Home Loans offers VA loans to borrowers in Saint Augustine. Connect with Smart Home Loans to discuss your Florida home plans and take the next step toward VA financing.
Frequently Asked Questions
Can I buy a home in Florida with a VA loan and no down payment?
Eligible borrowers may be able to buy a Florida home without a down payment if their entitlement, lender approval, and the property meet applicable requirements. This option isn’t guaranteed for every transaction. Closing costs and other expenses may still apply, so include them in your budget as you explore a veteran home loan Florida option.
Does having a Certificate of Eligibility mean my VA loan is approved?
No. A Certificate of Eligibility (COE) documents that you meet VA benefit eligibility requirements. A lender separately reviews your finances and the proposed property before making a mortgage decision. Receiving a COE doesn’t guarantee loan approval. Treat it as an important preparation step that establishes your eligibility, not as the lender’s final decision.
What credit score do I need for a VA home loan in Florida?
There isn’t one universal credit-score minimum for every VA lender. VA program guidance and individual lender requirements can differ, and lenders may apply their own credit criteria. They also consider credit alongside your income, debts, assets, and other application details. If you’re concerned about your score, review your full financial picture as you prepare to discuss financing.
Can a VA loan be used to buy a home in Saint Augustine, Florida?
A VA-backed purchase in Saint Augustine may be possible if you’re eligible and the home and transaction meet applicable occupancy, appraisal, and lender requirements. The property’s details matter, so its review is part of the process. As you consider local homes, include applicable property taxes and insurance in your affordability planning, since these costs vary by property and circumstances.