What if qualifying for luxury financing in Florida isn’t about jumping through impossible bureaucratic hoops? If you’re eyeing a property that exceeds the 2026 baseline conforming limit of $832,750, you might feel anxious about strict underwriting or complex tax returns. You aren’t alone; many high-earning buyers share those exact concerns. Making sense of Florida’s jumbo home loan requirements is simply a strategic financial check-up that rewards proactive preparation with the right local support.
You deserve total clarity instead of guesswork. In this guide, you’ll master the specific financial milestones and documentation necessary to secure your dream home, whether you’re purchasing in St. Johns County or along the coast. We’ll walk you through current credit score benchmarks, essential cash reserve rules, and proven ways to streamline your loan approval from day one.
Key Takeaways
- Identify where conventional financing ends and Florida jumbo home loan requirements begin, helping you plan your borrowing strategy with confidence.
- Discover the credit score benchmarks you need to clear the typical 700 floor and capture top-tier interest rates.
- Learn how to balance your debt-to-income ratio below 43% while organizing complex or self-employed income streams.
- Master post-closing cash reserve expectations so you can easily verify 6 to 12 months of payments ahead of underwriting.
Understanding the 2026 Jumbo Loan Landscape in Florida
A jumbo loan is a non-conforming mortgage that exceeds the Federal Housing Finance Agency (FHFA) limits, meaning it cannot be purchased by government-sponsored enterprises like Fannie Mae or Freddie Mac. Because lenders hold these debts directly or package them for private investors, they carry higher financial exposure. This dynamic shapes today’s stricter jumbo home loan requirements, demanding stronger proof of credit health, steady reserves, and consistent cash flow.
In thriving coastal communities like Saint Augustine and Ponte Vedra Beach, property values consistently outpace baseline caps. Understanding established non-conforming loan guidelines helps you prepare early, ensuring your portfolio stands up to manual underwriting scrutiny without unnecessary delays.
Conforming vs. Jumbo Limits in St. Johns County
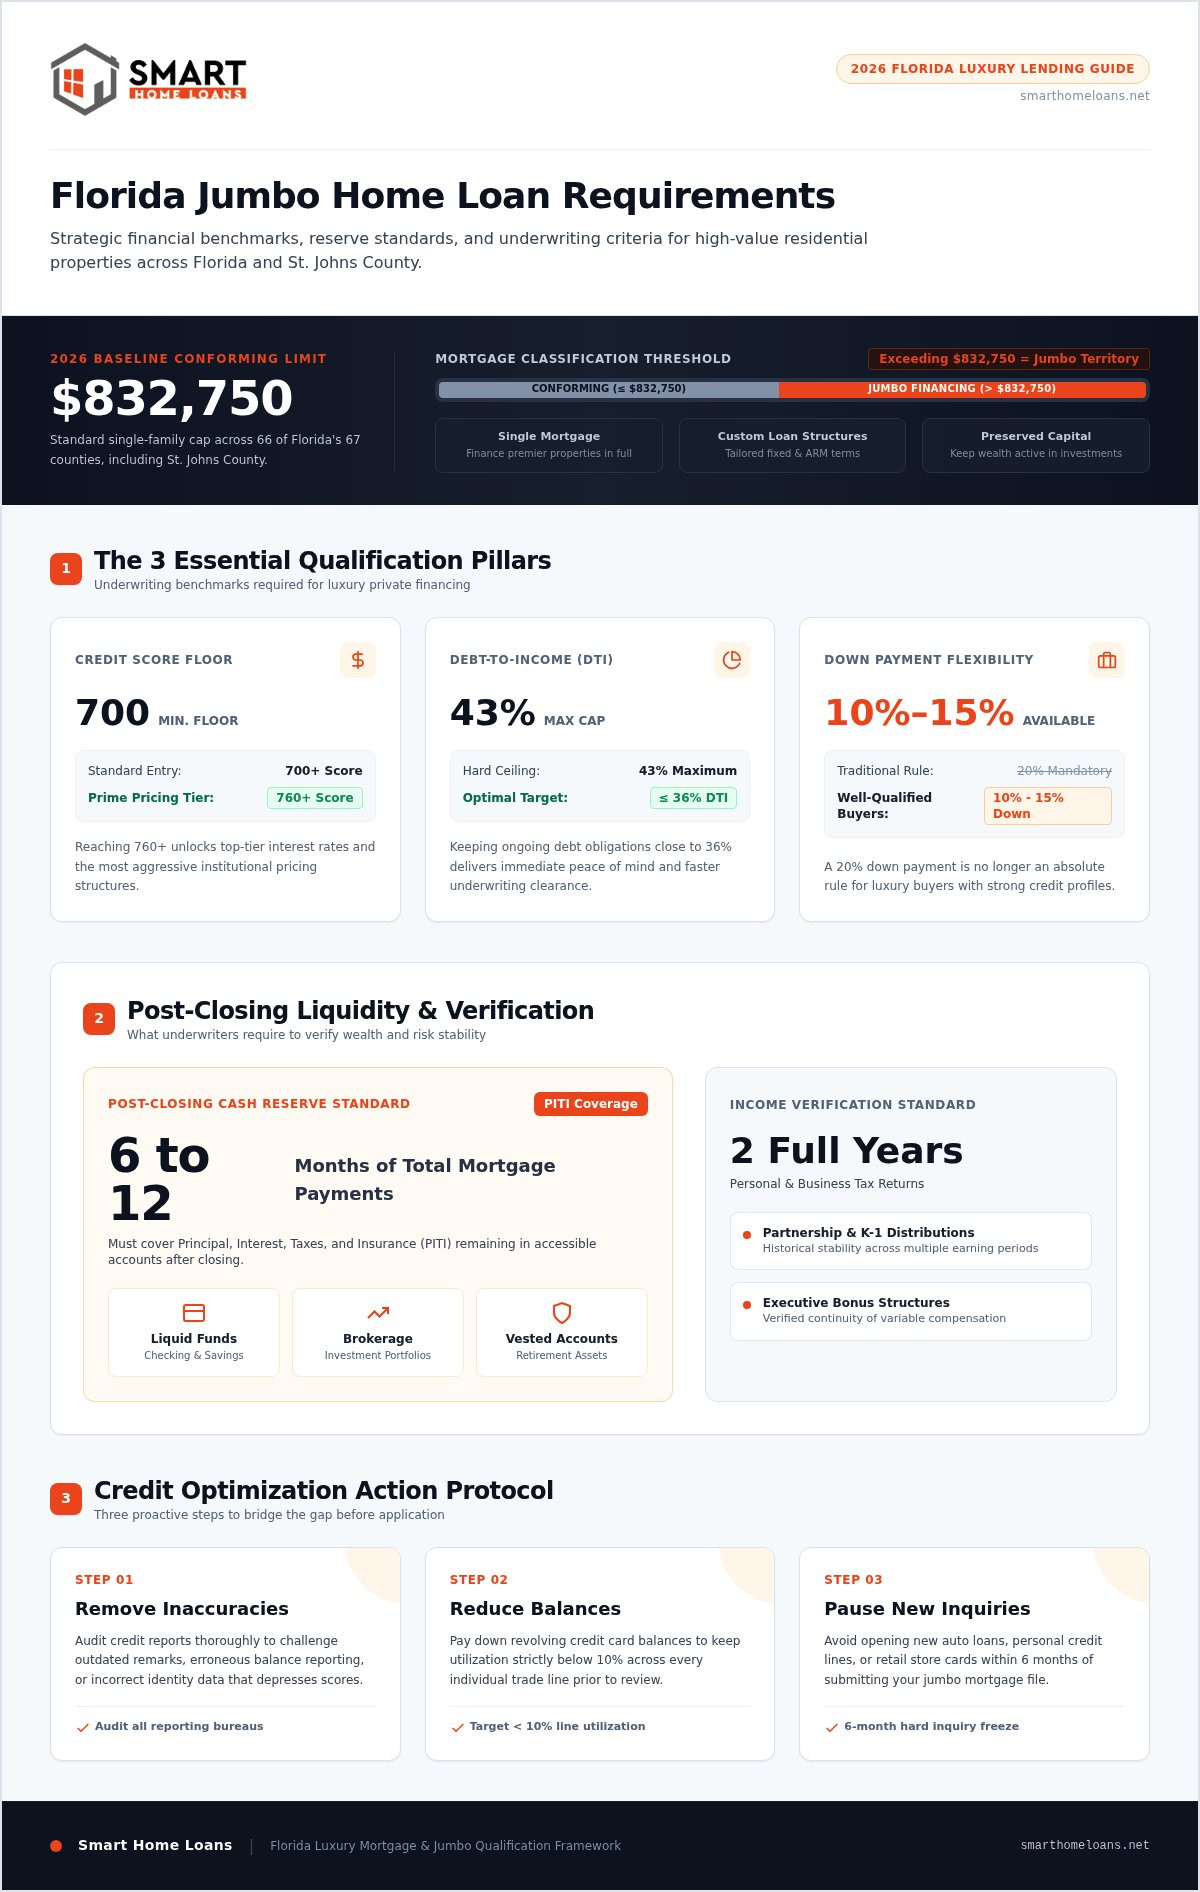
Florida properties cross into jumbo territory once the financed amount tops the baseline ceiling. In St. Johns County, the 2026 baseline limit for a single-family home sits at $832,750. Financing any amount above $832,750 classifies your mortgage as a jumbo product across 66 of Florida’s 67 counties.
Rather than squeezing your purchase budget into rigid conventional caps, exploring jumbo loans in Florida provides substantial purchasing power for high-value homes. You gain several distinct advantages:
- Competitive funding: Finance premier waterfront or golf-course properties with a single mortgage.
- Custom loan structures: Choose tailored fixed-rate or adjustable-rate terms suited to your cash flow.
- Preserved capital: Keep your investment funds growing elsewhere instead of tying up excess cash in a down payment.
Staying ahead of these Florida jumbo home loan requirements transforms a complex transaction into a clear, manageable path toward your next home.
The Essential Jumbo Loan Qualification Checklist
Securing a luxury home means meeting distinct underwriting benchmarks. While traditional mortgages follow rigid guidelines, private lenders set custom thresholds based on total exposure. Reviewing the CFPB guide to jumbo loans confirms that these mortgages demand deeper financial verification, but preparing your file in advance keeps the process simple and transparent.
To satisfy standard jumbo home loan requirements, focus your attention on these three core pillars:
- Credit score floors: Most programs require a minimum 700 score, but reaching 760 or higher unlocks prime interest rates and aggressive pricing tiers.
- Debt-to-income (DTI) caps: Lenders typically enforce a 43% maximum DTI ratio. Keeping your ongoing obligations closer to 36% provides immediate peace of mind during underwriting.
- Down payment flexibility: The mandatory 20% down payment is no longer an absolute rule. Well-qualified buyers can often access 10% to 15% down options depending on loan size.
Maximizing Your Eligibility with Credit Optimization
What happens if your credit score hovers just below the 700 threshold? Even high-net-worth borrowers experience reporting errors that drag down their profiles. A neighborly approach to fixing credit to buy a house bridges this gap before you submit an application.
You can optimize your score quickly by following three simple steps:
- Remove inaccuracies: Audit your credit reports to challenge outdated remarks or erroneous reporting.
- Reduce revolving balances: Pay down credit card utilization below 10% across all individual trade lines.
- Pause new inquiries: Avoid opening auto loans or store cards within six months of financing.
If you need extra guidance preparing your file, our dedicated credit repair services can help refine your standing so you qualify under ideal jumbo home loan requirements. You can easily connect with a local specialist at Smart Home Loans to map out your qualification checklist today.
Financial Documentation and Reserve Requirements
Documenting your wealth should feel validating, not intimidating. Satisfying Florida jumbo home loan requirements requires clear verification of your liquidity and earning stability. Because secondary market investors look closely at risk exposure, as highlighted in the Consumer Financial Protection Bureau guide to jumbo loans, preparation is your greatest asset.
Underwriters focus on three primary verification standards during review:
- Cash reserves: Expect to show 6 to 12 months of mortgage payments (principal, interest, taxes, and insurance) remaining in liquid or semi-liquid accounts after closing. Vested retirement and brokerage funds often count toward this cushion.
- Income verification: High earners with partnership shares, K-1 distributions, or executive bonus structures typically provide two full years of personal and business tax returns, alongside year-to-date profit-and-loss statements.
- Dual appraisals: For unique luxury estates or transactions exceeding $1.5 million, lenders frequently require two independent appraisals to confirm market valuation.
Gathering these files might feel like a full-time job. A dedicated, neighborly mortgage broker handles the heavy lifting, organizing your statements so underwriters receive a clean, organized package.
Proactive Preparation with a Saint Augustine Broker
Local knowledge makes a massive difference along Florida’s Historic Coast. Working with a Saint Augustine specialist helps you account for regional property tax assessments and coastal windstorm insurance requirements early, protecting your qualifying debt ratio from unexpected escrow inflation.
You can streamline the home buying process in Florida by securing a tailored pre-approval upfront. This proactive step validates your financial milestones, confirms specific jumbo home loan requirements, and ensures you make offers from a position of absolute strength.
Take the Next Step Toward Your Florida Luxury Home
Mastering Florida jumbo home loan requirements comes down to early, thoughtful preparation. When you know your target loan limits, maintain strong credit scores, and organize your asset documentation in advance, the entire mortgage approval becomes straightforward. You don’t have to navigate complex balance sheets or strict underwriting standards on your own.
Our team brings deep Saint Augustine expertise, specialized support for complex income structures, and an encouraging, neighborly approach to every transaction (NMLS ID 1734077). We handle the heavy lifting so you can focus on finding the perfect property. Ready to secure your Florida dream home? Get your custom Jumbo Loan checklist from Smart Home Loans today! Your path to luxury coastal living starts with a clear plan and the right partner by your side.
Frequently Asked Questions
What is the minimum credit score for a jumbo loan in Florida in 2026?
Most private lenders require a baseline score of 700 to 720 for approval. While certain portfolio exceptions exist down to 680 with compensating factors like larger equity positions, maintaining a score of 760 or higher earns the best terms. Our local credit repair services can help elevate your profile before applying.
How much down payment is required for a $1.5 million home in Saint Augustine?
Down payment requirements generally range from 10% to 20% depending on program guidelines and asset depth. For a $1.5 million purchase in Saint Augustine, a 10% down payment equals $150,000, while 20% requires $300,000. Higher balances may ask for larger initial equity to balance out overall monthly debt calculations.
Can I get a jumbo loan if I am self-employed?
Yes, self-employed borrowers qualify regularly by providing comprehensive business documentation. Florida jumbo home loan requirements for business owners typically call for two years of filed personal and corporate tax returns, current balance sheets, and profit-and-loss statements verified by your accountant. A knowledgeable local broker organizes these records to ensure smooth manual underwriting.
Are jumbo loan interest rates higher than conventional rates?
Jumbo interest rates are often remarkably competitive and can even mirror or beat conventional pricing. Because lenders set individual guidelines and evaluate well-capitalized borrowers directly, premier credit tiers and healthy liquid reserves often unlock highly favorable terms. Managing your debt structure helps you secure excellent value across Florida’s luxury real estate landscape.