Why does commercial real estate financing Florida business owners rely on often feel like trying to solve a puzzle with half the pieces missing? You aren’t alone if you’ve felt the sting of high interest rates or the cold shoulder from a big bank that treats your company like a spreadsheet entry. It’s frustrating to face complex underwriting requirements without a guide who actually knows the Saint Augustine streets you’re building on. Your business goals deserve more than a generic response from a distant corporate office.
This 2026 guide is here to help you master the local market so you can secure your next property with total confidence. You’ll gain a clear understanding of current loan frameworks and how to find competitive rates through local expertise. We’ll explore specific loan types and show you how a dedicated partner can handle the heavy lifting for you.
Key Takeaways
- Explore the 2026 market landscape in St. Johns County and Saint Augustine to identify high-growth opportunities.
- Learn to distinguish between SBA programs and bridge loans to find the right commercial real estate financing Florida offers for your specific project.
- Simplify the approval process by leveraging a local broker who shops multiple lenders on your behalf.
- Maximize your investment’s ROI by mastering interest rate structures and using cash flow forecasting tools.
Navigating Commercial Real Estate Financing in Florida: 2026 Insights
Commercial real estate financing Florida entrepreneurs rely on is quite different from a standard home loan. At its core, this financing is a business-focused loan secured by a property designed to produce income. Whether you’re eyeing a boutique hotel or a storefront, the property itself acts as the primary collateral. In 2026, the Florida landscape is shifting rapidly. We’re seeing incredible growth in St. Johns County, particularly within the Saint Augustine retail and office sectors.
Local market knowledge is your greatest asset. National banks often miss the nuances of our historic corridors or the specific seasonal traffic patterns that drive revenue. Securing the commercial real estate financing Florida lenders offer requires a deep dive into commercial mortgage underwriting metrics to see what banks see. While residential loans focus on your personal credit, commercial requirements prioritize the property’s ability to pay for itself through rent or operations.
Common Florida Commercial Property Types
Choosing the right asset class is step one. In the current market, these categories stand out for their resilience and potential:
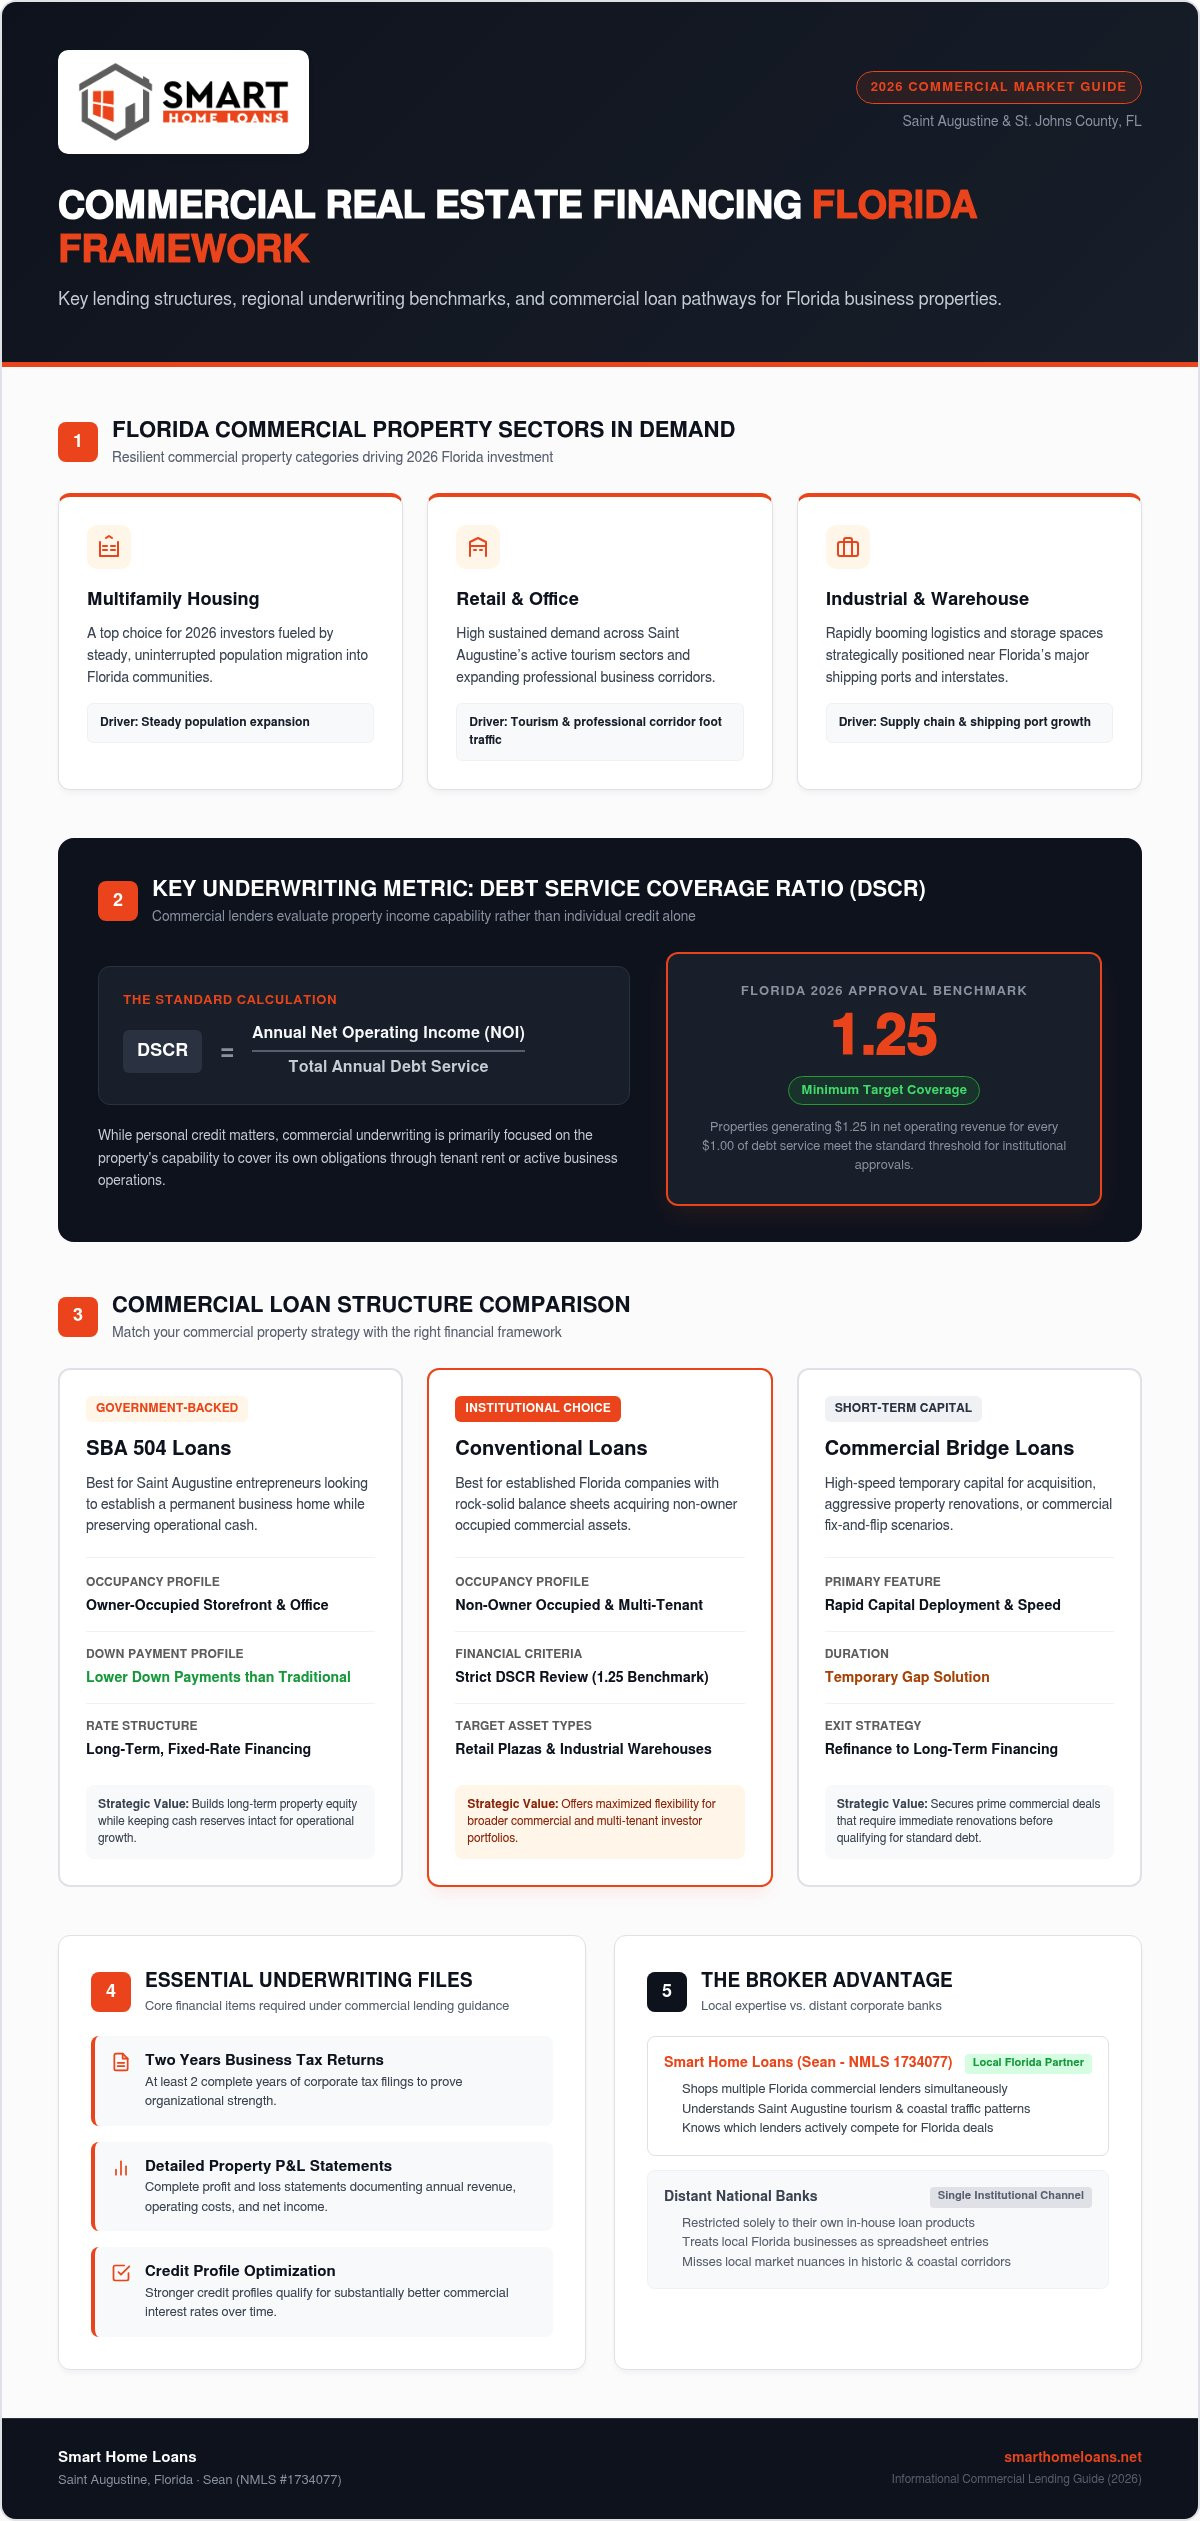
- Multifamily housing: Florida’s steady population growth makes apartments a top choice for 2026 investors.
- Retail and Office: Success here depends on navigating the Saint Augustine tourism and professional corridors where demand remains high.
- Industrial and Warehouse: Logistics spaces near Florida’s major ports and highways are booming as local supply chains expand.
Choosing the Right Commercial Property Loan: Florida Financing Options
Finding the right loan for your business shouldn’t feel like a guessing game. The commercial real estate financing Florida provides comes in several flavors; each designed for different stages of business growth. If you’re looking for a permanent home for your company, the SBA 504 loan program is a fantastic tool. It offers long-term, fixed-rate financing with lower down payments than traditional options. This is ideal for Saint Augustine entrepreneurs who want to preserve cash for operations while building equity in their own storefront or office.
Commercial Mortgage Comparison: Conventional vs. SBA
Conventional loans are best for established Florida businesses with rock-solid balance sheets. They often provide more flexibility for properties that aren’t owner-occupied, like a multi-tenant retail plaza or an industrial warehouse. However, lenders will look closely at your Debt Service Coverage Ratio (DSCR). The DSCR is a calculation of your property’s annual net operating income divided by its total annual debt service; a typical 2026 Florida benchmark for approval is a DSCR of 1.25.
What if you need speed? Bridge loans provide quick capital for renovations or “fix-and-flip” commercial projects. They act as a temporary solution until you secure long-term financing. Securing the best commercial real estate financing Florida offers often depends on your credit profile, so using professional credit repair services can help you qualify for much better commercial rates over time. It’s all about positioning your business for the best possible deal. If you’re ready to explore your options, you can speak with a local advisor who knows how to navigate these complex requirements for you.
Securing Your Florida Commercial Mortgage: The Path to Approval
Securing the commercial real estate financing Florida businesses need is mostly about preparation and partnership. Lenders want a clear picture of your business’s financial health before they commit capital. You’ll need to gather at least two years of business tax returns and detailed property Profit and Loss (P&L) statements. This documentation helps banks follow federal commercial real estate lending guidance to ensure the property is a sound investment. Having these files ready from day one speeds up the process significantly.
Working with a local broker gives you a massive “Broker Advantage.” While big banks only offer their own limited products, Smart Home Loans shops multiple Florida lenders to find your perfect fit. You aren’t just a number in a queue. Working with Sean (NMLS 1734077) means having a Saint Augustine neighbor in your corner who understands our specific coastal market. This local expertise beats a distant national call center every time. We know the streets, the local regulations, and the lenders who are actually hungry for Florida deals.
The 5-Step Commercial Approval Process
We’ve streamlined the path to closing so you can focus on running your business. Here is how we move from your first call to the closing table:
- Step 1: Initial consultation to align your business goals with the right financing path.
- Step 2: Comprehensive credit and financial review, including integrated credit repair if your score needs a boost.
- Step 3: Property appraisal and environmental reports specific to Florida coastal regulations.
The final steps involve formal underwriting and coordinating with title companies for a smooth finish. Ready to take the next step? Review our commercial mortgage loan guide or contact our Saint Augustine office today to start your application.
Maximizing Your ROI with Commercial Financing
How do you turn a property into a true wealth-builder? It starts with your rate structure. Fixed rates provide predictable costs, while variable rates may offer initial savings with more risk. In our current 2026 market, many Saint Augustine entrepreneurs choose fixed rates to protect against future fluctuations. Owning your professional space is almost always better than renting. It transforms a monthly expense into a long-term asset that builds equity for your future.
Smart planning requires accurate data. Use a commercial mortgage calculator to forecast your monthly cash flow before you sign. This helps you understand exactly how the commercial real estate financing Florida lenders offer fits into your budget. Watch out for prepayment penalties. These fees can sting if you decide to sell or refinance early. We help you negotiate these terms to ensure you maintain the flexibility your business needs to pivot. Don’t let restrictive fine print stall your growth.
Long-term Planning and Refinancing
Your property is more than just a place to work; it’s a financial engine. Once you’ve built significant equity, consider a cash-out refinance. This move allows you to pull capital from your property to fund a second location or upgrade your current equipment. Using your commercial equity for additional acquisitions is a proven way to scale. Our team stays by your side long after the first closing to help you spot these opportunities. We want to see your Saint Augustine business thrive for decades.
Build Your Future in Florida Today
You now have the roadmap to secure your business’s permanent home. Remember that success in the 2026 market depends on choosing the right loan structure and leveraging local insights. Whether you’re targeting a retail space in Saint Augustine or an industrial warehouse, the right support makes all the difference. We provide brokerage access to multiple Florida lenders and specialized credit repair services to ensure you get the best deal possible.
We handle the heavy lifting while you focus on your business vision. Don’t let complex requirements stall your progress. Ready to unlock the commercial real estate financing Florida offers? Get Started on Your Florida Commercial Financing Journey Today and secure the competitive rates your business deserves. Your goals are within reach; let’s build something great together.
Frequently Asked Questions
How much down payment is required for commercial real estate in Florida?
Most conventional lenders require a down payment between 20% and 25% of the property’s purchase price. If you qualify for an SBA 504 loan, you might secure your property with as little as 10% down. This lower requirement helps Saint Augustine business owners keep more cash available for daily operations. Every lender has different standards; your specific property type will influence the final amount.
What is the current interest rate for a Florida commercial mortgage in 2026?
Interest rates for the commercial real estate financing Florida offers vary significantly based on your property type and credit profile. In 2026, rates are influenced by broader economic shifts and your specific Debt Service Coverage Ratio. We recommend a personalized consultation to get an accurate quote for your project. Fixed and variable options are available to match your long-term business goals and risk tolerance.
Can I get a commercial property loan with a lower credit score?
Yes, you can still find financing even if your credit score isn’t perfect. We offer specialized credit repair services to help improve your standing before you apply for a long-term mortgage. Some bridge loan programs also focus more on the property’s value than your personal credit history. Our goal is to find a creative solution that bridges the gap between your current situation and your business aspirations.
How long does the commercial financing process take in Saint Augustine?
A typical commercial mortgage in Saint Augustine takes anywhere from 45 to 90 days to close. This timeline depends on the complexity of the property appraisal and environmental reports required for our coastal areas. We work proactively to streamline the document gathering phase to avoid unnecessary delays. Having your tax returns and profit statements ready from the start helps us move your application through underwriting much faster.