Rigid retail bank algorithms were never built to handle coastal luxury real estate. If you’ve spent weeks gathering tax returns only to watch an underwriter stall over complex corporate income or coastal property features, you know how frustrating the process can be. Securing a jumbo loan Ponte Vedra Beach buyers need shouldn’t feel like an uphill battle against red tape.
You deserve a financing strategy that works with your financial profile, not against it. Discover how to secure competitive jumbo financing for Ponte Vedra Beach luxury homes through tailored wholesale mortgage solutions that bypass big-bank delays. Below, we break down current St. Johns County thresholds, key asset qualification rules, and the exact steps to land a smooth pre-approval for your next purchase.
Key Takeaways
- Learn how St. Johns County baseline limits impact coastal luxury purchases and when you must step into non-conforming financing.
- Discover the specific credit, down payment, and post-closing reserve benchmarks needed to secure a jumbo loan Ponte Vedra Beach lenders will approve.
- Explore how tailored asset-depletion and alternative documentation options help business owners qualify without standard tax return limitations.
- See why working with an independent wholesale mortgage broker provides greater flexibility and smoother closings than traditional retail banks.
Understanding Jumbo Loan Limits in Ponte Vedra Beach
Ponte Vedra Beach real estate sits in a distinct financial tier. While conventional loans adhere strictly to standard government-backed caps, luxury coastal properties quickly surpass these rules. A jumbo loan is a non-conforming residential mortgage that finances transaction amounts higher than the baseline limits set by the Federal Housing Finance Agency (FHFA). For a deeper look at these secondary market mechanics, review this jumbo mortgage loan overview detailing how non-conforming debt operates outside standard government guarantees.
Because Fannie Mae and Freddie Mac do not purchase these larger mortgages, wholesale investors establish independent underwriting guidelines. This structural difference makes specialized regional insight essential for St. Johns County luxury purchases.
Conforming Thresholds and the St. Johns County Luxury Market
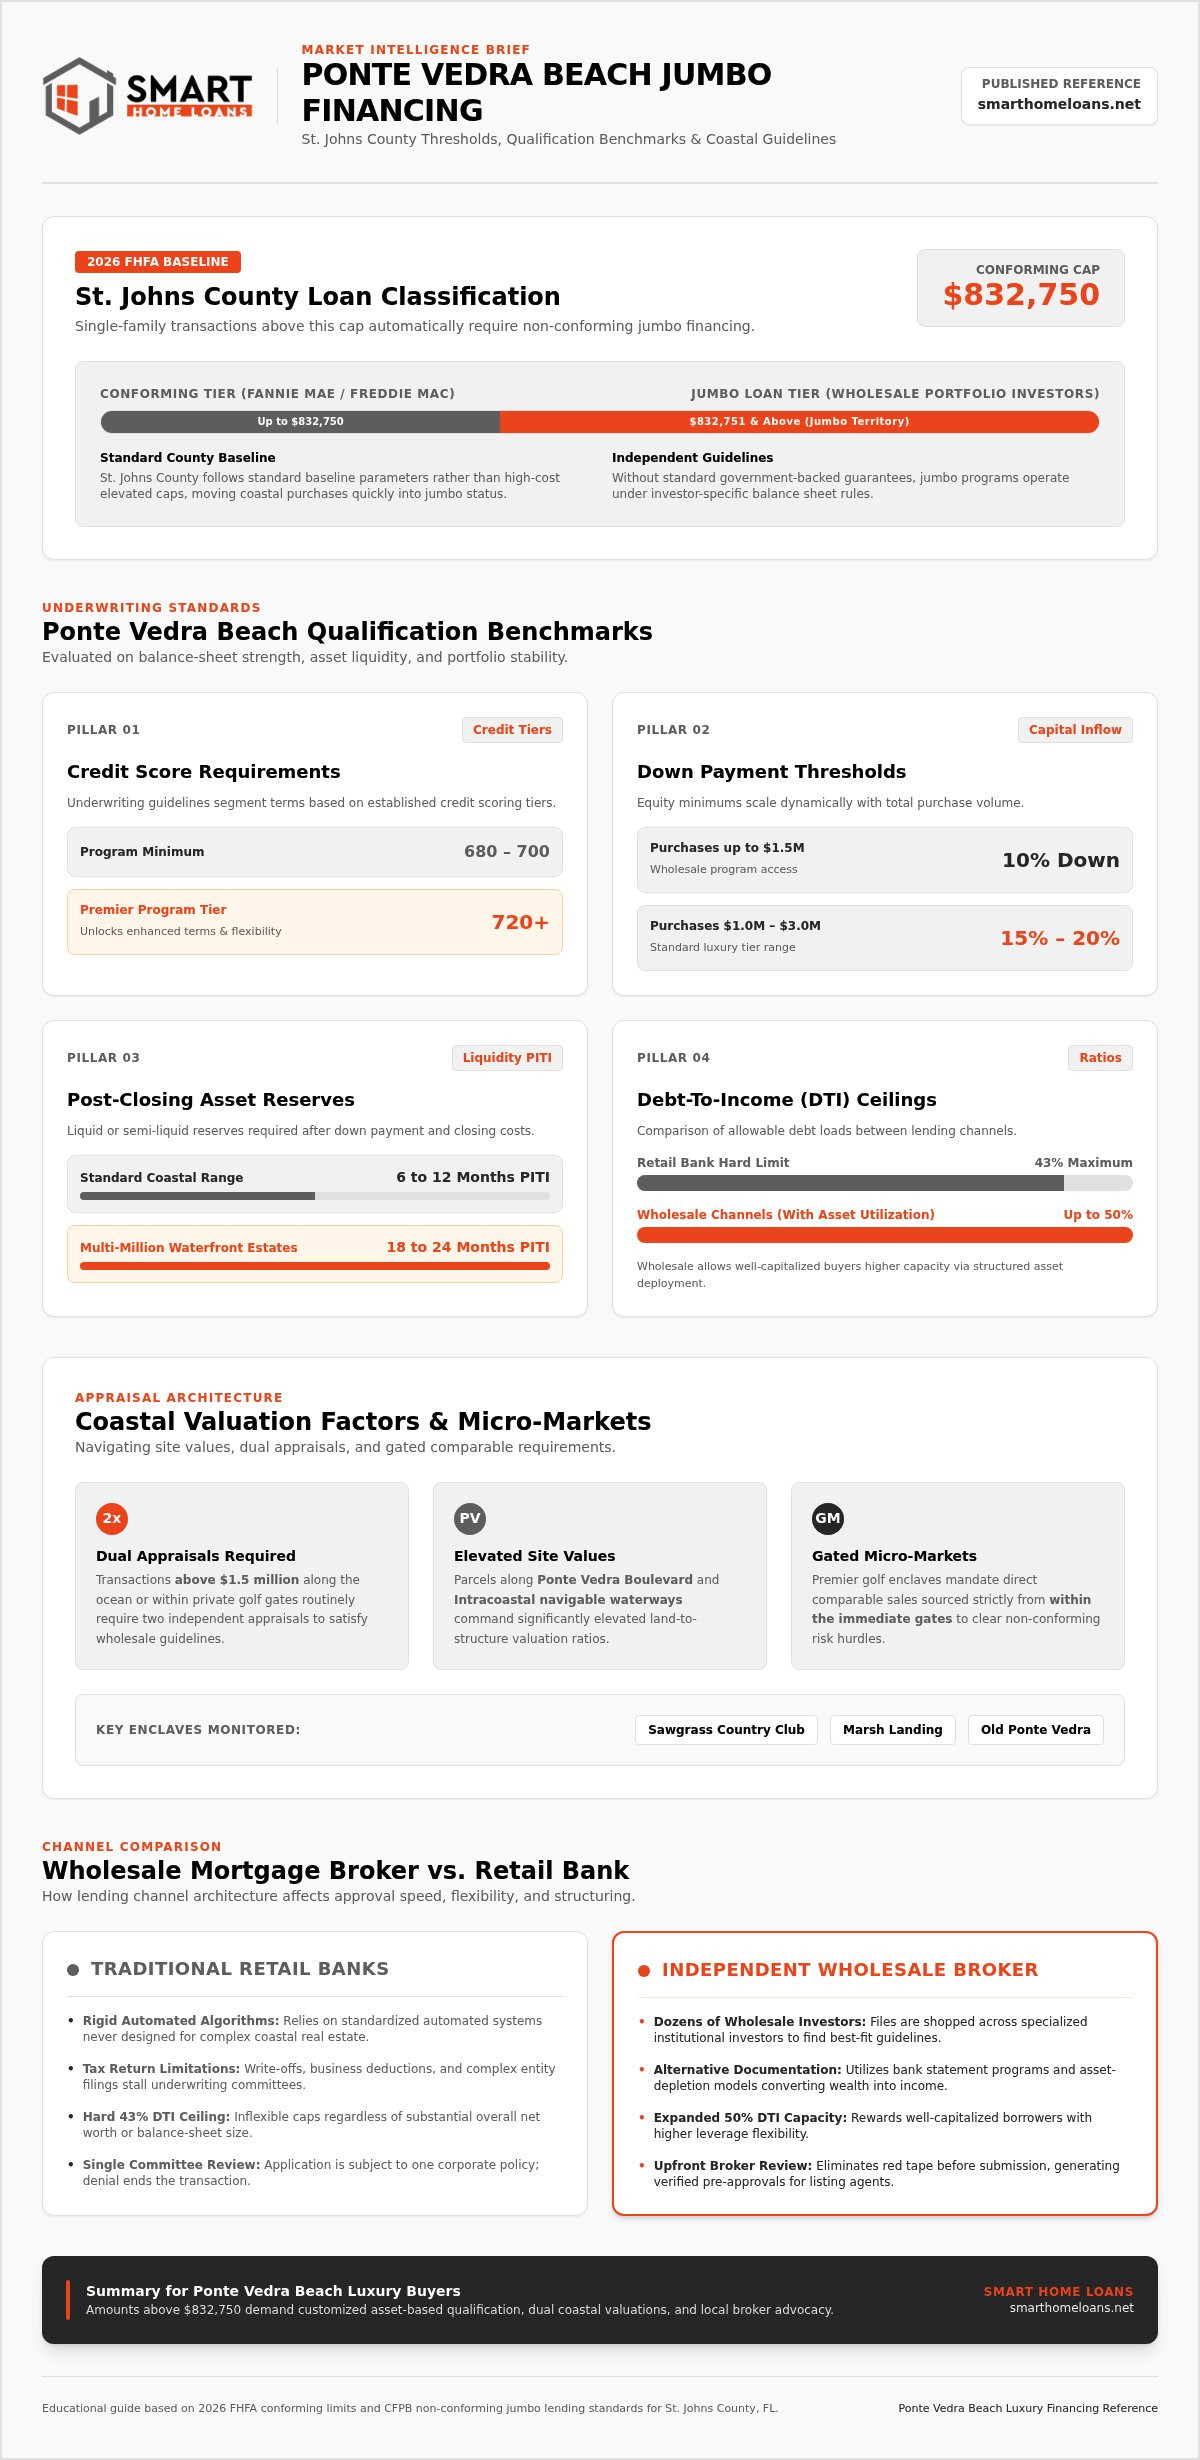
In 2026, the FHFA established the single-family conforming baseline limit at $832,750. St. Johns County falls under this standard baseline rather than an elevated high-cost designation. Consequently, any single-family financing exceeding $832,750 officially requires a jumbo loan Ponte Vedra Beach buyers rely on to secure high-end properties.
Prestigious coastal enclaves like Sawgrass Country Club, Marsh Landing, and Old Ponte Vedra routinely trade well past seven figures. Securing properties across these premier communities involves distinct localized factors:
- Unique Site Values: Oceanfront parcels along Ponte Vedra Boulevard and Intracoastal navigable waterways command elevated land-to-structure appraisal ratios.
- Gated Micro-Markets: Exclusive golf communities require direct comparable sales from within the immediate gates to satisfy non-conforming valuation standards.
Recognizing how local boundaries interact with federal loan caps gives you a distinct edge when negotiating purchase contracts.
Qualification Guidelines for Ponte Vedra Beach Jumbo Financing
Securing a jumbo loan Ponte Vedra Beach lenders approve demands a clear grasp of elevated underwriting tiers. Because these mortgages exceed official FHFA conforming loan limit values, risk models focus heavily on balance-sheet strength rather than basic payroll stubs alone.
Approval benchmarks typically center on three core pillars:
- Credit Profiles: Most programs require a minimum 680 to 700 score, while premier tiers reward scores of 720 or higher with enhanced terms.
- Down Payments: Wholesale programs often permit 10% down up to $1.5 million, though purchases between $1 million and $3 million commonly target 15% to 20% down.
- Dual Coastal Appraisals: For transactions above $1.5 million along the ocean or within private golf gates, lenders frequently require two independent appraisals to confirm property values.
Underwriting Criteria and Reserve Expectations for Coastal Homes
Post-closing liquidity remains paramount. Lenders generally require 6 to 12 months of principal, interest, taxes, and insurance (PITI) held in liquid or semi-liquid accounts. For multi-million-dollar waterfront estates, reserve cushions can scale toward 18 to 24 months.
While traditional banks enforce a strict 43% debt-to-income ceiling, wholesale channels offer flexibility up to 50% for well-capitalized borrowers using asset utilization. Review our detailed guide on jumbo home loan requirements to see how your portfolio aligns. If you’re ready to structure a competitive offer, connect with Smart Home Loans to explore tailored financing solutions built for your situation.
Why Choose a Local Wholesale Broker for Your Ponte Vedra Jumbo Loan
Big retail banks rely on rigid, automated underwriting models. If you have significant business write-offs, multi-entity tax filings, or dynamic bonus compensation, an algorithm can easily derail your file. Independent wholesale brokers work differently. Instead of answering to a single corporate credit committee, brokers shop your file across dozens of specialized wholesale investors to find programs that reward strong liquidity over tax return write-downs.
According to this regulatory CFPB guide on jumbo mortgages, lenders retain wide discretion when designing qualification standards for non-conforming debt. That latitude is where tailored mortgage structuring shines:
- Flexible Documentation: Qualified borrowers can utilize bank statement programs or asset-depletion models that count existing investment wealth as monthly qualifying income.
- Competitive Advantage: Comprehensive upfront broker reviews produce rock-solid pre-approvals, giving listing agents and luxury sellers full confidence in your offer.
The Wholesale Advantage for Luxury St. Johns County Buyers
Navigating high-end purchases along the coast demands local accountability. Sean (NMLS ID 1734077) and the Saint Augustine-based team at Smart Home Loans actively match St. Johns County buyers with wholesale partners that fit their exact financial picture. Whether you need single-appraisal exceptions or custom down payment structures, a dedicated local broker acts as your advocate every step of the way.
Explore our comprehensive guide to jumbo loans in Florida to discover modern non-conforming solutions designed around your wealth.
Secure Your Next Chapter in Ponte Vedra Beach
Purchasing a premier coastal property doesn’t have to mean fighting rigid bank algorithms. Understanding local conforming thresholds, preparing proper post-closing reserves, and structuring your assets strategically ensures a smooth transaction. When you pair that preparation with wholesale market access, securing the ideal jumbo loan Ponte Vedra Beach properties require becomes straightforward.
At Smart Home Loans, Sean (NMLS ID 1734077) pairs deep St. Johns County regional expertise with direct access to top wholesale lenders across Florida. You get personalized loan structuring designed around your unique balance sheet, without the bureaucratic delays. Ready to submit a winning offer? Connect with Smart Home Loans to explore your Ponte Vedra Beach luxury financing options today.
Frequently Asked Questions
What is considered a jumbo loan in Ponte Vedra Beach for 2026?
In 2026, any single-family mortgage exceeding the baseline conforming limit of $832,750 is classified as a jumbo loan in St. Johns County. Ponte Vedra Beach follows standard federal baseline limits rather than elevated high-cost caps. If your financing amount surpasses this threshold, you’ll need specialized non-conforming underwriting to complete your luxury purchase.
How much down payment is required for a Ponte Vedra Beach jumbo loan?
Most lenders expect down payments between 10% and 20% for a jumbo loan Ponte Vedra Beach buyers apply for. Select wholesale programs accommodate 10% down for transaction amounts up to $1.5 million. For multi-million-dollar coastal or golf properties exceeding $2 million, down payment benchmarks typically settle between 15% and 25% depending on your credit profile.
How many months of cash reserves do lenders require for a jumbo mortgage?
Lenders typically require 6 to 12 months of principal, interest, taxes, and insurance (PITI) held in verified post-closing reserves. For multi-million-dollar oceanfront properties, reserve requirements can expand toward 18 to 24 months. These funds can usually remain in retirement accounts, brokerage portfolios, or liquid business reserves without needing complete liquidation.
Can self-employed buyers qualify for a jumbo loan in St. Johns County?
Yes, self-employed entrepreneurs and business owners qualify easily through tailored wholesale mortgage programs. Instead of relying solely on net taxable income shown on tax returns, local brokers can utilize 12-to-24 month bank statement options or asset-depletion models. Based in Saint Augustine, Smart Home Loans helps luxury buyers across St. Johns County structure files to reflect their true purchasing strength.