Could a credit score below 620 still leave the door open to an FHA home in St. Augustine? In many cases, yes: FHA’s baseline allows scores as low as 500, though the down payment and lender’s own standards matter. If you’re searching “minimum credit score for FHA loan St. Augustine,” it’s understandable to feel confused when an online score and a mortgage credit review don’t match.
This guide explains FHA’s score thresholds, how they relate to down payment requirements, and why lender overlays can change the practical cutoff. You’ll also learn what lenders review beyond your score, including income, debts, and your overall credit profile. A past setback doesn’t automatically end your homebuying plans. Start by organizing your financial details, then discuss your options with a local mortgage professional to identify practical next steps.
Key Takeaways
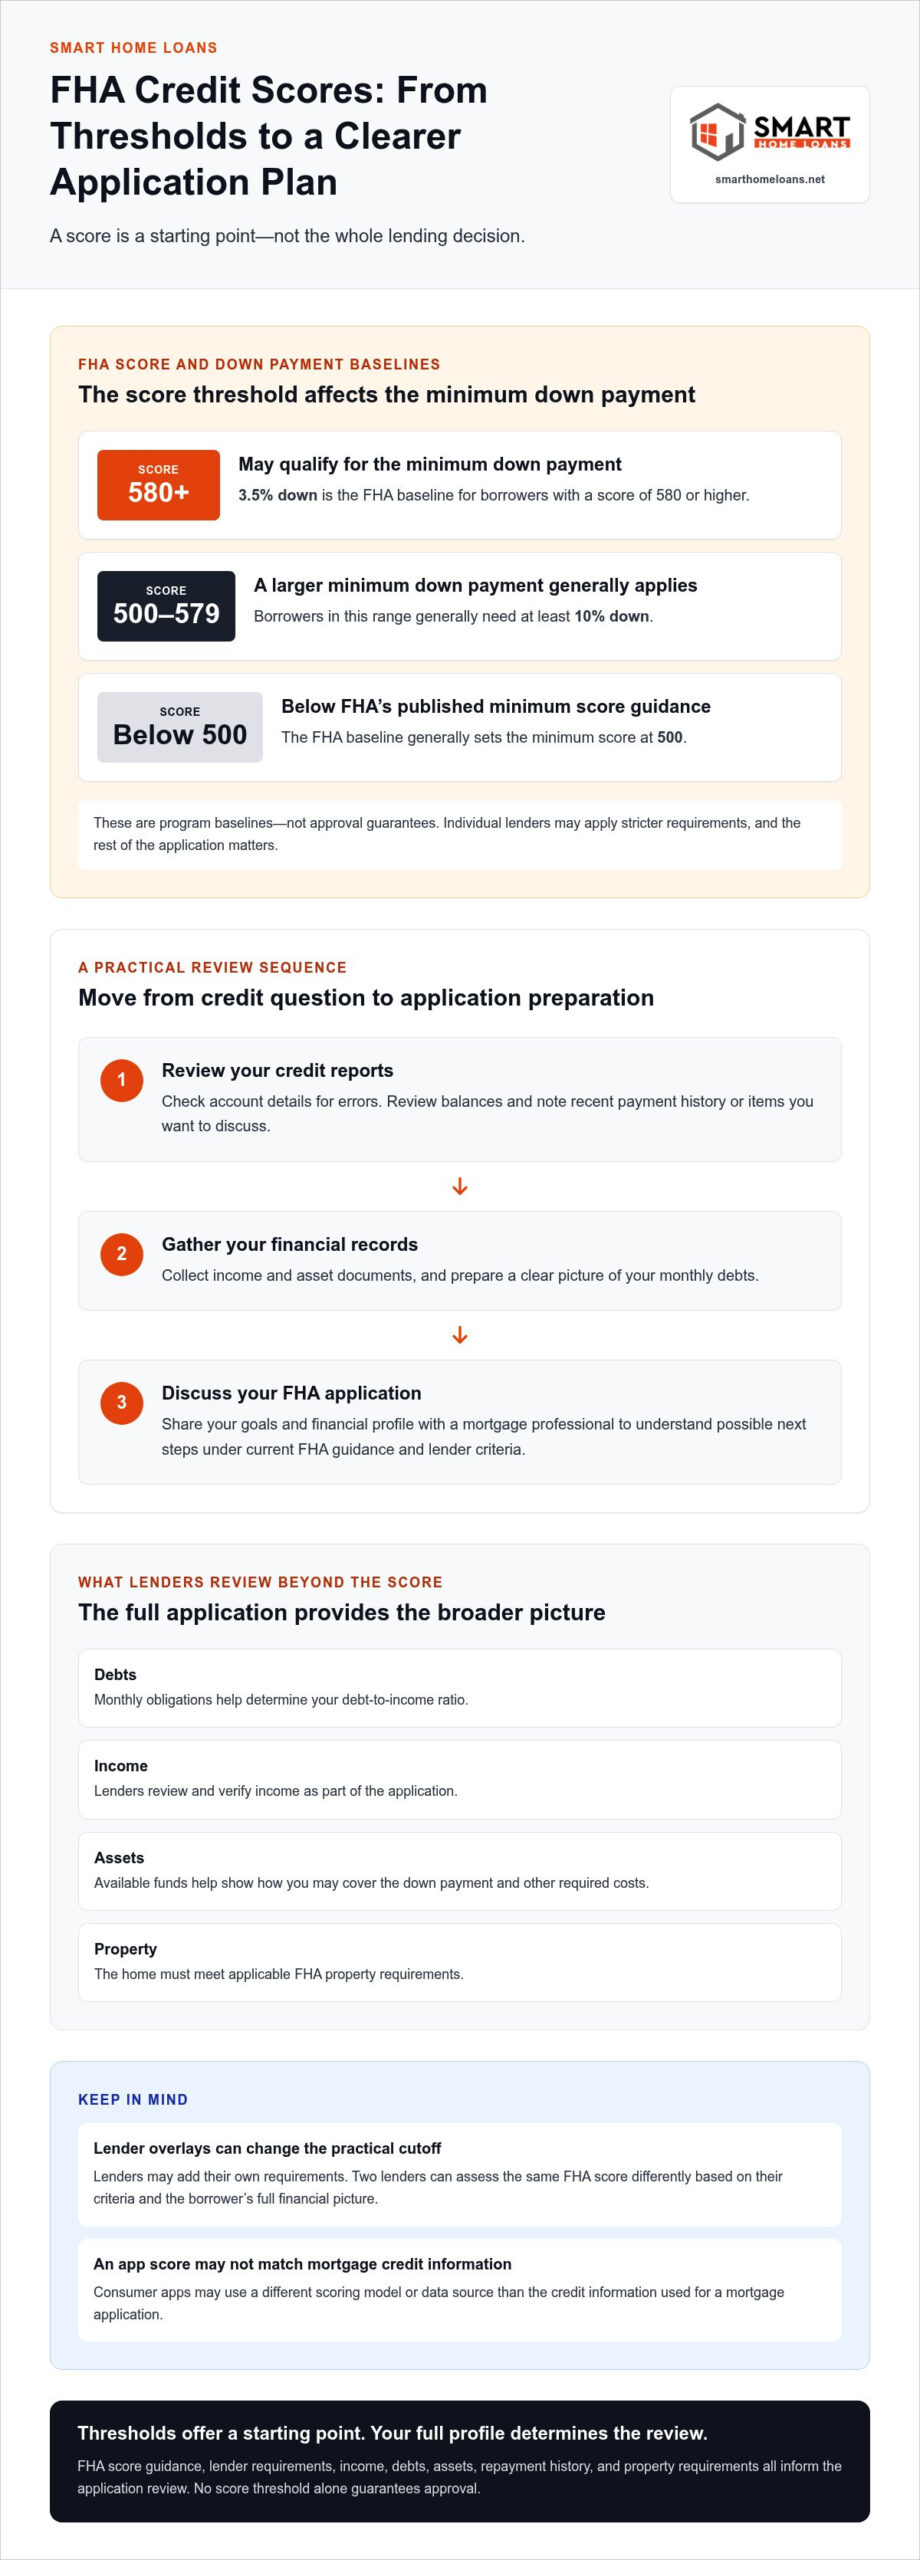
- The minimum credit score for FHA loan St. Augustine buyers may need depends on the down payment: FHA’s baseline is 580 for the minimum down payment, while scores from 500 to 579 generally require at least 10% down.
- FHA score thresholds are program baselines, not approval guarantees. Individual lenders may apply stricter requirements.
- A consumer app score may differ from the credit information used in mortgage underwriting, so review your credit profile in the context of an FHA application.
- Prepare by reviewing your credit reports and gathering income and asset documents, then discuss FHA guidance and potential credit repair or down payment assistance support with a mortgage professional.
What is the minimum credit score for an FHA loan in St. Augustine?
HUD’s FHA guidance generally sets the minimum score at 500. Borrowers with a score of 580 or higher may qualify for the minimum 3.5% down payment; those with scores from 500 to 579 generally need at least 10% down. These are program baselines, not a promise of approval or a guarantee that every lender will accept the same score. Review current HUD guidance as you prepare to apply.
The FHA doesn’t lend money directly. It insures eligible loans made by lenders, which can support more flexible qualification standards. For broader background on the program’s purpose and requirements, see this overview of the FHA insured loan. Your credit score is only one part of the decision. Lenders assess the full application, including your income, debts, assets, and repayment history, and may set requirements that are stricter than FHA’s baseline.
How do FHA score thresholds relate to the down payment?
The score threshold affects how much you may need to contribute upfront. For example, a buyer with a score of 585 may meet the baseline for 3.5% down, while a buyer with a score of 550 generally faces a 10% minimum. A score below 500 generally falls short of FHA’s published minimum score guidance. These thresholds don’t account for every lender’s criteria or the rest of your finances.
If your score is below the preferred range, don’t assume homeownership is out of reach. A mortgage professional can review your credit profile and discuss potential next steps. You can also explore FHA loans with bad credit in Florida to understand possible considerations before applying. For buyers in St. Augustine, the minimum credit score for FHA loan St. Augustine is a useful starting point, but the lender’s review determines how your full application fits.
Why can two St. Augustine lenders assess the same FHA credit score differently?
FHA sets program guidelines, but lenders may add their own requirements, called lender overlays. One lender may accept an application that another declines or reviews differently, even when both consider FHA financing. Their internal criteria and assessment of the borrower’s full financial picture can vary. That’s why the minimum credit score for FHA loan St. Augustine buyers see advertised may not match every lender’s practical cutoff.
Your score in a consumer app may differ from the credit information used for a mortgage application. Apps may show a score based on a different scoring model or data source, while mortgage underwriting relies on credit information obtained for that application. Don’t assume the app’s number is the one a lender will use. A mortgage professional can help interpret your credit profile in context.
What should St. Augustine buyers review besides their credit score?
Look beyond the number before applying. Check your credit reports for errors, review account balances, and note recent payment history. Then organize the information lenders use to assess whether the proposed payment fits your finances:
- Debts: Monthly obligations help determine your debt-to-income ratio.
- Income: Lenders review and verify income as part of the application.
- Assets: Available funds help show how you’ll cover the down payment and other required costs.
- Property: The home must meet applicable FHA property requirements.
These factors work together. For example, manageable monthly debts and documented income provide a fuller picture than a score alone, though they don’t guarantee approval. Use Smart Home Loans’ FHA mortgage guidance to understand how your credit, finances, and potential property fit the review. Before applying, list the documents you have and questions you want to discuss.
What are the next steps toward an FHA loan in St. Augustine?
Turn your credit-score question into a practical plan. A few organized steps can help you and a mortgage professional see what may need attention before you apply. Whether you’re buying in St. Augustine or elsewhere in St. Johns County, your application will be reviewed against current FHA guidance and the lender’s criteria.
- Review your credit reports. Check account details for errors and note balances or recent payments you may want to discuss.
- Gather your financial records. Collect income and asset documents, along with a clear picture of your monthly debts.
- Discuss your FHA application. Share your goals and financial profile with a mortgage professional to understand possible next steps.
Preparation helps make the conversation more useful. If the minimum credit score for FHA loan St. Augustine guidance leaves you unsure where you stand, a professional can consider your broader profile rather than focusing on one number alone.
How can a local mortgage review clarify your FHA options?
A local review can put your credit information, income, debts, available funds, and homebuying plans into context. Smart Home Loans provides FHA mortgage guidance and offers credit repair and down payment assistance. Eligibility for a loan or assistance depends on the applicable review, so no outcome is guaranteed. If a past credit setback is weighing on you, discuss what may need attention now and what preparation could help before applying. A tailored conversation can turn uncertainty into manageable next steps.
Organize your documents and questions, then explore FHA mortgage guidance from Smart Home Loans to discuss your situation and preparation options.
Move forward with a plan that fits your goals
Your next step doesn’t have to be a major commitment. Start by deciding what you want your homebuying timeline to look like and which questions would help you feel prepared. A focused conversation can help turn uncertainty about the minimum credit score for FHA loan St. Augustine into a clearer plan.
Smart Home Loans specializes in FHA home loans and can discuss your application goals. The brokerage also offers credit repair and down payment assistance, with eligibility depending on the applicable review.
Explore FHA loan guidance with Smart Home Loans and discuss a practical next step for your homebuying plans.
Frequently Asked Questions
What is the minimum credit score for an FHA loan in Florida?
FHA’s published baseline generally starts at 500. A score of 580 or higher may qualify for the minimum 3.5% down payment, while scores from 500 to 579 generally require at least 10% down. These FHA guidelines apply in Florida, including St. Augustine, but they don’t guarantee approval. Smart Home Loans can help you understand how current guidance applies to your application.
Can I get an FHA loan in St. Augustine with a 500 credit score?
Possibly, since 500 is FHA’s general minimum score baseline, but that score alone doesn’t ensure a lender will approve your application. At this score range, the baseline down payment is at least 10%, and the lender will assess the rest of your application. A useful next step is to discuss your credit profile and available funds with Smart Home Loans.
Does FHA require a 580 credit score for a 3.5% down payment?
Generally, yes. FHA guidance uses a score of 580 or higher for the minimum 3.5% down payment. That threshold describes the program’s baseline, not an automatic approval or a requirement that every lender use the same cutoff. If your score is near 580, review your mortgage credit information with Smart Home Loans before making plans around a particular down payment.
Can an FHA lender require a higher credit score than HUD?
Yes. A lender can set stricter credit criteria than FHA’s published guidance, so its minimum may be higher. These added requirements are often called lender overlays. Smart Home Loans can explain how lender standards apply to your FHA application and discuss practical preparation steps for your situation.