If you’re looking for a home loan with low credit score Florida lenders may consider more than your score. Income, monthly debts, available funds, payment history, and the loan program all help shape the full application. It’s understandable to worry that one number could shut the door, but different loan programs and lender requirements can lead to different outcomes.
This guide compares FHA, VA, and USDA paths, explains what lenders may review, and shows where Florida down payment assistance could fit. You’ll also find practical ways to prepare your application, including credit steps that can strengthen your overall profile without promising a particular score or approval. Whether you’re buying near Saint Augustine or elsewhere in Florida, you can use these steps to organize your finances and identify a useful next move.
Key Takeaways
- A low score doesn’t show the whole financial picture. Lenders may also review income, debts, payment history, and available funds when you seek a home loan with low credit score Florida.
- FHA, VA, and USDA loans have different eligibility rules. The right option depends on your circumstances and, for USDA, the property’s location.
- Florida down payment assistance may be worth exploring, but eligibility and repayment terms matter.
- Review your credit reports, organize income and debt records, and compare programs before taking on new debt.
Can You Get a Home Loan with a Low Credit Score in Florida?
Yes, it may be possible. A credit score summarizes information in your credit history, such as how you’ve managed borrowed money and made payments. It can help lenders assess credit risk, but it isn’t the same as a complete mortgage decision.
For a home loan with low credit score Florida buyers may need to consider more than the score. Lenders can review income, debts, available funds, payment history, and details about the property and loan program. FHA financing is one option some buyers explore. This general FHA loan overview explains how the program works. Eligibility and lender requirements still apply.
What lenders may consider beyond your credit score
Your debt-to-income ratio, or DTI, compares monthly debt payments with gross monthly income, which is income before taxes and other deductions. It helps show how much of your income is already committed. Lenders may also consider whether your income is stable and can be documented, along with funds available for the purchase and closing costs.
Payment patterns add context. Recent on-time payments may help show how you’re managing credit now, while missed payments or other credit events may prompt a closer review. Property details matter too, because each loan program has its own eligibility rules. Smart Home Loans can help assess how these factors fit together and compare relevant mortgage options, rather than treating one score as the whole story.
Which Florida Home Loan Options May Fit a Lower Credit Score?
Start with each program’s purpose and eligibility, not just its score guidance. FHA loans may suit buyers exploring flexible down-payment options. The Federal Housing Administration (FHA) insures these loans. VA loans are for eligible service members, veterans, and certain surviving spouses. USDA loans serve eligible buyers and properties under program rules. Each program has separate requirements, so Smart Home Loans can help compare the options for a home loan with low credit score Florida buyers are considering.
How to compare programs without relying on one credit-score number
Use this overview to understand the main differences, then review current requirements through official program resources. Score guidance can change, and lender standards may be stricter than program guidance.
| Program | Purpose and borrower context | Location rules | Where to verify |
|---|---|---|---|
| FHA | Insured mortgage option; down-payment guidance may depend on credit score. | No rural-area rule. | HUD program information and Smart Home Loans; review current score and down-payment requirements. |
| VA | For borrowers who meet VA service-related eligibility. | No rural-area rule. | VA program information and Smart Home Loans; review eligibility and applicable score standards. |
| USDA | For eligible buyers meeting program income and other criteria. | Property must qualify. Check the exact address, including near Saint Augustine, with the official USDA eligibility tool. | USDA program information and Smart Home Loans; review property, income, and credit requirements. |
| Florida Housing assistance | May pair with an eligible first mortgage; assistance is not automatically a grant. | Florida program rules apply. | Florida Housing program information and Smart Home Loans; review eligibility, funding, and repayment terms. |
For a practical comparison, weigh eligibility, property location, available funds, and repayment obligations together. Florida Housing assistance is a separate qualification question, not a substitute for mortgage approval. Review current score thresholds and assistance terms before relying on them. Explore mortgage options to compare FHA, VA, USDA, and assistance pathways based on your circumstances.
How to Prepare for a Florida Home Loan with Low Credit
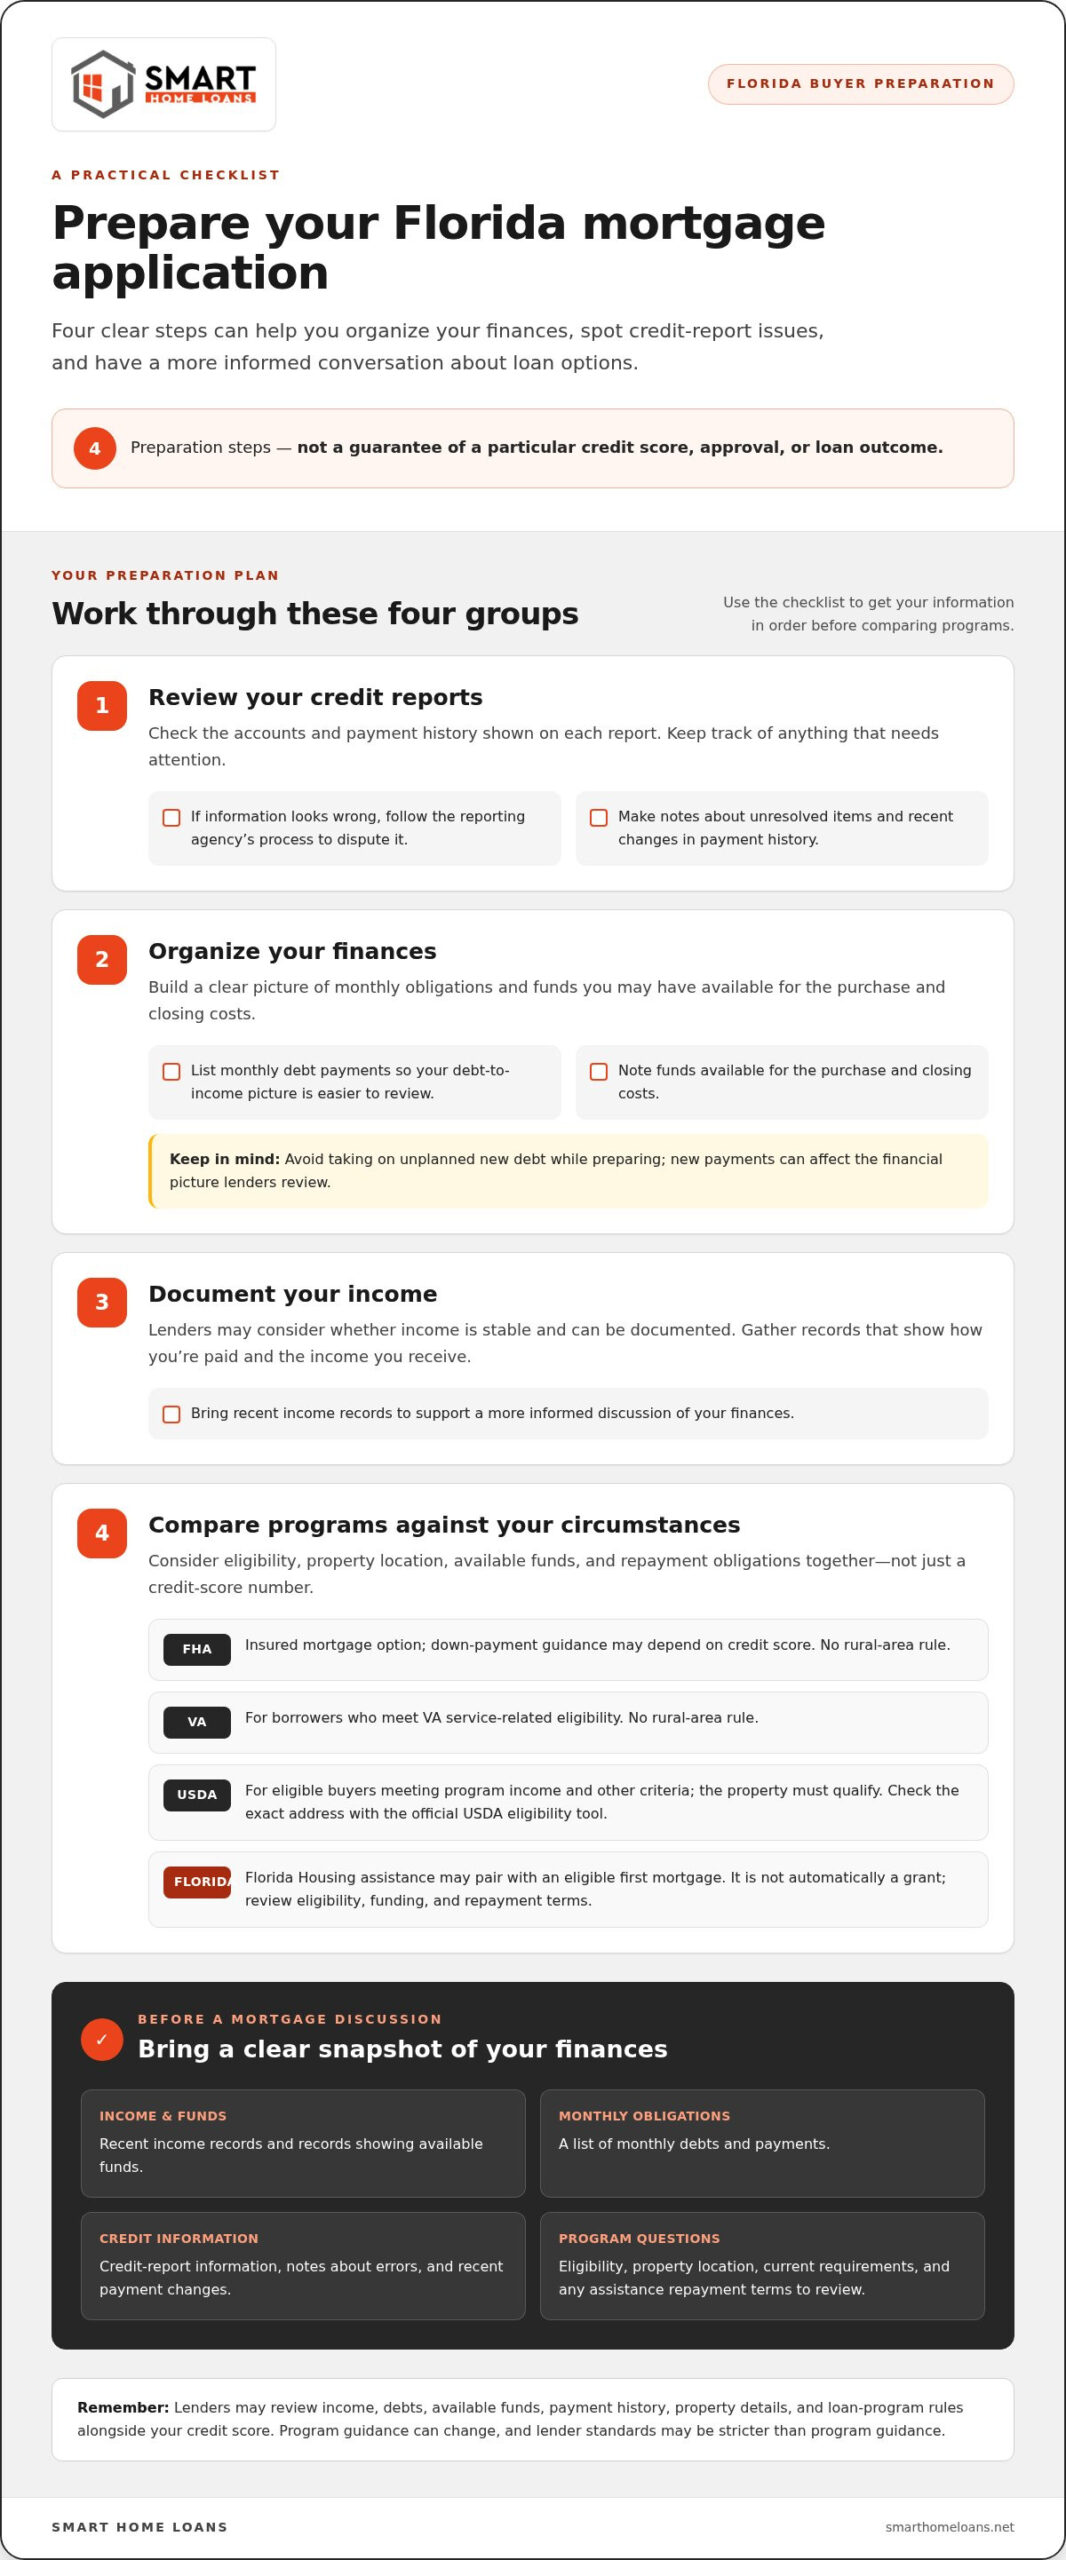
A clear plan can make the mortgage conversation more useful. Take these steps to understand your financial picture, spot issues to address, and prepare accurate information without assuming a particular score will lead to approval.
- Review your credit reports. Check the accounts and payment history shown on each report. If you find information that looks wrong, follow the reporting agency’s process to dispute it. Keep notes on any unresolved items.
- Organize your finances. List monthly debt payments and note the funds you may have available for a purchase. Avoid taking on unplanned new debt while preparing, since new payments can affect the financial picture lenders review.
- Document your income. Gather recent records that show how you’re paid and the income you receive. Clear documentation supports a more informed discussion of your finances.
- Compare programs. Once your information is organized, discuss which mortgage paths may fit your circumstances. Florida assistance has separate eligibility rules, so review the Florida Housing Finance Corporation program details alongside guidance from Smart Home Loans.
What to gather before discussing your mortgage options
Bring recent income records, a list of monthly debts, records showing available funds, and your credit-report information. Include notes about errors or recent payment changes. These details can make a discussion about a home loan with low credit score Florida buyers are considering more specific. For a broader look at what happens from pre-approval through closing, follow the Florida mortgage process guide.
Smart Home Loans offers mortgage options alongside credit-support steps, including credit repair and down payment assistance. Use this guidance to prepare for a personalized discussion, not as a promise of a particular score or loan outcome.
Take the Next Step Toward Homeownership
Your credit history is part of your financial picture, not a verdict on your future. A useful next move is to bring your financial information together and discuss your goals, timeline, and potential options. That can help you approach a home loan with low credit score Florida buyers are exploring with greater clarity, even if you’re still working on your credit.
Smart Home Loans offers FHA, VA, and USDA loans, as well as credit repair and down payment assistance. A mortgage discussion can help you consider preparation alongside loan options without promising a particular score or outcome.
Explore home loan options with Smart Home Loans and take a clear next step toward your home purchase in Saint Augustine or elsewhere in Florida.
Frequently Asked Questions
Can I get a home loan in Florida with a 550 credit score?
Possibly, but a 550 score alone can’t establish eligibility for a home loan with low credit score Florida buyers are considering. General FHA guidance may allow scores from 500 to 579 with a larger down payment, but current HUD requirements matter. Lender standards can be stricter, and the full review includes income, debts, available funds, and property details. Smart Home Loans can help you discuss how those factors apply to your situation.
Will checking my credit before applying for a mortgage lower my score?
Checking your own credit reports generally doesn’t lower your score, because reviewing your information is typically a soft inquiry. A mortgage lender’s credit check may be a hard inquiry, and scoring models can treat inquiries differently depending on timing and circumstances. Reviewing your reports before applying can help you understand what they contain. Before authorizing a mortgage credit review, discuss how it will be handled with Smart Home Loans.
Can I qualify for a Florida mortgage after bankruptcy or foreclosure?
A past bankruptcy or foreclosure doesn’t by itself determine whether you can qualify for a Florida mortgage. The timeline, evidence of financial recovery, current debts, and applicable program rules all matter, and requirements can differ. Don’t assume one waiting period applies to every loan. A review for buyers in Saint Augustine should consider individual circumstances and current program guidance.
Does Florida down-payment assistance automatically make a low-credit mortgage possible?
No. Down-payment assistance and mortgage approval are separate decisions. Florida Housing programs have their own eligibility and lender conditions, and assistance may include repayment terms. It can help with purchase funds, but it doesn’t replace credit, income, property, or underwriting requirements. Review current terms before planning around assistance, including if you’re buying in Saint Augustine.