What if buying a home in Florida didn’t require saving a traditional down payment, but still meant planning for cash at closing? A no down payment home loan Florida buyers may qualify for can bring homeownership closer, but zero down doesn’t always mean zero out-of-pocket costs.
If saving a large amount feels out of reach, comparing loan rules and assistance options can be confusing. This guide explains how eligible buyers may use VA or USDA financing, or pair a low-down-payment FHA loan with assistance. You’ll also learn how Florida and local programs may help with upfront costs, what expenses could remain, and what information to gather before comparing mortgage options. Start by understanding which paths may fit your situation.
Key Takeaways
- A no down payment home loan Florida buyers may qualify for depends on the loan program, borrower, property, and current rules.
- Plan for possible closing costs, prepaid expenses, inspections, and reserves, even when no down payment is required.
- Compare loan options and eligible assistance to understand what may help with upfront costs under program rules.
- For a Saint Augustine-area purchase, outline your finances, review property eligibility, and use a written estimate to understand your cash-to-close needs.
Can you get a no down payment home loan in Florida?
Yes. Some eligible buyers can finance a home purchase without making a down payment from their own funds. A no down payment home loan Florida option depends on the borrower, property, loan program, and current requirements. A mortgage loan is financing secured by the home, and each program sets its own rules for eligible borrowers and properties.
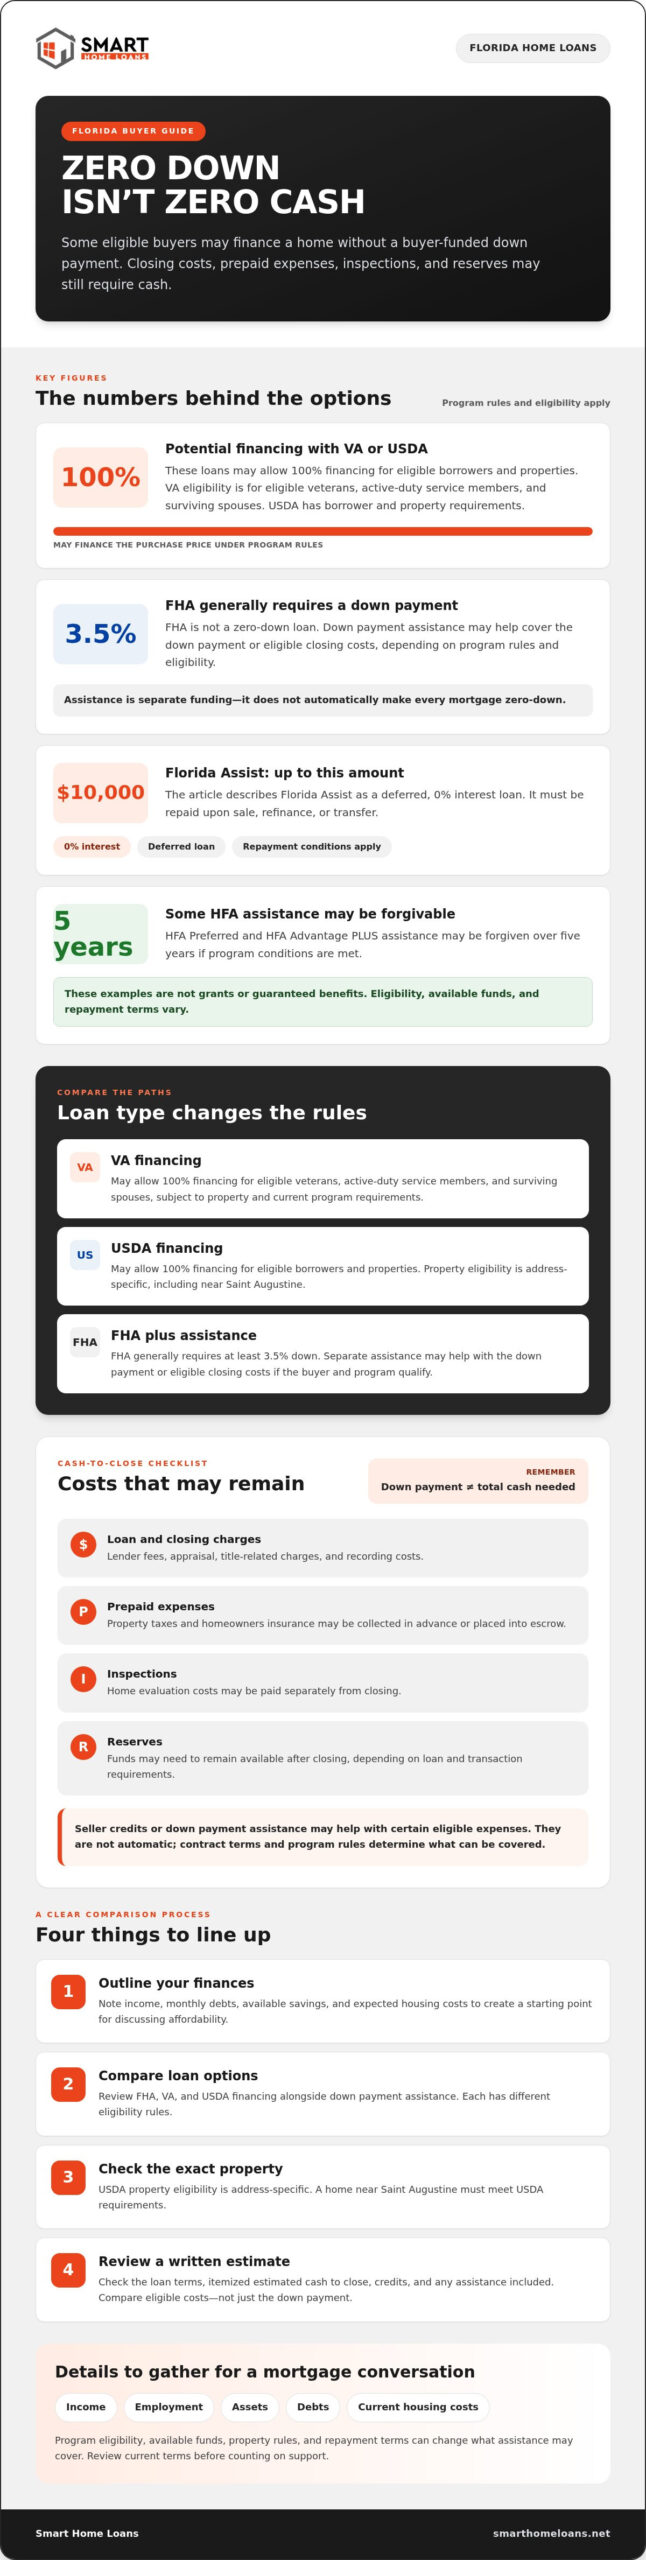
VA and USDA loans may allow 100% financing for eligible borrowers and properties. VA loans are for eligible veterans, active-duty service members, and surviving spouses. USDA financing is limited to eligible properties and borrowers who meet program requirements. A Florida address, including one near Saint Augustine, must meet USDA property rules. FHA is different: it generally requires at least 3.5% down. Down payment assistance may help cover that amount, but FHA itself isn’t a zero-down loan.
How zero-down loans differ from down payment assistance
A zero-down loan finances the purchase without a buyer-funded down payment. Down payment assistance is separate funding that may help with a down payment or eligible closing costs. It doesn’t automatically turn every mortgage into a zero-down loan, and eligibility and available funds vary.
Florida Housing assistance is program-specific financing, often structured as a second mortgage. For example, Florida Assist offers up to $10,000 as a deferred, 0% interest loan that must be repaid upon sale, refinance, or transfer. Other options have different repayment terms. HFA Preferred and HFA Advantage PLUS assistance may be forgivable over five years if program conditions are met. These examples aren’t grants or guaranteed benefits. Review current eligibility, funding, and repayment terms before counting on assistance to reduce your upfront cash.
What costs can remain with a no down payment mortgage?
Zero down doesn’t automatically mean you can buy with zero cash. A no-down-payment loan may remove the buyer-funded down payment, but other expenses can still affect how much you need at closing. The amount depends on the loan, purchase contract, property, and any assistance you qualify for.
Your down payment is only one part of the cash needed to close. Some costs may be due before closing, while others are collected or prepaid at closing. Depending on loan requirements, you may also need funds left over as reserves.
Which upfront expenses should Florida buyers plan for?
Build a working list of potential expenses, then compare it with your personalized estimate. Common categories include:
- Loan and closing charges: lender fees, appraisal, title-related charges, and recording costs.
- Prepaid expenses: items such as property taxes and homeowners insurance collected in advance or placed into an escrow account.
- Inspections: costs for evaluating the home, which may be paid separately from closing.
- Reserves: funds you may need to keep available after closing, depending on loan and transaction requirements.
Seller credits or down payment assistance may help with certain eligible expenses, but they aren’t automatic. Contract terms and program rules determine which costs can be covered and how much support may apply. Florida buyers can review program information from the Florida Housing Finance Corporation, including current eligibility and assistance terms.
Before committing to a purchase, review a written estimate that itemizes expected cash to close and shows any credits or assistance. Compare the loan terms and eligible costs, not just the down payment. Explore mortgage options as you prepare your budget.
How to explore a no down payment home loan in Saint Augustine
Start with your finances, then compare loan options against the home you hope to buy. A no down payment home loan Florida buyers may qualify for depends on personal eligibility as well as property requirements. These steps can make the process clearer:
- Outline your finances. Note your income, monthly debts, available savings, and expected housing costs. This creates a practical starting point for discussing affordability.
- Compare loan options. Review FHA, VA, and USDA financing alongside down payment assistance. Each has different eligibility rules, so compare options against your circumstances rather than assuming one fits every buyer.
- Check the property. USDA eligibility is address-specific. Some areas near Saint Augustine may qualify, but the home’s exact location must meet USDA requirements before you count on this financing.
- Review a written estimate. Look at the loan terms, estimated cash to close, and any assistance included. This helps you understand the full cost picture before moving forward.
Prepare for a mortgage conversation
Gather basic details about your income, employment, assets, debts, and current housing costs. You don’t need every answer in advance. A mortgage discussion can help you compare FHA, VA, and USDA loans with down payment assistance and identify what information may be needed next. You can also review a Florida mortgage process guide and a government-backed loan guide to become familiar with the steps.
Smart Home Loans helps buyers explore mortgage and assistance options, including FHA, VA, and USDA loans. When you’re ready, discuss your Florida home loan options in a practical conversation.
Make your next step a confident one
Your path to a home doesn’t have to begin with having every detail figured out. Start by identifying what you can comfortably afford each month and what funds you could bring to closing. Then use that starting point to discuss no down payment home loan options Florida buyers may qualify for.
Smart Home Loans is a mortgage brokerage offering FHA, VA, and USDA loans, along with down payment assistance and credit repair support. A personalized discussion can help you compare options against your finances and homebuying goals, without assuming one path works for everyone.
Ready to take a clear next step? Explore your Florida home loan options and get a clearer picture of what may work for you. Start with a conversation about your goals and available mortgage paths.
Frequently Asked Questions
Can I buy a house in Florida with no down payment?
Yes, eligible buyers may be able to purchase with no down payment through certain VA or USDA loan paths. A no down payment home loan Florida option depends on borrower eligibility and, for USDA, the specific property. Assistance is different: it may help with eligible upfront expenses but doesn’t automatically make a loan zero-down. Buyers in Saint Augustine should also budget for possible closing costs.
Does an FHA loan require no down payment?
No. FHA is generally a low-down-payment option, not a zero-down-payment loan. Eligible assistance may help cover some upfront expenses, but programs have their own qualification rules, funding conditions, and repayment terms. If you’re comparing FHA with a zero-down option, consider how much cash you have available and whether assistance can be used with the specific loan structure.
Can USDA loans be used to buy a home in Saint Augustine, Florida?
Possibly, but USDA eligibility depends on both the buyer and the property’s exact location. A home’s Saint Augustine mailing address, or its proximity to the city, doesn’t establish eligibility. Check the specific property address against current USDA location requirements, then review borrower qualifications and loan terms before relying on USDA financing for your purchase.
Does a no down payment mortgage mean I need no money at closing?
No. The down payment and total cash to close are different amounts. Depending on the transaction, you may need funds for prepaid items, inspections, or other charges. Assistance or eligible seller credits may reduce some costs if program and contract rules allow. Review an itemized estimate to see which expenses are due before closing and which are collected at closing.