What if that bankruptcy or foreclosure from a few years ago wasn’t the permanent “life sentence” traditional banks made it out to be? It’s incredibly frustrating to feel like a past mistake is blocking your path to Florida property ownership. You might feel anxious about high interest rates or confused by conflicting rules on waiting periods. We understand that stress, and we know that your credit score doesn’t tell your whole story. The truth is that you can often qualify for mortgage after credit setback situations much faster than most people realize.
This 2026 guide busts the myths that keep people from applying. We’ll show you how programs like FHA loans or VA loans offer a second chance for families. You’ll discover clear timelines for reapplying and learn how our local credit repair services bridge the gap between your past and your future home goals. It is time to stop worrying about the past and start planning for your next move.
Key Takeaways
- Debunk the seven-year myth and learn how modern lending rules allow you to return to the housing market much sooner than expected.
- See how you can qualify for mortgage after credit setback challenges with credit scores starting as low as 580 through specialized FHA loan programs.
- Master the 2026 waiting period requirements for government-backed loans to pinpoint exactly when you can start your Florida home search.
- Discover the advantage of a local partner who coordinates credit repair alongside your loan application for a faster, smoother closing.
3 Common Myths About Qualifying for a Mortgage After a Credit Setback
Don’t let outdated advice stall your plans. Many Florida families believe a past financial struggle creates a permanent barrier to owning a home. This misconception often leads to unnecessary anxiety and delays. It’s actually possible to qualify for mortgage after credit setback situations much sooner than most people think. Let’s look at the facts behind the most common myths to see what’s really possible in 2026.
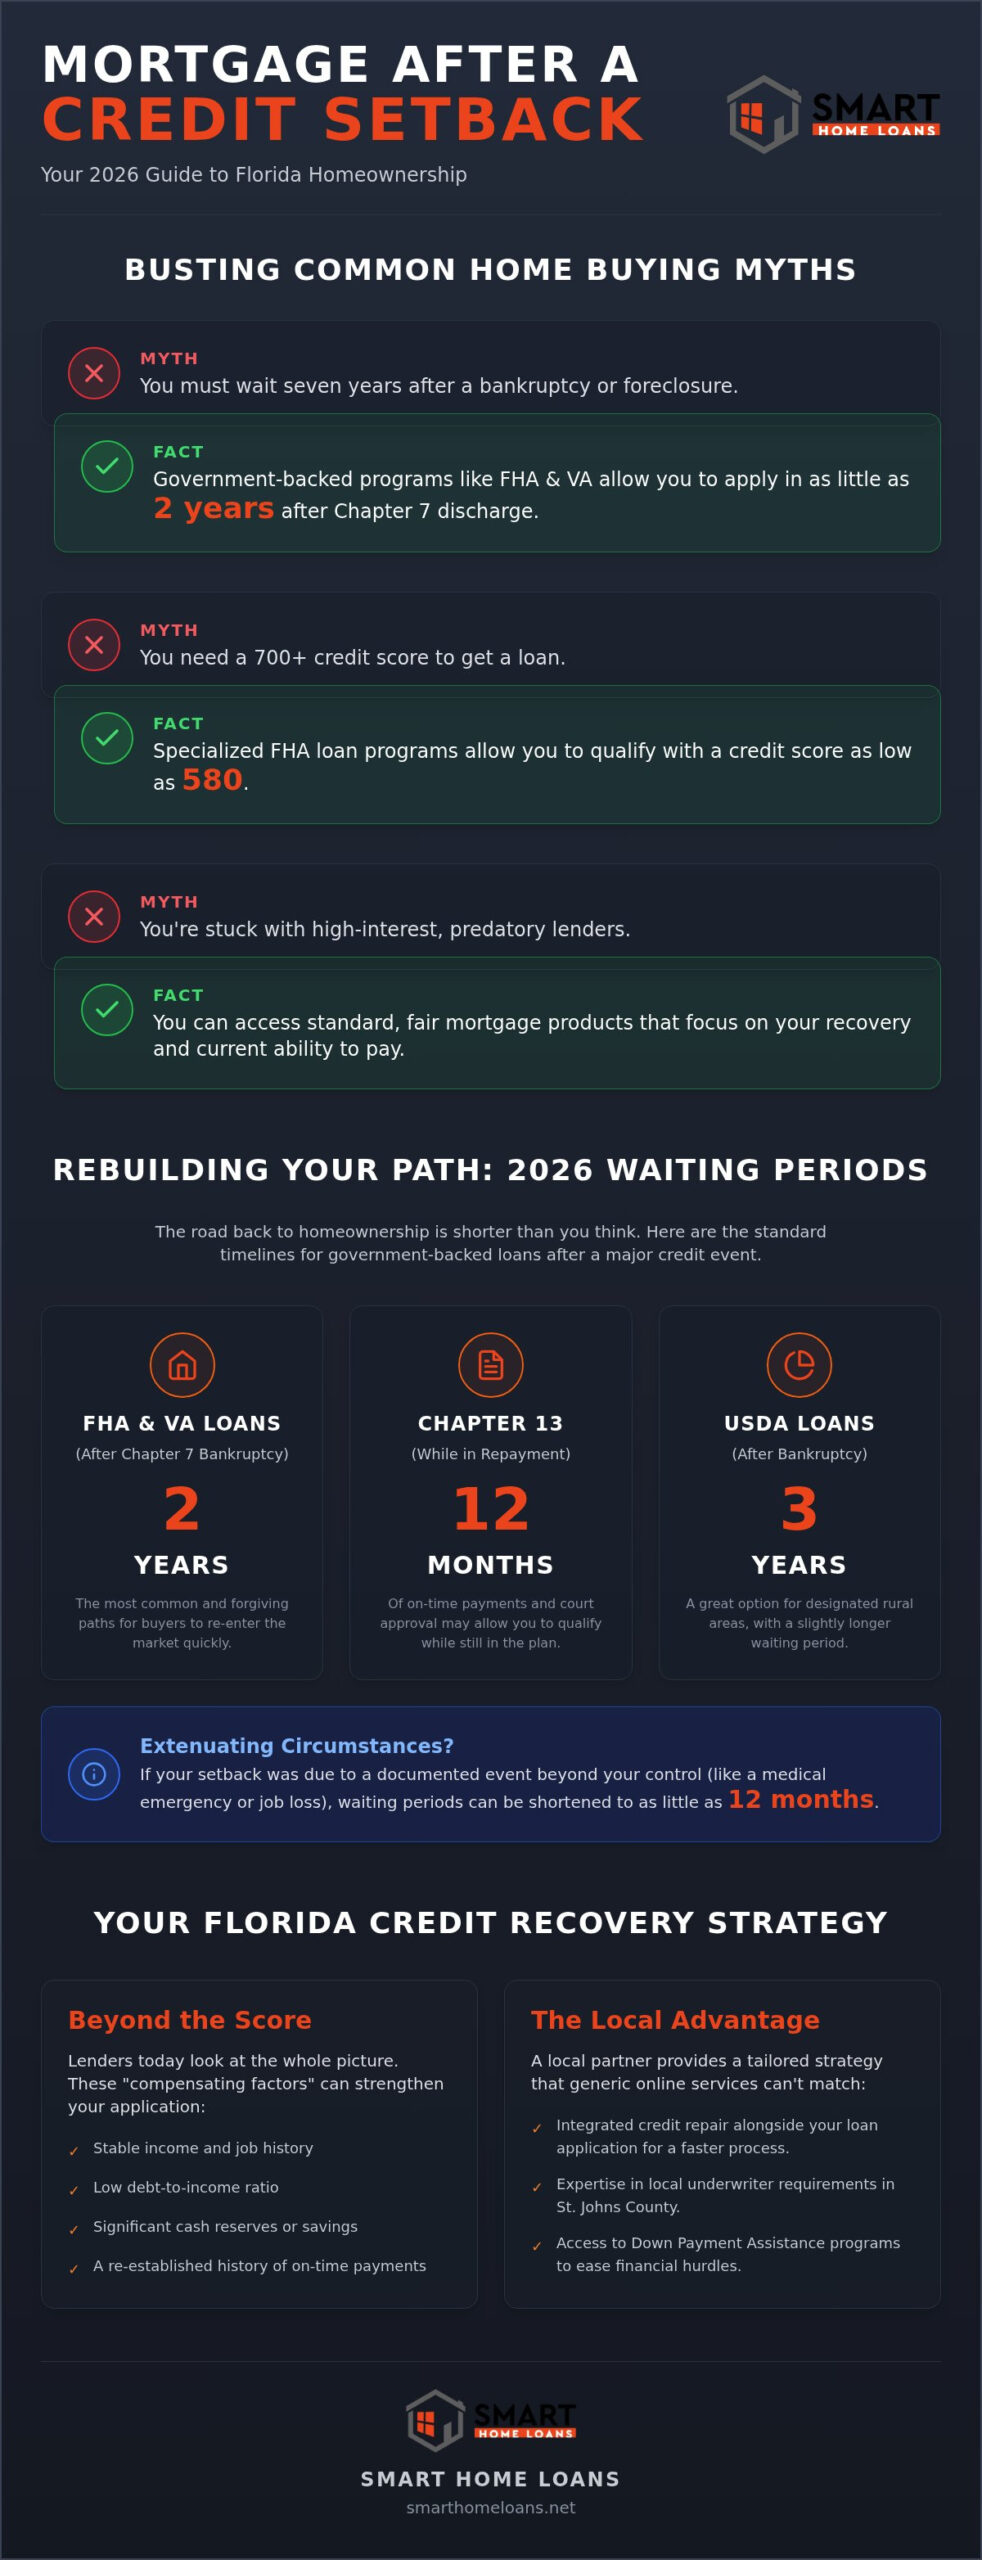
- Myth #1: You must wait seven years after a bankruptcy or foreclosure. This is a major hurdle for many buyers, but it’s rarely the reality. While some traditional lenders have strict rules, government-backed programs are much more flexible. You can often buy again in as little as two years after a Chapter 7 discharge.
- Myth #2: You need a 700+ credit score to get a loan. High scores are helpful, but they aren’t the only way in. We regularly help neighbors secure FHA loans with scores as low as 580. You don’t need “perfect” credit to find a competitive rate; you just need the right loan program.
- Myth #3: You’re stuck with predatory lenders. A single setback doesn’t mean you’re limited to high-interest options. Modern lending focuses on recovery. You can access standard, fair mortgage products that treat you like the responsible borrower you’re today.
Why Your Credit Score Isn’t the Only Factor
Lenders today look at your “compensating factors.” This means they weigh your stable income, low debt levels, and cash reserves against your past credit history. A “Credit Event” mortgage serves as a supportive bridge to standard financing while you rebuild. Specifically, FHA loans with bad credit in Florida prioritize your current financial health. If you have a solid job and a plan, your past doesn’t have to define your future. We focus on your current ability to pay rather than a mistake from years ago. Learning how to qualify for mortgage after credit setback issues is the first step toward your new front door.
Rebuilding Your Path: Waiting Periods and 2026 Requirements
Knowing exactly when you can apply is the first step to peace of mind. Most people assume they are locked out of the market for a decade. In reality, the 2026 guidelines are designed to help you move forward. To qualify for mortgage after credit setback issues, you need to understand the specific clock for your situation. These timelines are shorter than you might think.
Chapter 7 bankruptcy usually requires a two-year wait from the discharge date for FHA and VA loans. Chapter 13 is even more flexible. You might be eligible while still in the repayment plan. You just need 12 months of on-time payments and court approval. USDA loans typically require three years. Start gathering your records now. You’ll need to prove a “re-established” history with 12 to 24 months of perfect payments on utilities or new credit lines.
FHA and VA: The Most Forgiving Paths After a Setback
FHA loans are a fantastic tool for St. Johns County residents. After a Chapter 7 discharge, the standard two-year wait is much shorter than the seven years required by some conventional lenders. It’s the most common way to qualify for mortgage after credit setback events. For our local heroes, VA loans offer even more leniency. Veterans often find that their service history carries significant weight during the manual underwriting process.
Did your setback happen because of a medical emergency or a sudden job loss? The “extenuating circumstances” rule can shorten waiting periods to just 12 months in some cases. This requires specific documentation to prove the event was beyond your control. If you aren’t sure where you stand, our team can help you review your timeline and prepare your documentation. Proving your recovery is easier when you have a neighborly expert by your side.
Taking Control: Your Saint Augustine Credit Recovery Strategy
Generic online “quick fixes” often promise the world but deliver very little. These automated services don’t understand the specific nuances of the Florida mortgage market. To truly qualify for mortgage after credit setback events, you need a strategy tailored to your life. Local expertise matters. We know the St. Johns County landscape and exactly what documentation local underwriters require to see your progress.
Smart Home Loans acts as your proactive partner. We coordinate your Credit Repair while simultaneously preparing your loan application. This integrated approach ensures that as your score rises, your mortgage file is ready to go. We also explore Down Payment Assistance programs. These can help offset the initial costs often associated with recovering credit scores. It’s about building a bridge to your future.
Combining Credit Repair with Smart Lending Strategies
A professional credit audit is your most powerful tool. We help you identify and remove inaccuracies that might be unfairly dragging your score down. Once your report is clean, we focus on government backed home loans in Florida. These programs are specifically designed to support families who are rebuilding. They offer a stable path to homeownership that traditional banks often overlook.
Ready to see your 2026 timeline? We invite you to a neighborly consultation to map out your specific path. We’ll look at your current standing and create a clear, actionable plan. You don’t have to do this alone. Our team is here to handle the obstacles so you can focus on finding your next home. Let’s start the journey to qualify for mortgage after credit setback situations today.
Start Your Journey Home Today
Your past financial challenges don’t have to dictate your future in St. Johns County. We’ve shown that waiting periods for FHA and VA programs are often much shorter than the myths suggest. With a clear strategy and the right local partner, you can qualify for mortgage after credit setback situations and secure the home your family deserves. Our team provides integrated credit repair and lending expertise to ensure your application stands out. We focus on your current financial health and long-term success rather than mistakes from years ago.
Don’t wait another year to discover what’s possible. Take the first step toward your new front door today. Get Your Free Credit Analysis and Mortgage Roadmap and let’s map out your path together. You have the power to change your story, and we’re here to help you every step of the way.
Frequently Asked Questions
How long after a foreclosure can I qualify for an FHA loan in Florida?
You can typically qualify for an FHA loan three years after the date your foreclosure was completed. This is a standard federal requirement, but it’s much shorter than the seven-year wait often required for conventional financing. Our Saint Augustine team helps you track this timeline accurately. We ensure you’re ready to apply the moment your eligibility window opens.
Can I get a mortgage with a 580 credit score after a credit setback?
Yes, you can certainly qualify for mortgage after credit setback situations with a score as low as 580. FHA loans are specifically designed for this purpose, allowing for lower entry scores while still offering competitive terms. In Saint Augustine, we specialize in these government-backed programs. We look at your whole financial picture, including your stable income, rather than just a number.
What is the “extenuating circumstances” rule for mortgage approval?
The “extenuating circumstances” rule allows lenders to shorten waiting periods if your credit event was caused by a one-time matter beyond your control. This might include a sudden job loss or a significant medical emergency. If you can document the event and prove you’ve recovered financially, you might qualify for mortgage after credit setback events in as little as 12 months.
Does credit repair actually help with mortgage approval in Saint Augustine?
Professional credit repair is a vital tool for local buyers. It helps identify and dispute inaccuracies on your report that could be unfairly lowering your score. At Smart Home Loans, we offer integrated credit repair services right here in Saint Augustine. This dual approach means we fix your credit while simultaneously building your loan file, creating a faster and much smoother path to approval.