Zero down may be possible for eligible buyers in St. Augustine: VA loans can require no down payment, and some properties may qualify for USDA financing based on location and household income. A no-down-payment mortgage in St. Augustine isn’t available to everyone, but low-down-payment options can help more buyers move toward homeownership.
It’s understandable to wonder where to begin, especially when assistance programs and loan requirements can feel like a lot to sort through. This guide explains how to start counseling and an application, compare Florida options such as VA, USDA, FHA, and down payment assistance, and understand the local steps involved. You’ll also learn what mortgage lender services can help you assess your options and move toward a home purchase with a clearer plan.
Key Takeaways
- Start by reviewing your credit, income, savings, and homebuying timeline so you can prepare for counseling and an application.
- Compare assistance programs carefully: St. Johns County SHIP has eligibility rules, a purchase price cap, and a required buyer contribution.
- Weigh zero-down options against low-down-payment loans, including how mortgage insurance and repayment terms may affect your budget.
- Explore FHA, VA, USDA, or Jumbo loan options with Smart Home Loans when you’re ready to match a loan path to your situation.
Homebuyer counseling and application steps
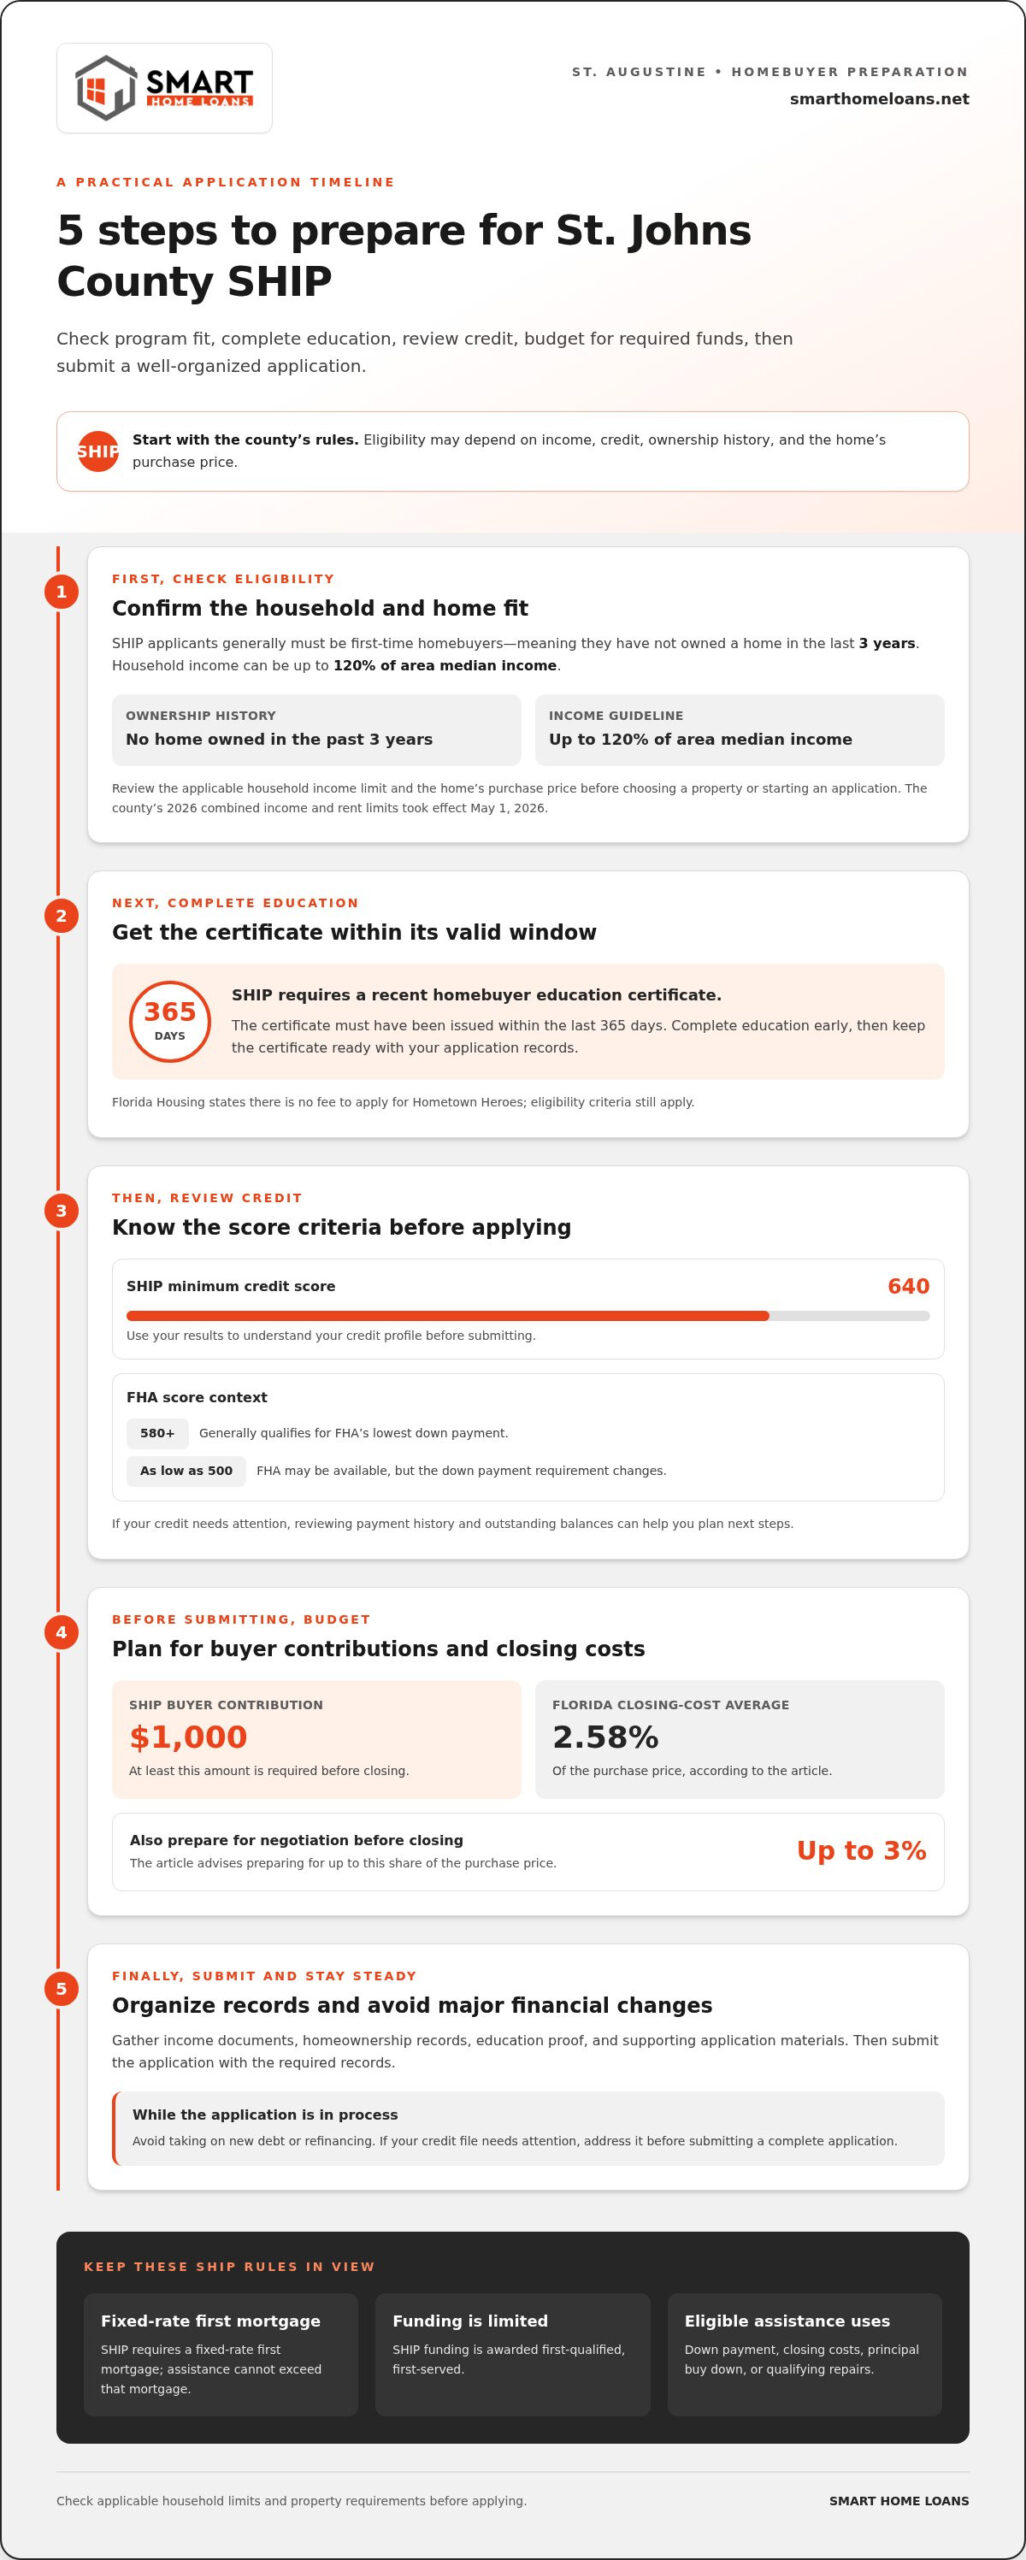
Start by identifying possible assistance programs, gathering financial records, and completing any required homebuyer education. In St. Johns County, eligibility can depend on income, credit, ownership history, and the home’s purchase price.
Education and Income Limits
For St. Johns County SHIP assistance, applicants generally must be first-time homebuyers, meaning they haven’t owned a home in the last three years. Household income can be up to 120% of area median income. The county’s 2026 combined income and rent limits took effect May 1, 2026. Review the applicable household limit before choosing a property or starting an application.
SHIP also requires a homebuyer education certificate issued within the last 365 days. Complete the education step early, then organize income documents and homeownership records for the application. Florida Housing states there’s no fee to apply for Hometown Heroes, another program to consider if you meet its eligibility criteria.
Credit Score and Education Criteria
SHIP applicants need a minimum credit score of 640. Use the results to understand your credit profile before applying. If credit needs attention, reviewing payment history and outstanding balances can help you plan next steps.
For FHA’s lowest down payment, borrowers generally need a score of at least 580. FHA loans may be available with scores as low as 500, but the down payment requirement changes. Keep your education certificate current, since SHIP requires it to fall within its 365-day window.
Before closing, SHIP applicants must contribute at least $1,000 and should prepare for up to 3% of the purchase price in negotiation before closing. Florida buyer closing costs average about 2.58% of the purchase price. Build those costs into your budget alongside the down payment. Then submit your application and supporting records, and avoid taking on new debt or refinancing during the process.
Florida no- and low-down-payment mortgage options
Florida buyers can compare zero-down loans, low-down-payment mortgages, and assistance programs against their monthly budget. Eligibility, property location, credit, and repayment terms all affect which option may fit.
FHA and Conventional Down Payments
Qualified FHA buyers can put down 3.5% with a credit score of at least 580. FHA also charges an upfront mortgage insurance premium of 1.75% of the base loan amount. Compare the minimum down payment with mortgage insurance and funds needed for payment and closing.
VA and USDA Zero-Down Options
Eligible service members, veterans, and some surviving spouses may qualify for VA purchase loans with 0% down. Eligibility can include 90 consecutive days of active service during wartime. USDA loans may offer low- or no-down-payment financing in eligible areas near St. Augustine, based on property location and household income. It isn’t forgivable, and specified changes to occupancy or ownership can make it due.
Rates, Fees, and Monthly Payments
Does Florida offer down payment assistance for St. Augustine homebuyers? Yes. Hometown Heroes is one option; compare its repayment terms with your first mortgage. USDA, VA, and assistance programs don’t have one shared rate, fee, or monthly payment. Loan terms, borrower qualifications, and applicable fees affect the total. FHA’s upfront mortgage insurance premium is 1.75% of the base loan amount. Review the full payment and closing picture, not just the interest rate.
Zero-Down Mortgage Risks
What risks should buyers consider? Zero down means less initial equity, while mortgage insurance, loan costs, or assistance repayment can affect the budget. Hometown Heroes assistance isn’t forgivable and can become due if you sell, refinance the first mortgage, transfer the deed, or stop occupying the home as your primary residence. Compare these obligations with low-down-payment choices, and explore down payment assistance as part of your funding plan.
St. Augustine mortgage lender services
A useful lender conversation connects the first mortgage, assistance rules, and your homeownership budget. Ask for a side-by-side review of eligibility, county limits, required funds, and how assistance affects the amount you borrow.
Eligibility for Florida Hometown Heroes depends on meeting the program’s criteria. A lender can help assess whether your employment and proposed home fit the program, then account for the assistance alongside the first mortgage. Florida Housing states there’s no fee to apply for Hometown Heroes.
St. Johns County SHIP has different requirements. The program requires a fixed-rate first mortgage, and assistance can’t exceed that mortgage. SHIP funding is awarded first-qualified, first-served, so organize income, credit, and property documents before applying. Eligible uses include down payment, closing costs, principal buy down, or qualifying repairs.
Follow a clear sequence: review your credit and income, identify potentially eligible programs, then compare the first-mortgage payment with any deferred assistance repayment. Check whether the home meets SHIP purchase price limits and whether the loan follows its fixed-rate requirement. If your credit file needs attention, address it before submitting a complete application. This helps you understand the approval process and assistance terms together, rather than treating payment assistance as a separate decision.
Explore down payment assistance options as you prepare your financing plan.
Smart Home Loans: FHA Home Loans
Smart Home Loans can help you compare FHA Home Loans with VA, USDA, and Jumbo options. Turn to this step once you understand assistance rules and want to match a mortgage path to your credit profile, eligible property, and available funds. FHA financing may suit buyers who can make a low down payment, while VA or USDA options may fit eligible buyers seeking zero-down financing. Jumbo Loans provide another option when the purchase requires financing beyond standard loan limits. The right comparison looks beyond the initial payment. Consider ongoing mortgage costs, assistance repayment terms, and the cash needed for closing. Bring your income details, credit information, and preferred home price to start a focused discussion. Contact Smart Home Loans to discuss your mortgage options.
Take the Next Step Toward Homeownership
Start by deciding what matters most to you: preserving savings, keeping monthly payments manageable, or finding a home that fits your needs. Let that priority guide your next conversation about a no-down-payment mortgage in St. Augustine. Bring questions about eligibility, available funds, and how the loan terms fit your budget.
Smart Home Loans offers FHA Home Loans, VA Loans, and USDA Loans. Each path has different qualification criteria and payment considerations, so the next step is matching your goals with an option that fits your circumstances. If your plans or finances change, that conversation can also help clarify what to consider before making a major borrowing decision.
Contact Smart Home Loans to get started. A thoughtful first conversation can help turn your homebuying goal into a practical plan.
Frequently Asked Questions
How do I get started?
For a no-down-payment mortgage in St. Augustine, begin by considering VA, USDA, or Florida assistance paired with an eligible first mortgage. Gather income and employment records, details about monthly debts, and the address or area where you hope to buy. Then discuss them with a mortgage professional or housing counselor. This focuses the initial conversation on eligibility, property fit, and the application steps that apply to you.
What no-down-payment mortgage programs are available in St. Augustine, Florida?
Eligible VA buyers may qualify for a purchase loan with no down payment, while USDA financing may fit homes in eligible locations. Florida Hometown Heroes assistance can be paired with an FHA, VA, RD, or conventional first mortgage for eligible borrowers. St. Johns County SHIP is another assistance program, but its rules and required buyer contribution mean it isn’t a zero-cash-at-closing option for everyone.
Can eligible buyers use a USDA loan to buy a home in St. Augustine?
Yes, eligible buyers can use USDA financing for a home in an eligible area near St. Augustine. When comparing no-down-payment mortgage options in St. Augustine, consider the specific property address because location affects USDA eligibility. The program also considers household income. Two homes in the same general market may have different eligibility outcomes if they fall under different program boundaries.
What are the income, credit score, and purchase price limits for Florida housing assistance programs?
The county’s 2026 combined income and rent limits took effect May 1, 2026. Hometown Heroes has separate eligibility requirements, so don’t apply SHIP’s limits to that program.
Which areas near St. Augustine are eligible for USDA financing?
USDA eligibility depends on the property’s location, not simply on whether a buyer describes the home as near St. Augustine. The program also considers household income. The specific property address is essential: assess the home’s location and household income under USDA eligibility rules before relying on this financing in your purchase plan.