What if the closest mortgage broker isn’t the right fit for your goals? Searching for a “local mortgage broker near me” in Saint Augustine is a practical first step. You’ll also want someone who explains your options clearly and answers questions without pressure.
It’s normal to be unsure which loan program fits your finances, what costs to ask about, or how to assess a broker’s local knowledge. This guide explains how to compare mortgage professionals, what questions to ask, and which credentials and disclosures to review before applying.
You’ll also learn how to discuss FHA, VA, USDA, and jumbo loan paths, including what to clarify about eligibility and next steps. The goal is a clearer conversation about financing that fits your homebuying plans.
Key Takeaways
- When searching for a local mortgage broker near me, weigh clear communication and loan fit alongside location.
- Ask which loan programs and lenders a broker can access, and how broker compensation works.
- Verify the broker’s credentials and review disclosures so you understand the process before applying.
- Gather details about your income, debts, savings, and timeline to make an initial discussion more useful. This can help identify possible paths, but it isn’t an approval or rate guarantee.
Finding a Local Mortgage Broker Near Me in Saint Augustine
Searching for a local mortgage broker near me often means you want more than a nearby name. You want someone who listens, explains your choices in plain English, and helps you work out what to ask next. A mortgage broker acts as an intermediary between borrowers and lenders. For a neutral overview of the role, see What is a mortgage broker.
Proximity can make conversations feel more personal, and familiarity with Saint Augustine may help a broker understand the local context. But location alone won’t tell you whether a loan option suits your finances or whether communication will be clear. Compare each professional’s:
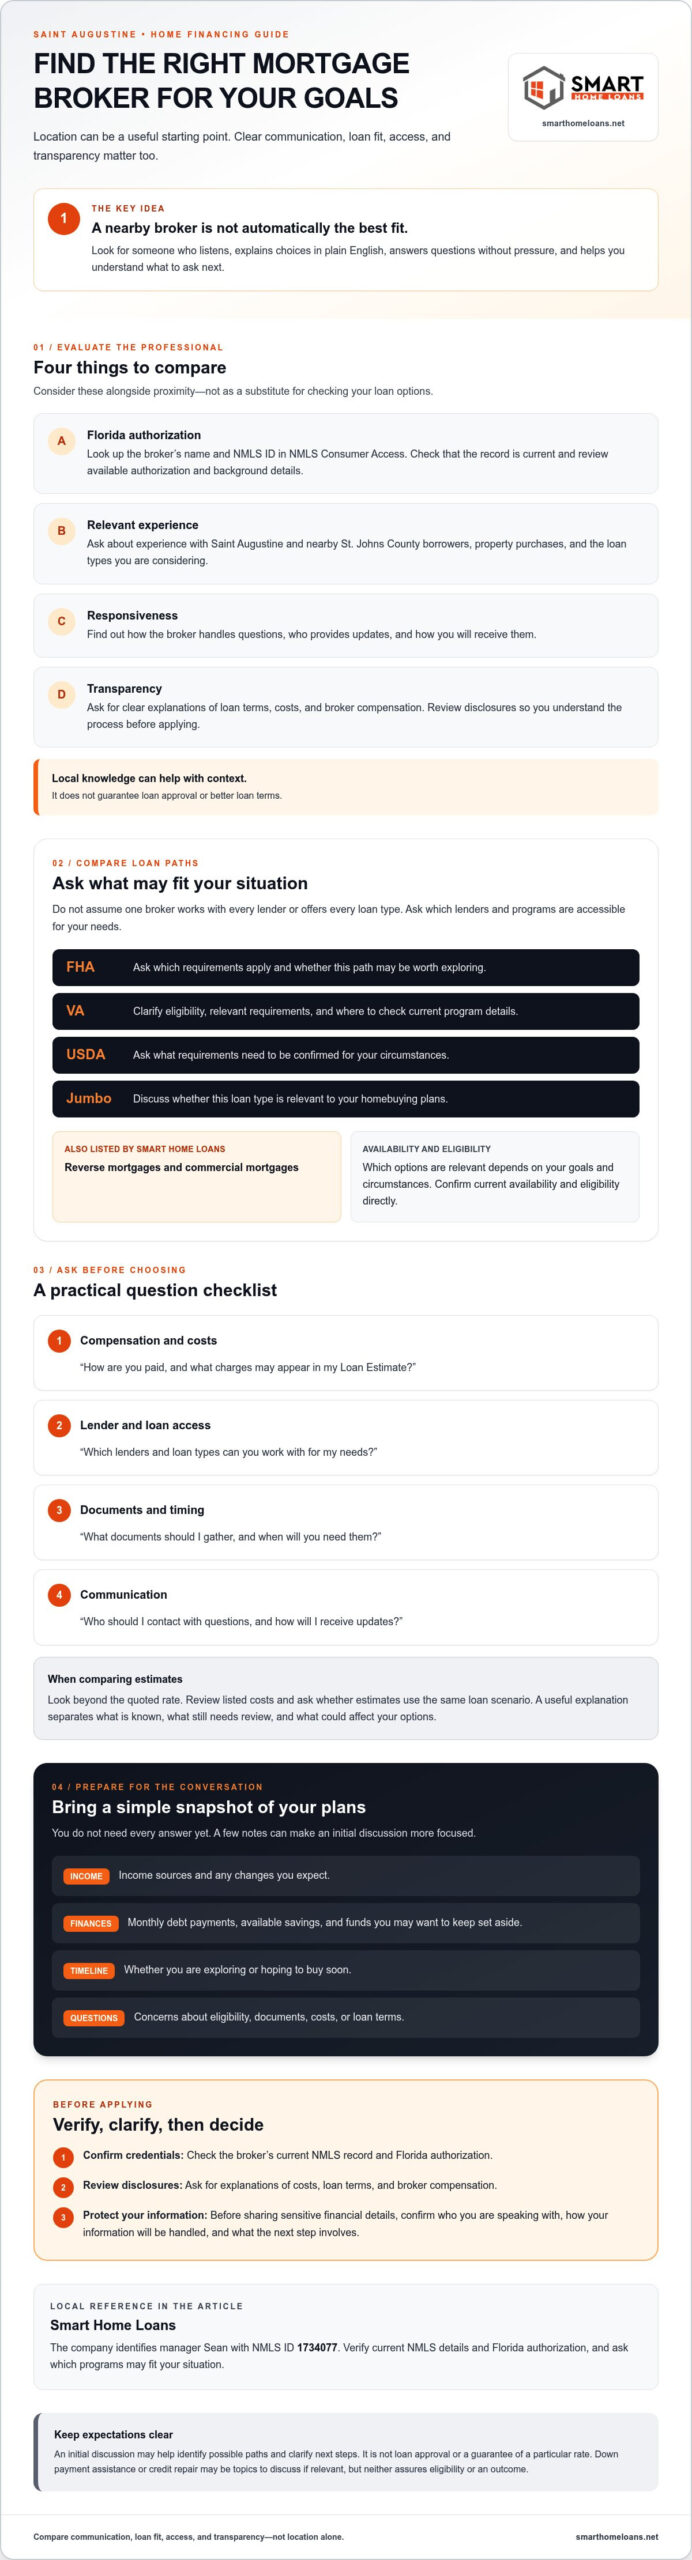
- Florida authorization: Check current details through NMLS Consumer Access.
- Relevant experience: Ask about work with Saint Augustine and nearby St. Johns County borrowers, and with the loan types you’re considering.
- Responsiveness: Find out how the broker handles questions and provides updates.
- Transparency: Ask for clear explanations of loan terms, costs, and broker compensation.
What should a Saint Augustine borrower verify first?
Look up the broker’s name and NMLS ID in NMLS Consumer Access. Check that the record is current, then review the available authorization and background details. Ask how familiar the broker is with borrowers and property purchases in Saint Augustine and St. Johns County. Local knowledge can be helpful, but it doesn’t guarantee approval or better loan terms.
Smart Home Loans is one local starting point for discussing FHA, VA, USDA, and jumbo loan options. The company identifies manager Sean with NMLS ID 1734077. Verify current NMLS details and Florida authorization before proceeding, and ask which programs may fit your situation. A clear, pressure-free conversation should leave you better informed, not rushed to apply.
How to Compare Local Mortgage Brokers and Their Loan Options
Start by telling each broker what you hope to buy, your approximate timeline, and what matters most to you in a monthly payment. Then ask which loan programs and lenders they can access for your situation. Don’t assume one broker works with every lender or offers every loan type.
FHA, VA, USDA, and jumbo loans have different eligibility rules and terms. Ask which programs may be worth exploring, what requirements you need to confirm, and where to check current program details. When comparing estimates, look beyond the quoted rate. Review the listed costs and ask whether the figures are based on the same loan scenario. A useful explanation should distinguish what’s known, what still needs review, and what could affect your options.
Questions to ask before choosing a mortgage broker
Use these questions to assess transparency and communication:
- Compensation: How are you paid, and what charges may appear in my Loan Estimate?
- Access: Which lenders and loan types can you work with for my needs?
- Preparation: What documents should I gather, and when will you need them?
- Communication: Who should I contact with questions, and how will I receive updates?
Listen for clear answers in plain language. If a cost or loan term is unclear, ask for an explanation before moving forward. A broker should help you understand the process without pressuring you to apply. To review options available through a local brokerage and prepare questions for a conversation, you can explore Smart Home Loans’ mortgage options.
Taking the Next Step With a Saint Augustine Mortgage Broker
Before speaking with a broker, gather a simple snapshot of your finances and plans. You don’t need every answer yet. A few notes can make the conversation more focused:
- Income: Your income sources and any changes you expect.
- Debts and savings: Monthly debt payments, available savings, and funds you may want to keep set aside.
- Homebuying timeline: Whether you’re exploring or hoping to buy soon.
- Questions: Write down concerns about eligibility, documents, costs, or loan terms.
Smart Home Loans lists FHA, VA, USDA, jumbo, and reverse mortgages, as well as commercial mortgages. Which options are relevant depends on your goals and circumstances. Confirm current availability and eligibility directly.
What to expect from an initial mortgage conversation
Start by describing what you hope to do and where you feel uncertain. Ask which possible paths may be worth exploring and what information would help assess them. An initial discussion can clarify next steps, but it isn’t loan approval or a guarantee of a particular rate.
If your savings or credit history is a concern, ask whether down payment assistance or credit repair may be relevant. These are options to discuss, not assurances of eligibility or an outcome. Before sharing sensitive financial information or applying, confirm who you’re speaking with, how your information will be handled, and what the next step involves.
If you’re looking for a local mortgage broker near me in Saint Augustine, you can discuss mortgage options with Smart Home Loans and ask which path may fit your goals.
Move Forward With a Clearer Mortgage Plan
Choosing a local mortgage broker near me is about more than finding someone nearby. Look for clear answers, transparent costs, and loan options that fit your goals. Ask which lenders and programs are available to discuss, and confirm eligibility before moving forward. An initial conversation can clarify possible next steps, but it isn’t approval or a rate guarantee.
Smart Home Loans lists FHA, VA, USDA, and jumbo loans, along with down payment assistance and credit repair as options to discuss. The company identifies Sean as manager with NMLS ID 1734077. Verify his current registry details before proceeding.
Talk with Smart Home Loans about your mortgage options and bring your questions about loan fit, costs, and eligibility. Clear information and a pace that feels right for you can help you take your next step with greater confidence.
Frequently Asked Questions
Is it better to use a local mortgage broker near me?
A local mortgage broker near me may make communication easier and bring familiarity with Saint Augustine and the surrounding area. Still, compare more than distance. Ask whether the broker can discuss options suited to your circumstances, explain disclosures and costs, respond clearly, and provide verifiable credentials. Local knowledge can be useful, but location alone doesn’t guarantee approval, a lower rate, or better loan terms.
How do I check whether a mortgage broker is licensed in Florida?
Use NMLS Consumer Access to look up the broker’s current information and authorization. Check that the name and NMLS identifier match the person you’re speaking with, and review the available record details. If something doesn’t match or is unclear, ask the broker to explain before proceeding. This registry check is a practical verification step, not individual legal or financial advice.
How much does it cost to use a mortgage broker?
The broker’s compensation and any borrower charges can vary depending on the transaction and arrangement. Ask directly who pays the broker, what fees may apply, and how each charge will be disclosed. Review the Loan Estimate and ask the broker to explain any listed costs in plain language. Don’t rely on assumptions about fees or compensation; clarify the details for your situation.
Can a local mortgage broker help me compare FHA, VA, USDA, and conventional options?
A broker can discuss loan paths that may fit your circumstances, but available options, lender access, and eligibility vary. Ask which FHA, VA, USDA, or conventional options the broker can actually help you compare, and confirm current program requirements before making decisions. Smart Home Loans lists FHA, VA, and USDA loans, but conventional loans aren’t among its confirmed offerings.