What if a rate quote tells you less about your home-buying budget than you think? For mortgage pre-approval Saint Augustine buyers need more than an estimated payment. They need a documented buying range based on verified finances and a realistic look at local costs.
It’s understandable to feel unsure about which documents to gather, how pre-approval differs from prequalification, or whether taxes and homeowners insurance could change what feels affordable. This guide breaks the process into clear steps, so you can prepare a complete application and make informed decisions before you shop.
You’ll learn what financial records to collect, how FHA, VA, USDA, and other loan paths may compare, and which Saint Augustine-area costs to include in your budget. With a clearer picture of your options and monthly expenses, you can approach an offer with more confidence.
Key Takeaways
- Understand how pre-approval differs from prequalification, a rate quote, and final underwriting, so you know what a lender’s estimate does and doesn’t confirm.
- Use a practical mortgage pre-approval Saint Augustine checklist to organize financial details and move through the application steps with confidence.
- Compare FHA, VA, USDA, and other loan paths based on your circumstances, then review the terms that shape your estimated buying range.
- Build a fuller home budget by separating principal and interest from property taxes, insurance, HOA fees, and other property-specific costs.
What Mortgage Pre-Approval Means for Saint Augustine Homebuyers
A mortgage pre-approval is a lender’s preliminary review of your financial information, such as income, assets, debts, and credit, to estimate how much you may be able to borrow. It gives you a documented buying range to use while planning, not a promise that a loan will close. For a neutral overview of mortgage pre-approval, see how it differs from pre-qualification and fits into the home-buying process.
These terms aren’t interchangeable. Prequalification is generally a less formal estimate based largely on information you provide. A rate quote focuses on possible interest-rate terms and may not include a full review of your finances. Pre-approval typically involves checking financial documents and credit. Final underwriting comes later, when the lender evaluates the complete application and property details before making a final loan decision.
A pre-approval is preliminary: the property, updated documentation, and underwriting review can change the final loan decision. That distinction matters as you consider mortgage pre-approval Saint Augustine options. Treat the estimated borrowing range as a planning tool, not a target you must spend up to.
What a pre-approval letter can and cannot tell you
A letter can help show sellers that you’ve taken steps to understand your financing when you make an offer. It may state an estimated loan amount and other conditions, but it doesn’t guarantee final approval, a specific interest rate, or financing for every property. The lender may still need to verify information and assess the home against the chosen loan’s requirements.
Letter terms and validity periods vary. Follow the timeline stated by your lender, and share updates if your finances or home-buying plans change. This keeps your expectations grounded as you move from a preliminary estimate toward a complete application.
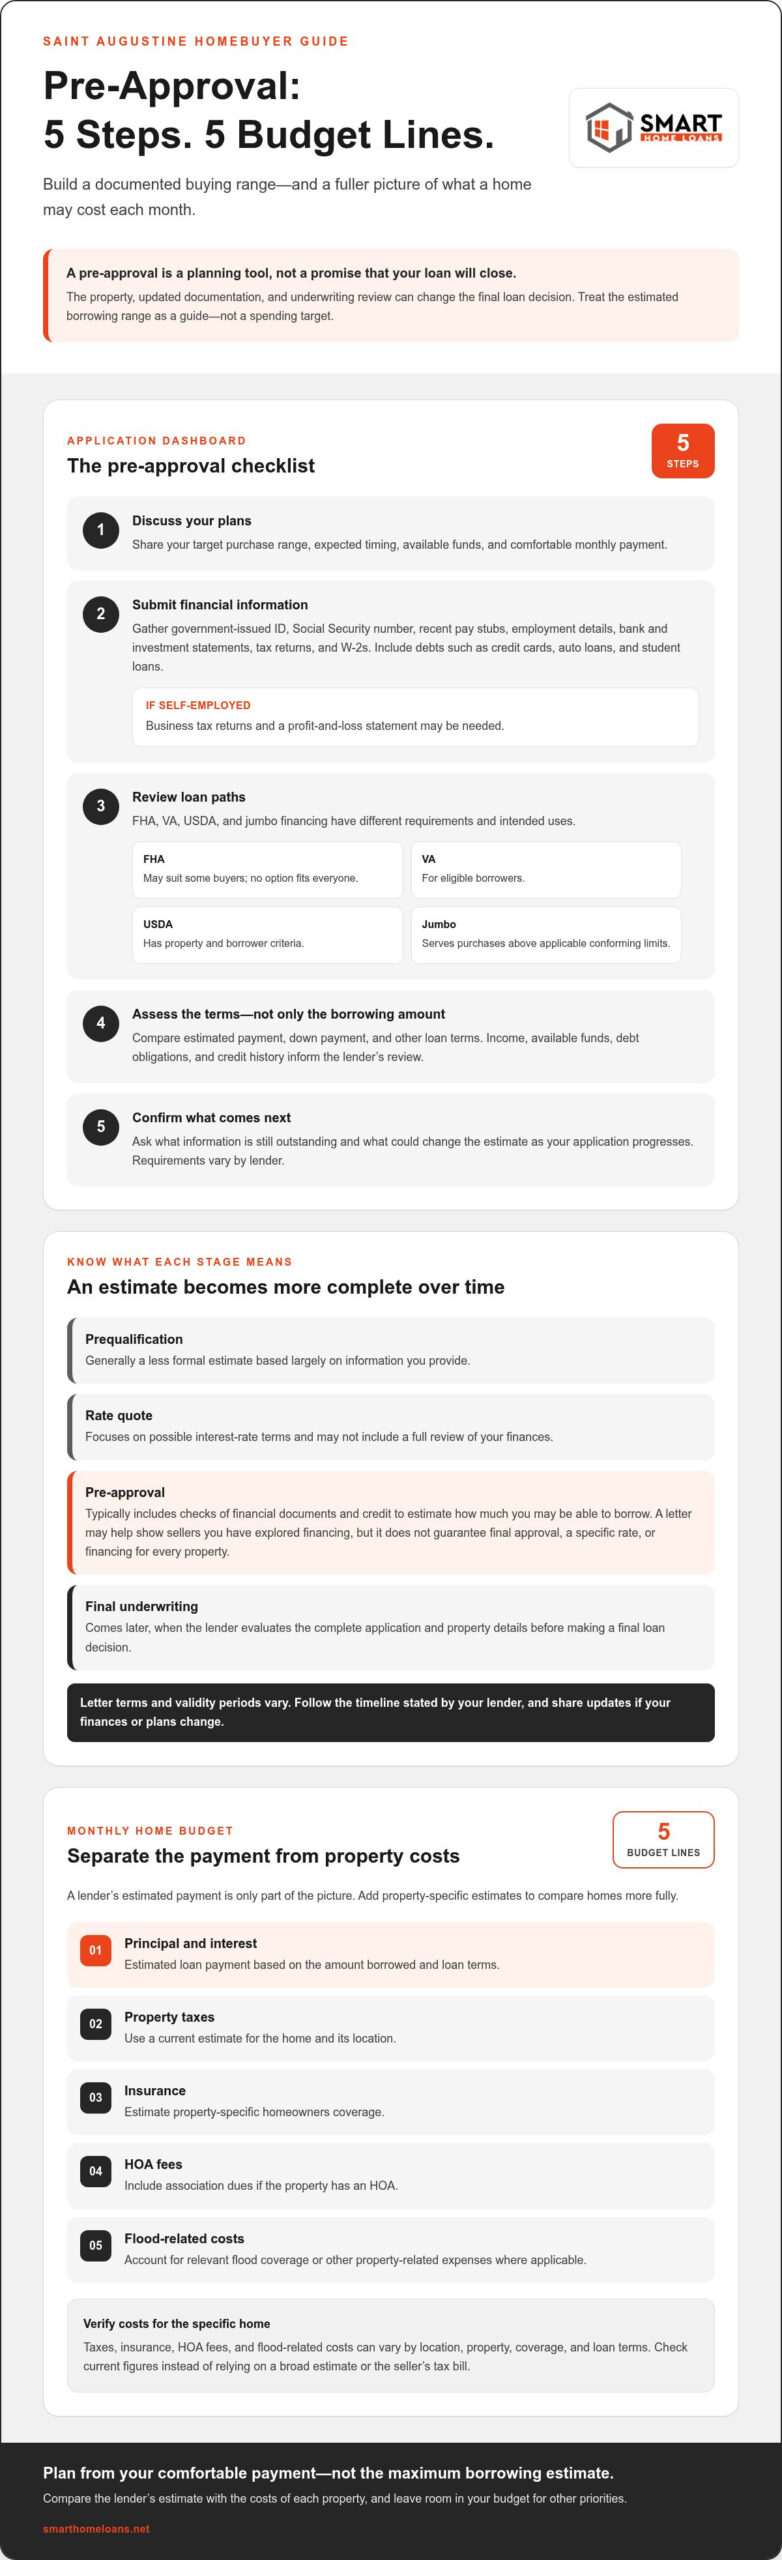
Mortgage Pre-Approval in Saint Augustine: A Checklist
A clear application starts with your goals and the right records. Use these steps to organize the process. Lender requirements vary, so be ready to provide additional information if requested.
- Discuss your plans. Share your target purchase range, expected timing, available funds, and monthly payment comfort zone.
- Submit your information. Gather government-issued ID, Social Security number, recent pay stubs, employment details, bank and investment statements, tax returns, and W-2s. Include details about debts, such as credit cards, auto loans, and student loans. Self-employed buyers may need business returns and a profit-and-loss statement. Experian’s guide to documents you’ll likely need offers another useful preparation list.
- Review loan paths. FHA, VA, USDA, and jumbo financing have different requirements and intended uses. For example, VA options are for eligible borrowers, USDA financing has property and borrower criteria, and jumbo loans serve purchases above applicable conforming limits. FHA may suit some buyers, but no option fits everyone.
- Assess the terms. Compare estimated payment, down payment, and other loan terms, not just the amount you may borrow. Income, available funds, debt obligations, and credit history all inform the lender’s review.
- Receive next steps. Ask what information remains outstanding and what could change your estimate as the application progresses.
Prepare your finances and compare loan paths
Review your statements for accuracy and organize records before applying. If you’re concerned about credit history, read this FHA loan guide for buyers with credit challenges. For a wider view of the process, explore the Florida mortgage process. A mortgage pre-approval Saint Augustine application is easier to navigate when your goals and documents are ready. Explore mortgage guidance as you compare your next steps.
Set a Realistic Saint Augustine Budget and Take Your Next Step
A lender’s estimated payment is only part of your home budget. For each property, account for taxes, homeowners insurance, any HOA fees, and flood-related costs or requirements where applicable. These expenses can vary by location, property, coverage, and loan terms, so verify current figures for the specific home instead of relying on a broad estimate or the seller’s tax bill.
Use this simple breakdown to compare homes. Keep principal and interest separate from other costs, then add property-specific estimates for a fuller monthly picture.
| Budget item | What to include |
|---|---|
| Principal and interest | Estimated loan payment based on the amount borrowed and loan terms |
| Property taxes | Current estimate for the home and its location |
| Insurance | Property-specific homeowners coverage estimate |
| HOA fees | Association dues, if the property has an HOA |
| Flood-related costs | Relevant flood coverage or other property-related expenses, where applicable |
Turn a pre-approval into a confident home search
Choose a monthly budget that leaves room for your other priorities. Don’t treat the maximum borrowing estimate as a spending target. The Consumer Financial Protection Bureau explains how a preapproval letter from a lender can help show sellers you’re prepared, while your own budget helps keep the search grounded. With mortgage pre-approval Saint Augustine buyers can plan more confidently when they compare the lender’s estimate with the costs of each property.
Gather your documents, note your comfortable payment range, and discuss which financing path fits your circumstances with Smart Home Loans. Explore mortgage options with Smart Home Loans.
Take Your Next Step Toward a Confident Home Search
A strong mortgage pre-approval Saint Augustine plan starts with organized financial documents, a loan path that fits your circumstances, and a budget that accounts for property-specific costs. Remember, a pre-approval is a starting point, not a guarantee. Compare the estimated payment with taxes, insurance, HOA fees, and any applicable flood-related expenses before deciding what feels comfortable.
Smart Home Loans, managed by Sean, can help you compare FHA, VA, USDA, and jumbo loan options. Credit repair and down payment assistance are also possible support topics, depending on your situation and eligibility. Together, these steps can help you move forward with a clearer picture of your choices.
Ready to explore a suitable path? Explore your mortgage options with Smart Home Loans. Take it one step at a time. A thoughtful start can make your home search feel more manageable.
Frequently Asked Questions
Does mortgage pre-approval guarantee I will get a home loan?
No. Pre-approval is a preliminary assessment, not a promise that a lender will finance a purchase. Final approval may depend on verifying your finances, reviewing the property and appraisal, and completing underwriting. Keep your information current and respond to document requests. For Saint Augustine homebuyers, treat the letter as a planning tool, not guaranteed financing for every property.
How long does mortgage pre-approval take in Saint Augustine?
Timing depends on how quickly you provide complete information and how the lender reviews your application. Start the mortgage pre-approval Saint Augustine process before you’re ready to make an offer, so there’s time to address questions that come up. Ask about next steps and outstanding documents rather than relying on a universal timeline. Prompt, complete responses can help keep your application moving.
Does getting mortgage pre-approval affect my credit score?
A lender may review your credit, and a credit inquiry can affect your score. The effect and treatment of inquiries depend on the scoring model and your circumstances. Before applying, ask how the credit review is handled. While your application is under review, avoid opening or changing credit accounts without discussing the timing with your lender, since changes may affect the financial picture being assessed.
What should I bring to a mortgage pre-approval appointment?
Prepare details about your identity, income, employment, assets, debts, and available funds. You may need government-issued identification, your Social Security number, recent pay stubs, bank statements, tax returns, and W-2s. Requirements vary with your circumstances and the lender’s process. Mention early if you’re considering FHA, VA, USDA, or jumbo financing, so the discussion can focus on relevant loan options.