Yes, St. Johns County SHIP down payment assistance may cover repairs needed to make homeownership affordable, as well as down payment and closing costs. For down payment assistance in St. Augustine, the key is matching your finances and home purchase to the program’s rules.
It’s easy to assume your credit score or homebuying history could rule you out. The guidelines are specific, but understanding them can help you see where you stand and what to prepare.
Learn how household income, purchase limits, credit score requirements, and the first-time buyer definition affect eligibility. You’ll also find out how repair funds work and how other assistance options may fit your plans.
Key Takeaways
- Compare your household’s income with the limit for the specific assistance program, and account for all adult residents when the program requires it.
- SHIP funds may help with eligible repairs as well as purchase costs. According to St. Johns County, its assistance is a 15-year deferred loan forgiven at 10% per year beginning in year 6.
- Review the credit and ownership rules early: SHIP requires a credit score of at least 640, and its first-time buyer definition looks at whether you owned a home during the prior three-year period.
- Once you understand your eligibility, explore whether an FHA Home Loan can fit your purchase and financing needs.
St. Johns County income limits by household size
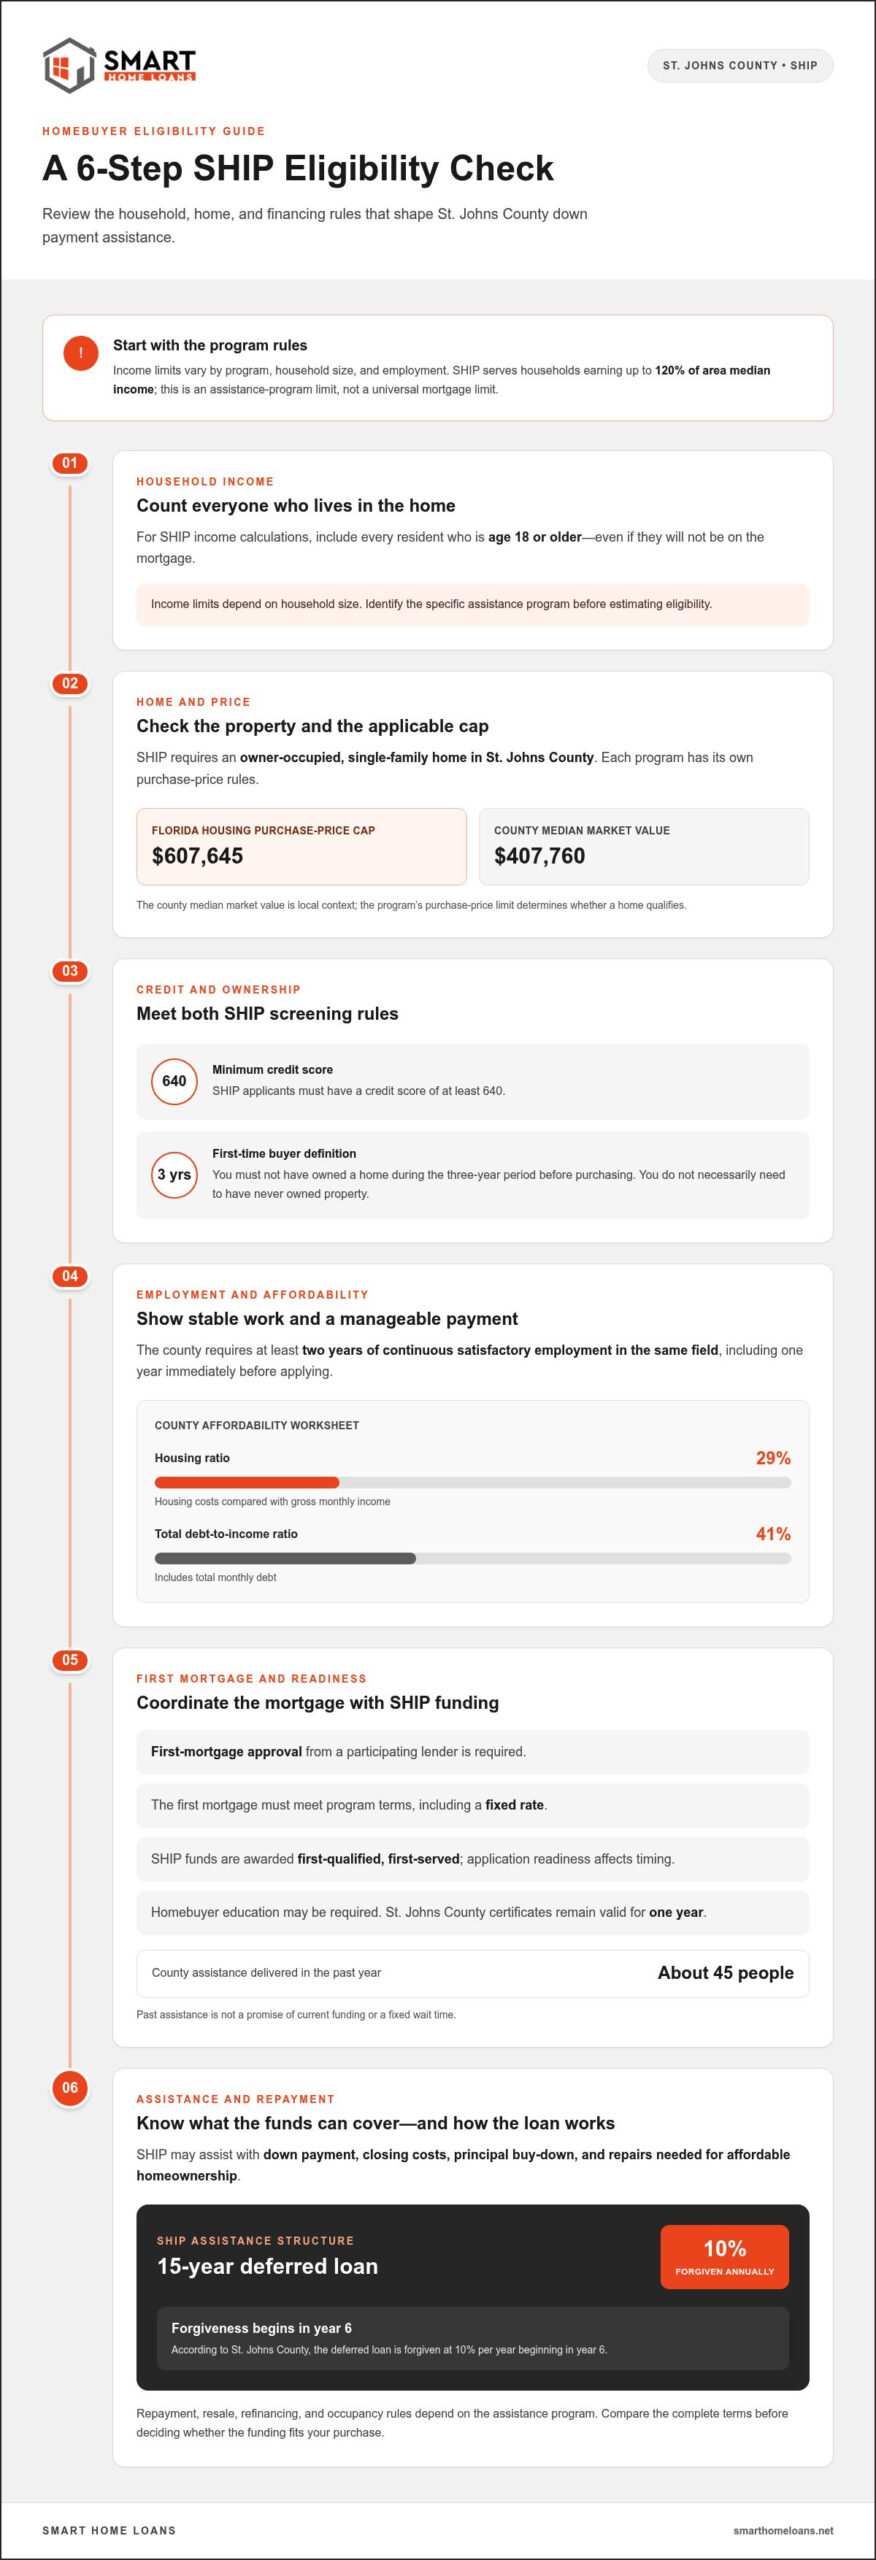
Income caps vary by program, household size, and employment. St. Johns County SHIP serves households earning up to 120% of area median income. These limits apply to housing assistance, not a universal mortgage limit, so identify the program before estimating eligibility.
Income includes everyone age 18 or older who lives in the home, even if they won’t be on the mortgage. Reservations on or after May 6, 2026, use these limits. Florida Housing’s St. Johns County purchase-price cap is $607,645.
Occupation matters for Hometown Heroes. Qualifying borrowers must work full time for a Florida-based employer, except for the listed servicemember category. Hybrid employees may qualify if they report to a physical Florida work location at least three days per week. Florida’s 2026 allocation opened July 13, with funds reserved first come, first served through participating lenders.
Repayment, resale, refinancing, and occupancy rules depend on the assistance program. Hometown Heroes assistance is a deferred second mortgage, due in full if the home is sold, the first mortgage is refinanced, the deed is transferred, or the home is no longer the owner’s primary residence.
Before applying for down payment assistance in St. Augustine, compare the applicable income limit and purchase-price cap. Then ask a participating lender to assess your household income, occupation, and financing together. Homebuyer education may also be required.
St. Johns County homeownership and down payment assistance
St. Johns County and Florida programs offer different forms of assistance. Compare the eligible home, mortgage terms, and repayment rules before applying.
Available Assistance Programs
St. Augustine homebuyers can consider St. Johns County SHIP assistance, Florida Housing Bond programs, and Hometown Heroes. SHIP funds may cover down payment, closing costs, principal buy-down, and repairs needed for affordable homeownership. According to St. Johns County, its assistance is a 15-year deferred loan forgiven at 10% annually beginning in year 6. The home must be an owner-occupied single-family residence in the county.
The county’s certified property tax roll lists a median market value of $407,760. That figure offers local context, while each program’s purchase-price limit determines whether a home qualifies.
Participating Lenders and Loan Programs
SHIP applicants need approval for a first mortgage from a participating lender. The county considers preferred SHIP lenders annually at the start of its fiscal year on July 1. Lender participation matters because the first mortgage must meet program terms, including a fixed rate. Check that the lender can coordinate the assistance application with the mortgage approval and closing timeline.
The Housing Finance Authority of St. Johns County serves St. Augustine, St. Augustine Beach, Ponte Vedra, Hastings, and other county communities. Its service area also includes unincorporated areas. If you’re comparing county assistance with financing, review these down payment assistance options.
Funding Availability and Timing
SHIP funding is awarded on a first-qualified, first-served basis, so application readiness affects timing. St. Johns County helped about 45 people with down payment assistance in the past year. That number describes past assistance, not a promise of current funding or a fixed wait time.
Prepare your first-mortgage approval and application materials early. The county may combine SHIP purchase assistance with state or federal funds when assistance is needed and funds are available. Each funding source has its own eligibility and repayment terms, so compare the full package before moving toward closing.
Credit score and first-time buyer guidelines
St. Johns County SHIP defines a first-time homebuyer as someone who hasn’t owned a home during the three-year period before purchasing. You don’t necessarily need to have never owned property. For this county housing program, the timing of your previous ownership is the key test.
SHIP applicants must have a credit score of at least 640. Many Florida down payment assistance guidelines also reference a minimum score around 640. Before applying, review your credit reports for errors and check whether outstanding balances or missed payments need attention. A score is one part of the finance review, alongside income, debts, and mortgage qualification.
Employment history also matters. St. Johns County requires homeownership applicants to show at least two years of continuous satisfactory employment in the same field, including one year immediately before applying. Gather records that clearly show your work history and income. This can help the lender assess whether you meet the program’s employment and repayment criteria.
The county’s affordability worksheet uses a 29% housing ratio and a 41% total debt-to-income ratio. The first compares housing costs with gross monthly income; the second includes total monthly debt. These limits help determine whether the proposed payment fits your finances. St. Johns County homebuyer education certificates remain valid for one year, so plan the course and application timing together.
If your credit profile needs work before you apply, explore credit repair support as a step toward preparing for homeownership. Then compare your score, employment history, and debt ratios with the SHIP requirements before moving ahead.
Smart Home Loans: FHA Home Loans
Smart Home Loans offers FHA Home Loans for buyers considering FHA financing alongside down payment assistance. If your credit score, income, or available funds shape your plans, compare the assistance program’s requirements with the mortgage option you’re considering. The right fit depends on eligibility, property requirements, and loan terms.
Smart Home Loans also offers VA Loans, USDA Loans, and Jumbo Loans. These are distinct financing options, so your service eligibility, property location, and borrowing needs can help guide which one to explore. Discuss your assistance program details and homebuying goals to clarify the next step.
Contact Smart Home Loans to discuss which mortgage option may fit your home purchase.
Move Forward With a Clear Financing Plan
Your next step is turning eligibility into a workable homebuying plan. Set your target purchase, organize income and employment records, and compare assistance terms with the mortgage you’re considering. This can help you understand how the pieces fit before committing to a property or closing timeline.
For down payment assistance in St. Augustine, consider financing and assistance together. Smart Home Loans offers FHA Home Loans, VA Loans, and USDA Loans. Explore which option aligns with your homebuying goals and the program requirements you’ve reviewed.
Contact Smart Home Loans to discuss your financing options and next steps. A thoughtful start can make the path to homeownership feel more manageable.
Frequently Asked Questions
Can funds be used for repairs?
Yes. St. Johns County SHIP funds may help pay for repairs needed to make homeownership affordable. The assistance may also support purchase costs, but the repair work must relate to making homeownership affordable. The home must be an owner-occupied, single-family residence in St. Johns County. Include the repair need in your planning so it can be considered alongside the purchase and financing.
How do I get started?
Start by identifying the assistance program that fits your household and planned home. For SHIP, secure first-mortgage approval through a participating lender, then prepare your application and supporting income, employment, and credit information. Plan for homebuyer education as part of the process; the county’s certificate is valid for one year. Coordinating these steps can help you move from eligibility review toward a complete application.
Does St. Johns County offer down payment assistance, and what are the income and purchase price limits?
Yes. The applicable income ceiling depends on household size, so compare your household’s income with the relevant limit. Also distinguish the county’s SHIP rules from Florida Housing program limits, which have separate income and purchase-price caps.
What Florida state down payment assistance programs can St. Augustine homebuyers use, such as Florida Hometown Heroes?
It is a 0% deferred second mortgage with a 30-year term, and it isn’t forgivable. Eligibility includes qualifying full-time employees of Florida-based employers, with a listed servicemember category. In 2026, funds were reserved first come, first served through participating lenders.
What are the eligibility requirements for first-time homebuyer assistance in St. Augustine?
For St. Johns County SHIP, “first-time homebuyer” means you haven’t owned a home during the three-year period before purchasing. Applicants also need at least a 640 credit score and two years of continuous satisfactory employment in the same field, including the year immediately before applying. Homebuyer education is another planning step. Meeting the first-time buyer definition alone doesn’t replace the program’s other qualification criteria.