A polished promise to erase accurate debt isn’t proof of legitimate credit repair. Credit repair services in Saint Augustine, FL should follow Florida requirements: credit service organizations must maintain a $10,000 bond, consumers have a 5-day cancellation right for credit restoration agreements, and companies can’t charge upfront fees before services are rendered. These rules give you a practical starting point for judging your options.
It’s reasonable to want clear answers before trusting anyone with your credit concerns. This guide explains what Florida’s rules mean, how bureau disputes and creditor interventions work, and how long negative items may remain on your reports. You’ll also learn what credit repair services in Saint Augustine, FL can address, what they can’t change, and how to understand the next steps.
Key Takeaways
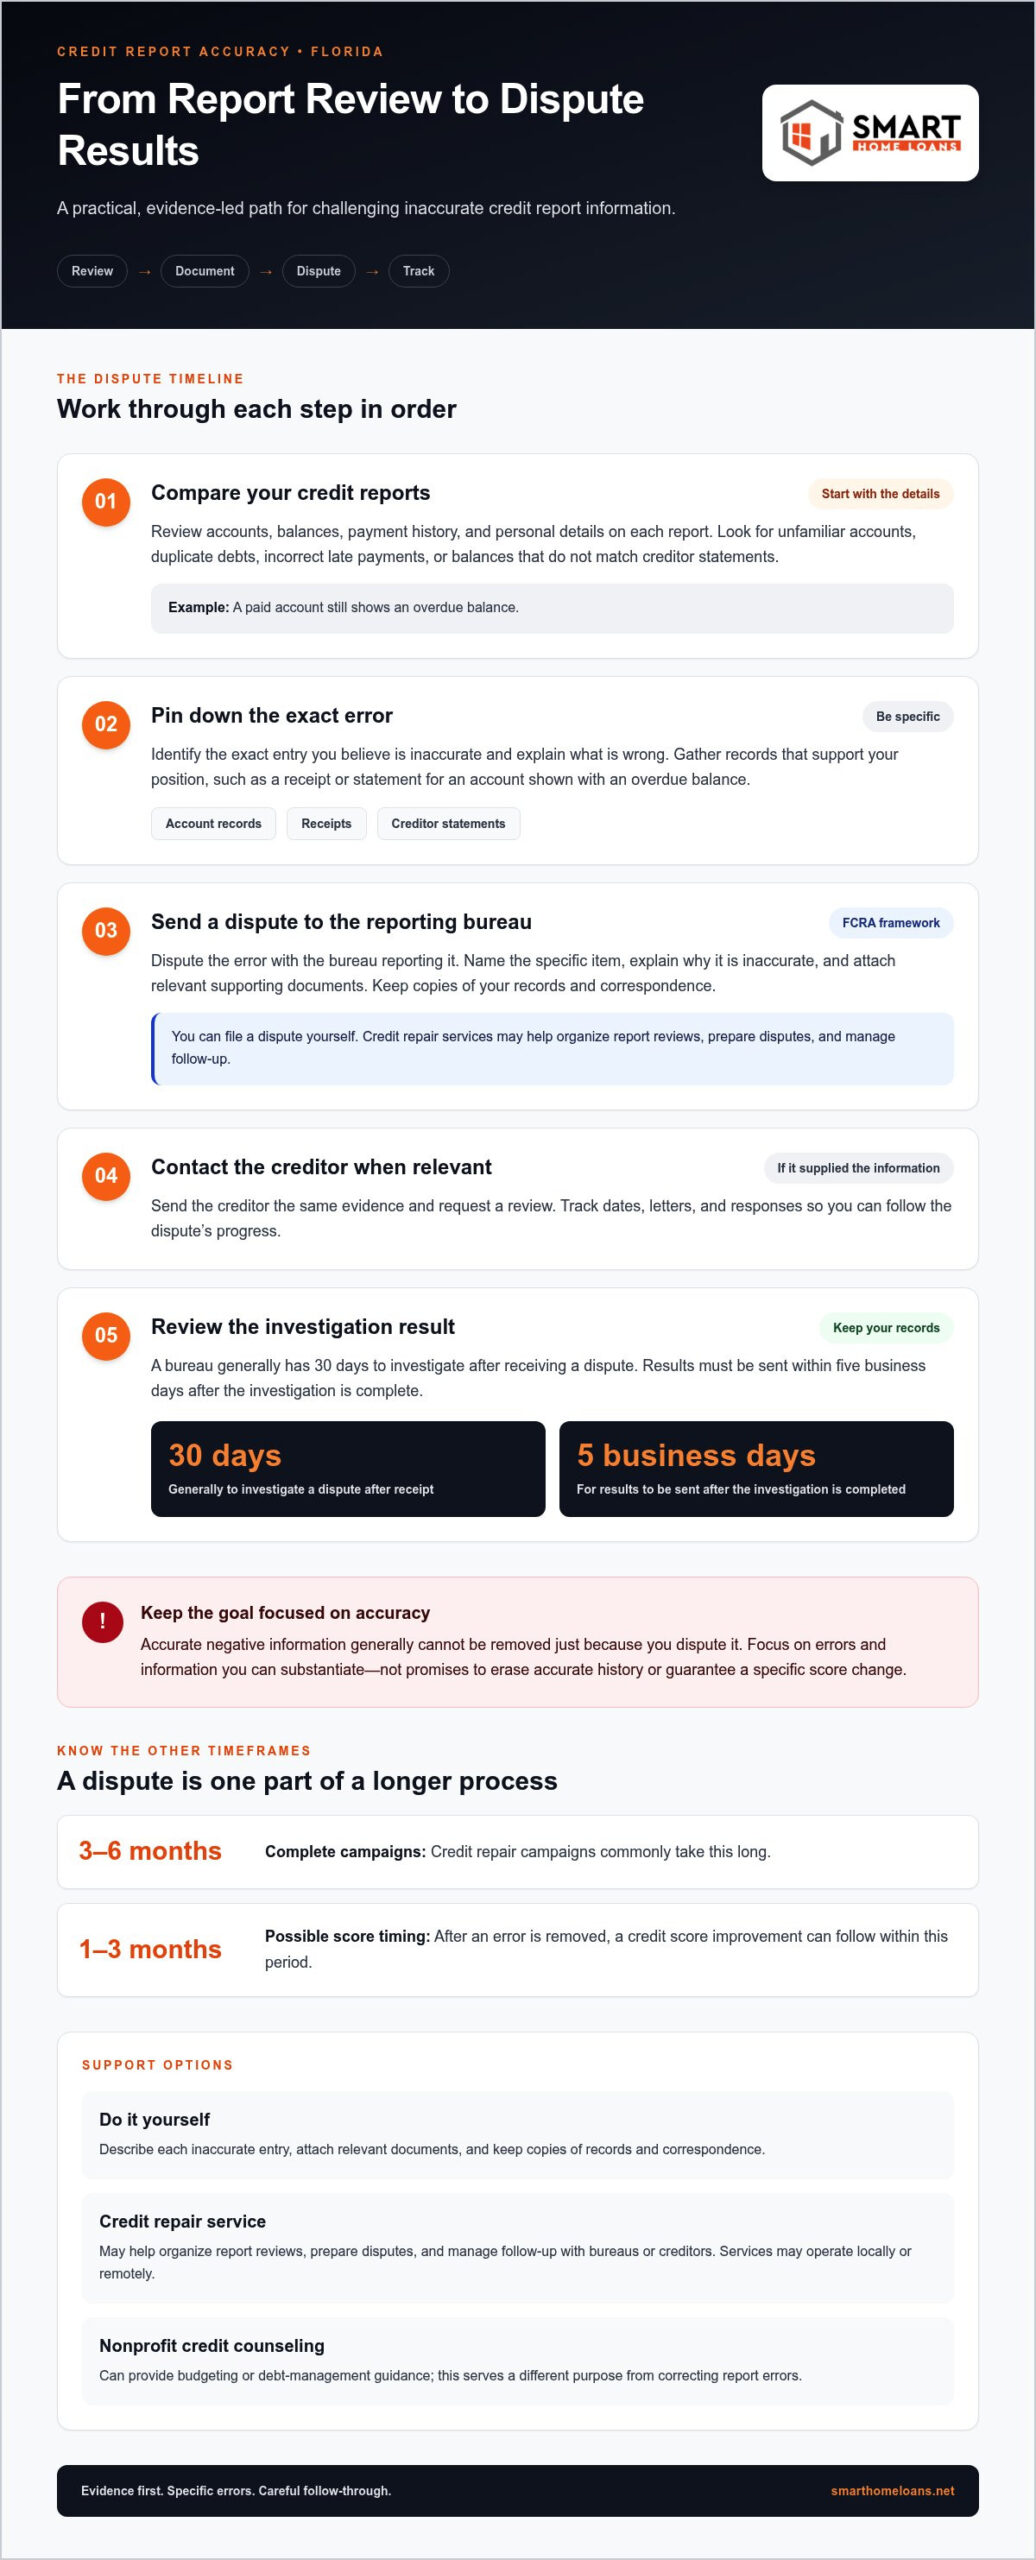
- Gather account records and identify the exact information you believe is wrong before filing a bureau dispute. Investigations generally take 30 days, with results sent within five business days of completion.
- Review negative entries for accuracy and reporting age. The Federal Trade Commission says most negative marks can remain on credit reports for seven years.
- Understand that accurate negative information generally can’t be removed just because you dispute it; focus on errors and records that can be substantiated.
- Use Florida’s consumer protections to assess a credit repair agreement, and be cautious of promises to erase accurate information or improve your score by a set amount.
Credit bureau disputes and creditor interventions
Start with the credit reports, then dispute specific inaccuracies with supporting records. Bureau investigations generally take 30 days, and results arrive within five business days after completion.
Reviewing Credit Reports for Errors
Compare the accounts, balances, payment history, and personal details on each report. Look for unfamiliar accounts, duplicate debts, incorrect late payments, or balances that don’t match creditor statements. For example, if a paid account still shows an overdue balance, gather the receipt or statement and identify the exact entry. Dispute errors with the bureau reporting them, and keep copies of your records and correspondence.
DIY Disputes and Repair Services
You can file disputes yourself by describing each inaccurate entry and attaching relevant documents. Credit repair services may help organize report reviews, prepare disputes, and manage follow-up with bureaus or creditors; complete campaigns commonly take 3 to 6 months. What credit repair companies serve Saint Augustine, FL? Services may operate locally or serve residents remotely. Which Saint Augustine services are locally based versus online? Local services may offer in-person interactions, while online services handle documents and communication digitally. Nonprofit credit counseling is also an option for Saint Augustine residents seeking budgeting or debt-management guidance, though it serves a different purpose from correcting report errors.
Disputes Under the FCRA
The Fair Credit Reporting Act (FCRA) provides the framework for disputing inaccurate information on credit reports. State the specific item you’re challenging, explain why it’s wrong, and include records that support your position. A bureau generally has 30 days to investigate a dispute after receiving it, then must send results within five business days of completing the investigation. If a creditor supplied the information, contact that creditor with the same evidence and request a review. Track dates, letters, and responses so you can follow the dispute’s progress.
How long do negative items stay on your credit report?
The Federal Trade Commission says most negative marks can remain on U.S. credit reports for seven years. Bankruptcies can remain for as long as 10 years. Check the date, account status, and payment history for each entry. An item’s presence doesn’t prove it’s accurate, so compare unfamiliar accounts and balances with your own records.
Medical debt has distinct reporting policies. Paid medical collections should not appear on consumer credit reports under nationwide reporting changes. The major credit bureaus’ voluntary policies exclude unpaid medical collections with an original balance below $500. If a medical account appears incorrectly, compare its balance and status with your billing documents, then dispute the specific error.
Reporting periods can also have exceptions. Credit bureaus may disclose older negative information when a job applicant seeks work paying more than $75,000 a year. They may also disclose it for loan or insurance applications worth more than $150,000. For rental applications, landlords in Historic Colonial Quarter and Anastasia Island look for credit scores of 640 or higher. These are screening considerations, not a promise of approval.
After an error is removed, a credit score improvement can follow within one to three months. Keep paying current accounts on time while reviewing updates, since payment history and accurate reporting both matter. If errors are affecting a home purchase plan, explore credit repair support as part of your next steps.
What makes credit repair legitimate in FL?
Florida credit service organizations must maintain a $10,000 bond and meet Florida Department of Agriculture and Consumer Services requirements. Before signing, read the agreement and identify the services, billing terms, and cancellation instructions. A credit repair company’s years of experience may offer context, but it doesn’t replace these basic compliance checks.
Florida consumers have a mandatory 5-day cancellation right for credit restoration agreements under Fla. Stat. § 817.702. Save a copy of the signed contract and note when you receive it, so you can track the cancellation period. If you cancel, follow the agreement’s stated process and keep proof of delivery. Review any billing terms carefully; credit repair services can’t charge upfront fees before services are rendered under the Florida Credit Service Organization Act and federal CROA standards.
How can you check reviews and complaints for local credit repair companies? Search the company name with terms such as “complaint” and “credit repair,” then read Better Business Bureau reviews and complaint responses. Look for repeated concerns about billing, missed follow-ups, or promises to remove accurate information, and compare those reports with the company’s written agreement.
Be cautious of guarantees about specific deletions or score changes. Legitimate work focuses on disputing inaccurate entries and explaining what each step addresses, not promising that accurate history will disappear. If you’re ready to discuss credit repair as part of your financial plans, explore credit repair options.
Smart Home Loans: FHA Home Loans
Smart Home Loans offers FHA Home Loans for readers preparing to turn credit progress into a home-buying plan. If you’re reviewing your credit profile and considering a purchase, discussing financing options can help clarify the next steps. Smart Home Loans also offers VA Loans, USDA Loans, and Jumbo Loans, giving borrowers different financing categories to explore.
Bring your current credit information and questions about your goals to the conversation. Knowing what appears on your reports can help frame a clearer discussion about financing, while reviewing your circumstances helps identify which loan category may fit. Credit improvements don’t replace the loan application process, but they can be part of preparing for it.
Contact Smart Home Loans to discuss FHA Home Loans and your financing plans.
Turn your credit work into a home-buying plan
Credit repair can be one part of preparing to buy a home. After reviewing your reports and identifying what needs attention, consider how your financing goals fit alongside your next credit steps. For credit repair services in Saint Augustine, FL, focus on accurate records and a realistic plan for moving forward.
Smart Home Loans offers FHA Home Loans, VA Loans, and USDA Loans. Exploring these options can connect your financial preparation with a possible path to homeownership. Start with your goals, your current credit picture, and the questions you want answered.
Contact Smart Home Loans today to discuss your financing plans. Take the next step at your pace, with a clearer picture of what comes next.
Frequently Asked Questions
How much do credit repair services in Saint Augustine typically cost?
The cost depends on the case and is given after a quote request. For credit repair services in Saint Augustine, FL, the work involved can affect the price, including reviewing reports, preparing disputes, and following up with creditors. Ask for an itemized explanation of the services and billing terms before agreeing. Don’t treat promised score increases or deletions as proof of value.
What services and packages do Saint Augustine credit repair companies offer?
Services may include reviewing credit reports, identifying possible inaccuracies, preparing bureau disputes, and communicating with creditors. The scope varies: one consumer may need help addressing a single account, while another may need several entries reviewed and tracked. Don’t assume a package includes every step. Compare the written service description with your specific needs before signing.
What Florida and federal laws regulate credit repair services?
Florida’s Credit Service Organization Act and federal CROA standards regulate credit repair practices. Florida credit service organizations must maintain a $10,000 bond and meet Florida Department of Agriculture and Consumer Services requirements. Both state and federal standards prohibit charging upfront fees before services are rendered. Read the agreement for the services covered, billing terms, and cancellation instructions before enrolling.
What are my rights under the Credit Repair Organizations Act?
Federal CROA standards protect consumers from upfront charges before credit repair services are rendered. In Florida, consumers also have a 5-day cancellation right for credit restoration agreements under Fla. Stat. § 817.702. Keep your signed agreement and a record of its delivery date. If you cancel, follow the contract’s written instructions and retain proof that you sent your notice.
How do I dispute inaccurate credit report items myself for free?
Get your credit reports from Equifax, Experian, and TransUnion through AnnualCreditReport.com, which currently provides free reports every week. Identify the exact entry and bureau reporting it, then submit a dispute explaining the error and include copies of supporting records. Save your submission and any response. If the same error appears on multiple reports, dispute it with each bureau reporting it.