When comparing Capital City Home Loans with a local broker in St. Augustine, focus on how each option fits the property, location, and financing you need, rather than the company name alone. The area spans distinct settings, from historic downtown to coastal Anastasia Island and suburban communities.
Consider both the home and the lender before deciding. A ZIP code is a useful starting point, but neighborhood character and property type matter too. This guide looks at St. Augustine areas and explains how to weigh those details when comparing mortgage options.
Key Takeaways
- Compare the property’s ZIP code and neighborhood setting to understand how location can shape your home search and financing needs.
- Look at lender coverage and broker networks to see how each option approaches local purchases.
- Match the loan program to your property and borrowing goals, rather than comparing lenders by name alone.
- Explore how FHA, VA, USDA, and Jumbo loan options may fit different buyer situations.
3. Does Capital City Home Loans serve borrowers in St. Augustine, Florida?
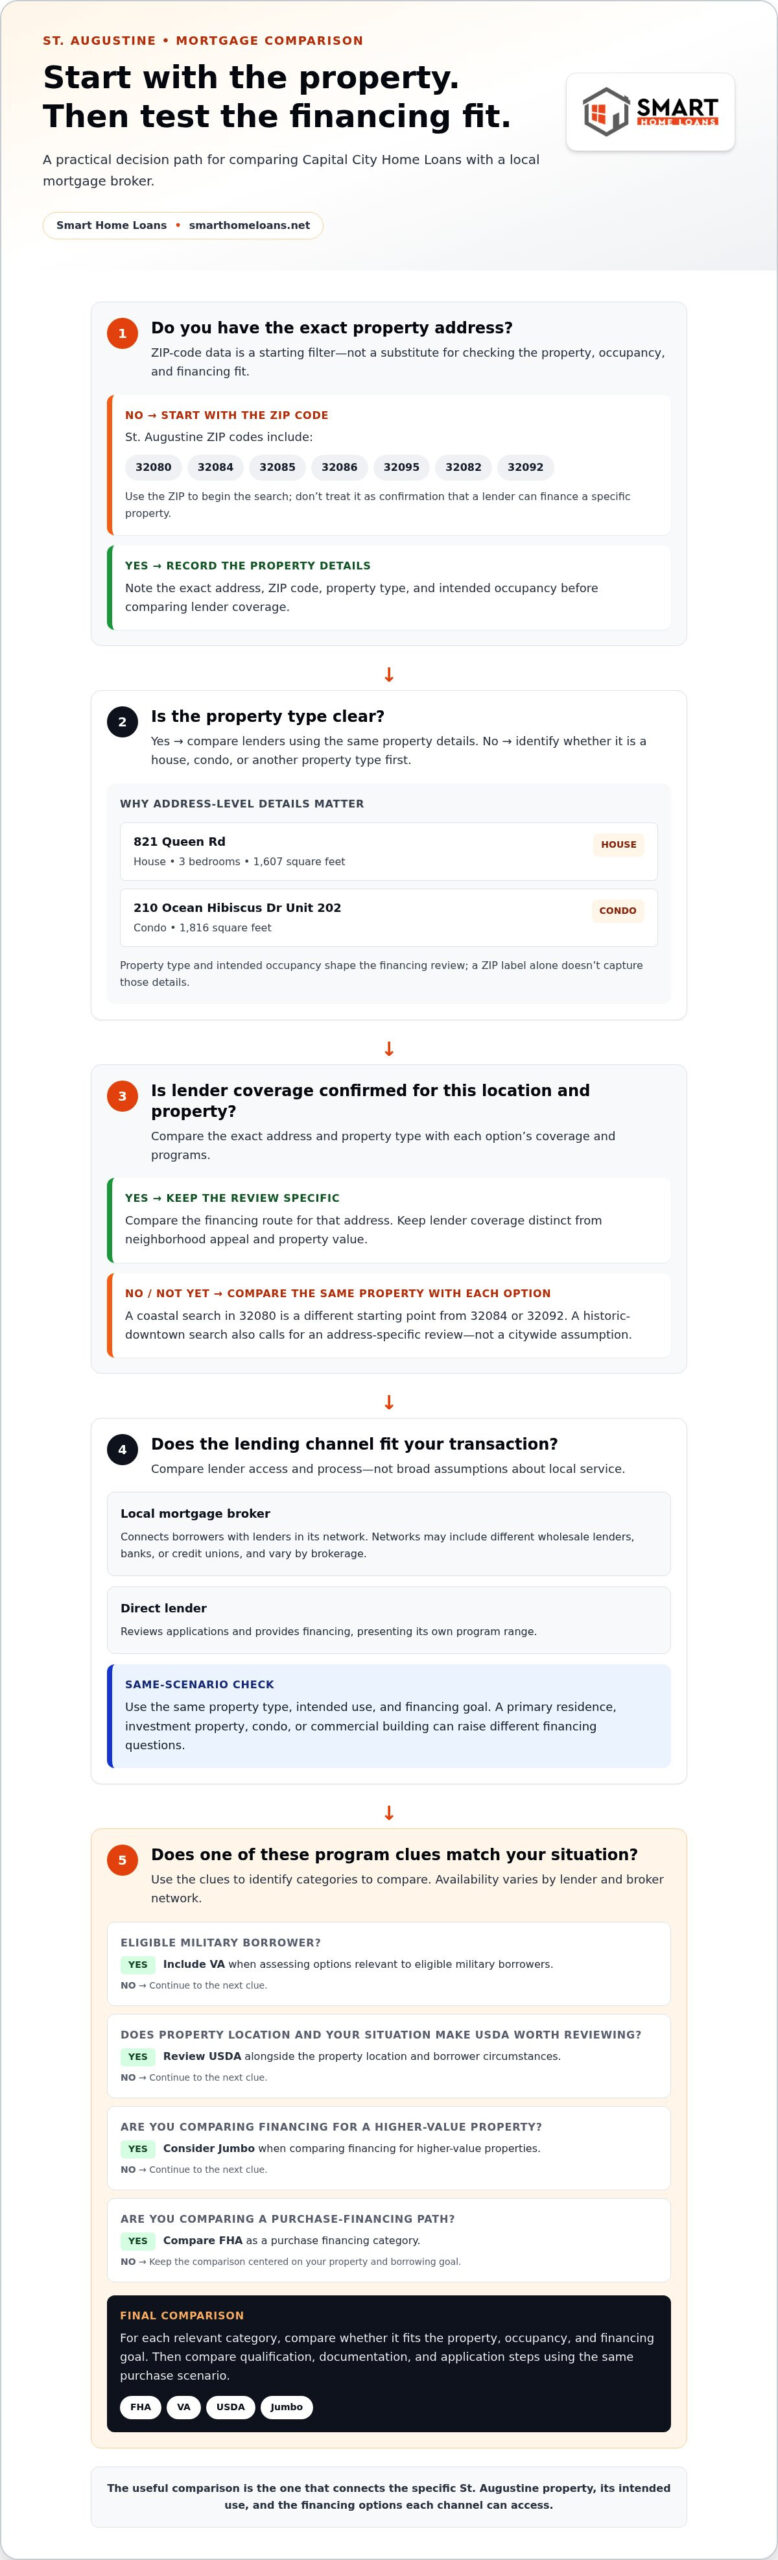
ZIP-code data alone cannot tell you whether a lender can finance a specific property. Compare the property’s exact address, ZIP code, occupancy, and type with the lender’s programs. St. Augustine includes different housing markets, so an address-level comparison is more useful than relying on the city name alone.
St. Augustine ZIP codes include 32080, 32084, 32085, 32086, 32095, 32082, and 32092. That spread makes ZIP code a useful first filter, not a substitute for assessing the specific property and financing fit.
Compare location and property type side by side. The house at 821 Queen Rd has three bedrooms and 1,607 square feet. The condo at 210 Ocean Hibiscus Dr Unit 202 has 1,816 square feet. These examples show why an address-level comparison should account for houses and condos, not just ZIP labels. Property details and intended occupancy shape the financing review.
Use a clear sequence: identify the property ZIP code, note its type, then compare lender coverage for that location. For a coastal search, 32080 offers a different starting point from 32084 or 32092. A search near historic downtown also calls for an address-specific review, rather than relying on citywide assumptions. Keep lender coverage distinct from neighborhood appeal and property value.
Check each property’s exact address and type against lender coverage.
3. Which local mortgage brokers serve St. Augustine and what lenders do they work with?
St. Augustine borrowers can compare local mortgage brokers by their lender networks and property experience. Each brokerage may work with different wholesale lenders, banks, or credit unions. A Capital City Home Loans vs local broker St. Augustine comparison should focus on what each financing channel can offer for your specific purchase, not assume all brokers have the same lender access.
A mortgage broker connects borrowers with lenders in its network, while a lender reviews applications and provides financing. Compare the lender types each option can access, then consider whether those channels fit your borrower profile and property. A condo near Anastasia Island, for example, may raise different financing questions than a commercial building in St. Augustine.
Use the same details in each comparison: property type, intended use, and financing goal. A second Capital City Home Loans vs local broker St. Augustine comparison can assess how each option handles a primary residence versus an investment or commercial property. This keeps the review focused on your transaction rather than broad claims about local service.
As you compare, note each brokerage’s lender categories and application process. For a St. Augustine purchase, connect those details to the address and property use. If you’re exploring financing paths, review mortgage financing options as part of your decision. A consistent comparison makes it easier to see which lending channel aligns with your needs.
Local brokers may work with different wholesale lenders, banks, or credit unions, and their lender networks vary. Compare each brokerage’s lender categories and application process against your property and financing needs.
3. What loan programs does Capital City Home Loans offer compared with local brokers?
Compare programs by borrower purpose and property type, not name alone. Four categories to review are FHA, VA, USDA, and Jumbo financing. Program access varies between lenders and broker networks. A local broker’s options depend on its lender relationships, while a direct lender presents its own program range. The useful question is which route fits the property and borrower.
Use the same comparison points for each program. Note whether it fits your property, occupancy, and financing goal. Then compare how each option explains qualification, documentation, and application steps. These details help you assess the process without assuming every broker offers identical programs.
- FHA: Compare this category when reviewing a purchase financing path.
- VA: Include it when assessing options relevant to eligible military borrowers.
- USDA: Review it alongside the property location and borrower circumstances.
- Jumbo: Consider it when comparing financing for higher-value properties.
For example, a home in ZIP code 32080 may call for a different financing review than one in 32084. The ZIP code does not select a program by itself. Property details, intended use, and borrower circumstances all inform the comparison. Ask how each option handles the same purchase scenario, then compare the answers side by side.
Keep the review practical: identify the program category that fits your needs, compare available options, and understand each application process. This gives you a clearer basis for weighing a large lender against a local broker. Review the program categories before deciding which route suits your St. Augustine purchase.
Compare FHA, VA, USDA, and Jumbo financing, but confirm which categories each option can access. A local broker’s range depends on its lender relationships, while a direct lender presents its own program range.
Smart Home Loans: FHA Home Loans
Smart Home Loans offers FHA Home Loans to borrowers comparing financing options in St. Augustine. It also offers VA Loans, USDA Loans, and Jumbo Loans, giving you several program categories to consider alongside your property type and borrowing goals.
Start by identifying the kind of financing you want to explore. Then compare the relevant program with your purchase plans and the property’s intended use. If you’re weighing an FHA option against another route, for example, focus on how each fits your circumstances and what the application involves. A clear comparison helps you prepare focused questions and understand your choices.
If you’re ready to discuss which program category may fit your plans, contact Smart Home Loans.
Choose a Financing Path That Fits Your Next Move
Turn a broad lender comparison into a focused conversation about your purchase. As you weigh Capital City Home Loans against a local broker in St. Augustine, consider what matters most: a suitable program, a property that fits your plans, or an application process you understand. Bring those priorities, along with the property details and intended use, to the discussion.
Smart Home Loans offers FHA Home Loans, VA Loans, and USDA Loans. Use these program categories to guide questions about your financing goals and identify which may be relevant to your situation. Contact Smart Home Loans to discuss your St. Augustine purchase and a practical next step.
Contact Smart Home Loans to discuss your financing needs. Take the next step with a clearer sense of what you want from your St. Augustine home search.