Finding a reliable mortgage broker in St. Augustine means looking beyond a name in a directory: the BBB directory displayed 1,282 mortgage broker results near Saint Augustine, Florida. A directory count alone doesn’t show how a broker works with borrowers. Look for clear explanations, responsive communication, and access to different loan options.
It’s understandable to want confidence before making a major financial decision. Customer feedback can show how borrowers describe their experience, while a broker’s lender access can influence the mortgage options they can present.
This guide explains what to look for when finding a reliable mortgage broker in St. Augustine, how to assess customer feedback, and how access to multiple lenders may help you compare loan options. You’ll also find practical questions to ask as you consider your next step.
Key Takeaways
- Use the broker’s listed St. Augustine address and contact details to understand how to connect locally.
- Read customer feedback for clues about communication, clarity, and support throughout the mortgage process.
- Understand how independent wholesale-lender access can provide different combinations of rates and points.
- Explore FHA, VA, USDA, and Jumbo loan options to see which financing path may fit your goals.
Branch location and contact information
Start with a verifiable local location and a clear way to identify the broker. Yvon Michael Acloque’s listed business address for Smart Home Loans is 125 King Street, Suite B, St. Augustine, Florida 32084. This gives you a specific St. Augustine reference point when assessing a broker’s local presence. It’s one practical detail to consider when finding a reliable mortgage broker in St. Augustine.
A directory can help show how broad the local search is. The Better Business Bureau directory displayed 1,282 mortgage broker results near Saint Augustine, Florida. Treat that count as a starting point, not a quality rating. Narrow your options by checking the broker’s name, address, and contact details together. Then note whether the information is consistent across the places where the broker is listed.
- Match the broker’s full name to the listed business address.
- Use the St. Augustine address to distinguish local listings from broader regional results.
- Keep contact details and the broker’s name together when arranging a purchase discussion.
St. Johns County’s population exceeds 264,000 people, and Flagler Health+, Publix Super Markets, and the St. Johns County School District collectively provide thousands of jobs. These local employment sources may shape a borrower’s income picture, while a lender evaluates the applicant’s income and financial obligations. Property taxes in St. Augustine can affect the ongoing cost of owning a home and the amount a borrower can comfortably carry. Ask how those costs fit into your purchase budget and whether down payment assistance could support your upfront plans.
In your first conversation, explain your purchase goals, income sources, and preferred area. Sharing these details helps the broker discuss relevant next steps and possible mortgage options. A suitable loan should fit your finances and the property you plan to buy.
Customer experiences with the broker
Customer reviews can show how clearly a broker explains financing, responds to questions, and provides updates. Look for specific examples, such as help resolving a document issue, rather than praise without detail. Compare several reviews and note recurring themes about communication and approval expectations.
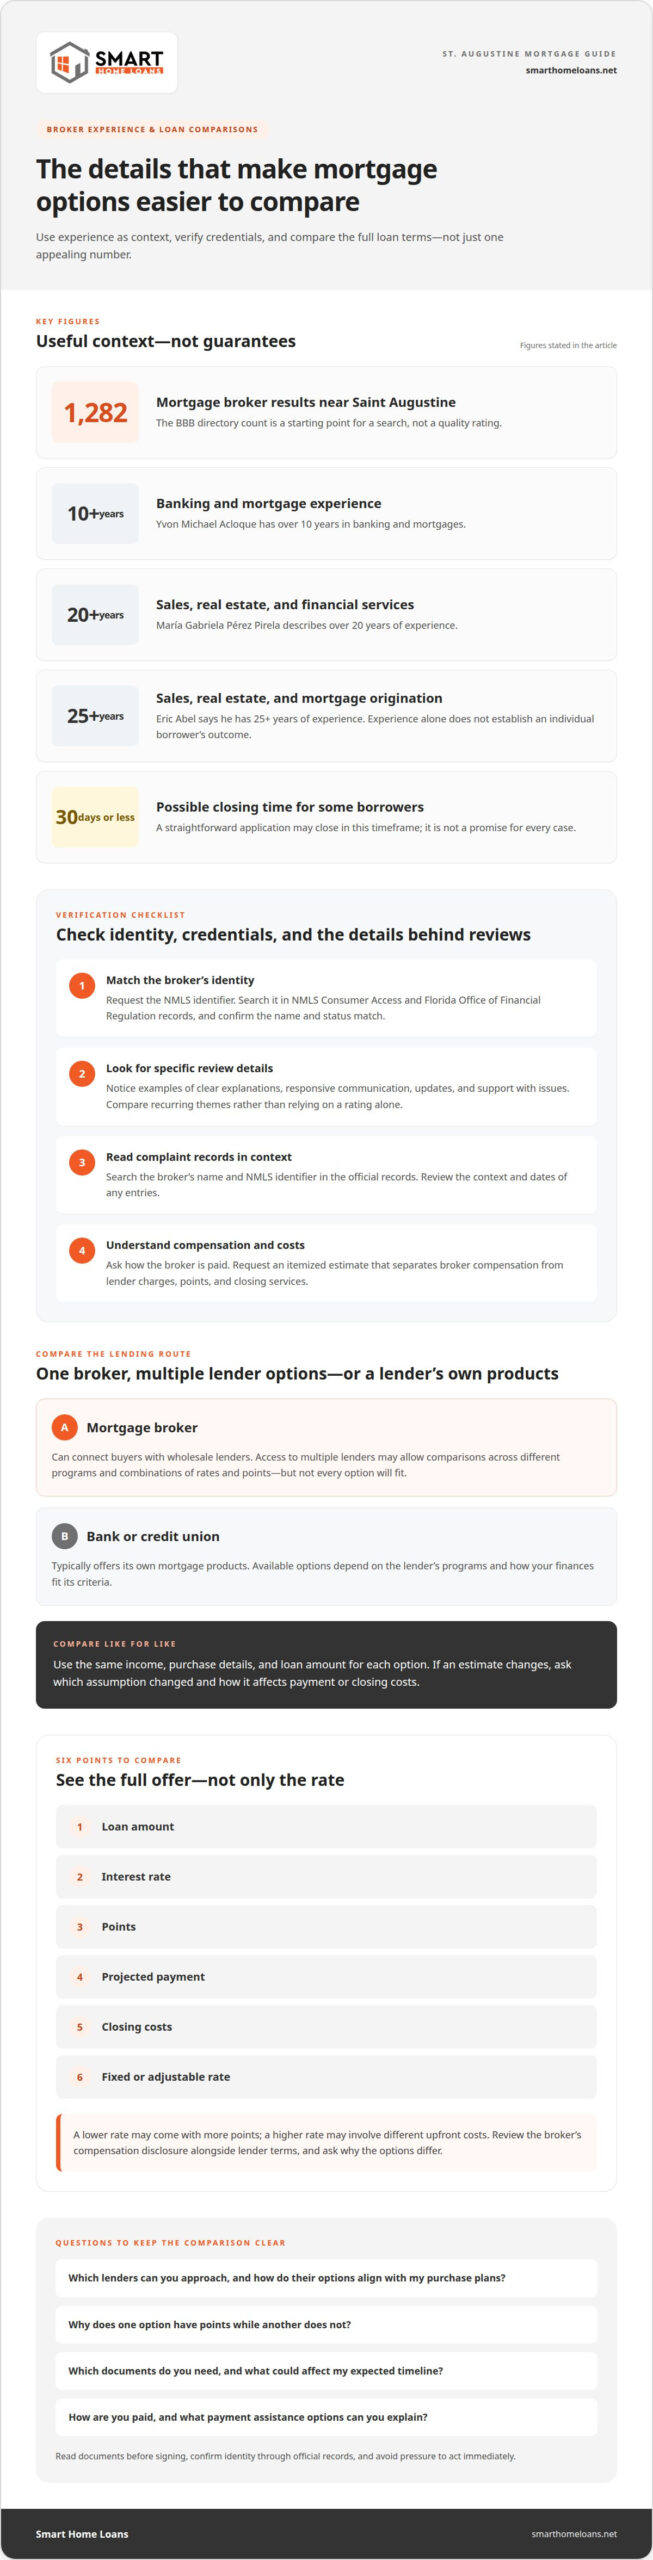
Verify a Florida mortgage broker’s credentials by requesting their NMLS identifier. Search the identifier in NMLS Consumer Access and Florida Office of Financial Regulation records, and confirm that the name and status match.
To review complaints or disciplinary history, search the broker’s name and NMLS identifier in NMLS Consumer Access and Florida Office of Financial Regulation records. Read the context and dates of any entries rather than relying on a rating alone.
Experience can help a broker explain loan steps. Yvon Michael Acloque has over 10 years in banking and mortgages; María Gabriela Pérez Pirela describes over 20 years in sales, real estate, and financial services. Treat experience as context, not proof of a particular customer outcome.
Fees and closing costs vary by loan and borrower. Loan type, points, lender charges, and closing services all affect the total. Ask for an itemized estimate that separates broker compensation from other costs.
Ask how the broker is paid, which lenders they can access, what documents they need, and how they’ll explain payment assistance options. Request a plain-language overview of the next approval steps.
Reduce scam risk by confirming identity through official records, reading documents before signing, and avoiding pressure to act immediately. For financing options, review mortgage financing assistance as you consider your next step.
Eric Abel says he has 25+ years of experience in sales, real estate, and mortgage origination, offering another experience point to weigh alongside the broker’s explanations. Experience alone does not establish what an individual borrower will experience.
Some borrowers can close a home purchase loan in as few as 30 days or less with a straightforward application, but that timing is not a promise for every case. Ask what could affect the expected timeline for your application.
Independent broker access to multiple wholesale lenders
A mortgage broker can connect buyers with wholesale lenders, while a bank or credit union typically offers its own mortgage products. The options depend on each lender’s programs and how your finances fit its criteria. Ask which lenders the broker can approach and how those options align with your purchase plans.
Access to multiple lenders can make comparisons more useful, but it doesn’t mean every option will fit. According to the Office of the Federal Register, National Archives and Records Administration, a broker’s contract should disclose that the broker can show borrowers other loans with different combinations of rates and points. Ask to review those alternatives in writing.
Compare loan estimates using matching terms. Check the loan amount, rate, points, projected payment, closing costs, and whether the rate is fixed or adjustable. A lower rate may come with more points, while a higher rate may involve different upfront costs. Focus on the costs and payment that fit your budget and planned timeline.
Ask for a plain-language explanation of differences between lenders. For example, ask why one option has points and another doesn’t, or whether a lender’s requirements affect the documents you need. Compare the full loan terms, not just one attractive figure, so you understand what each lender is offering before choosing financing.
Use the same income, purchase details, and loan amount when comparing options. If an estimate changes, ask which assumption changed and how that affects payment or closing costs. Review the broker’s compensation disclosure alongside the lender terms, so you understand how the broker is paid. To explore options for your plans, review mortgage financing choices.
Smart Home Loans
Smart Home Loans helps borrowers explore mortgage options that fit their financing needs. If you’re weighing FHA Home Loans, VA Loans, USDA Loans, or Jumbo Loans, it can help you understand which path may suit your situation. Share your purchase plans and questions, then discuss the options in straightforward terms.
When you’re ready to move from comparing brokers and lenders to reviewing possible loan paths, talk with Smart Home Loans. Buyers considering a government-backed option can discuss FHA, VA, or USDA financing, while buyers seeking Jumbo Loans can explore that route. The right fit depends on your goals, financial details, and property plans.
Contact Smart Home Loans to discuss your mortgage questions and next steps.
Take the Next Step With Confidence
Choosing a mortgage path is easier when you start with your priorities: the home you hope to buy, your financial goals, and the questions you still have. Finding a reliable mortgage broker in St. Augustine is about more than finding a nearby name. Look for clear explanations that help you make an informed decision.
Smart Home Loans offers FHA Home Loans, VA Loans, and USDA Loans. If one may fit your plans, discuss your goals and compare the available financing paths. A focused conversation can help you understand what to consider as you move forward, without pressure to decide before you’re ready.
Start a conversation with Smart Home Loans about your mortgage goals and next steps. Your home-buying plans deserve a thoughtful beginning.
Frequently Asked Questions
Which mortgage brokers in St. Augustine have strong recent customer reviews?
Smart Home Loans is a local option, and customer Brad Cregan praises Sean’s responsiveness, guidance through closing, and help securing a rate. Read the full context of any review, especially comments about communication and support, and consider whether those details match what you need during your mortgage process.
What fees and closing costs do mortgage brokers in St. Augustine charge?
Fees and closing costs vary by loan and borrower. Loan type, points, lender charges, and closing services all affect the total. Request an itemized estimate that separates broker compensation from other costs.