Start with the Florida Homeownership Loan Program and compare it with local assistance before you set your homebuying budget. St. Johns County’s SHIP program offers eligible buyers assistance awards of up to $100,000, according to St. Johns County.
It’s natural to focus first on the down payment, but each program has its own eligibility rules, loan structure, and buyer contribution requirements. Some assistance may be combined when program rules and funding allow; other options have different terms.
This guide explains how to get started, what to consider before combining assistance, and how to prepare for your required contribution and first-mortgage approval. It also outlines Florida’s Homeownership Loan Program to help you compare potential paths to buying with more clarity.
Key Takeaways
- Compare assistance programs’ terms before combining them, since eligibility and repayment rules can affect which options work together.
- Prepare for both the minimum buyer contribution and first-mortgage approval by reviewing your finances and credit early.
- Explore how Florida’s Homeownership Loan Program structures its second mortgage and whether its requirements fit your plans.
- Compare FHA, VA, USDA, and Jumbo loan options with Smart Home Loans as you consider a first mortgage.
Combining assistance with other down payment assistance programs
Before planning your closing, compare each program’s amount, repayment terms, and rules for combining funds. State and county assistance can support an affordable homeownership plan, but every option has its own requirements.
Assistance Amounts and Program Structures
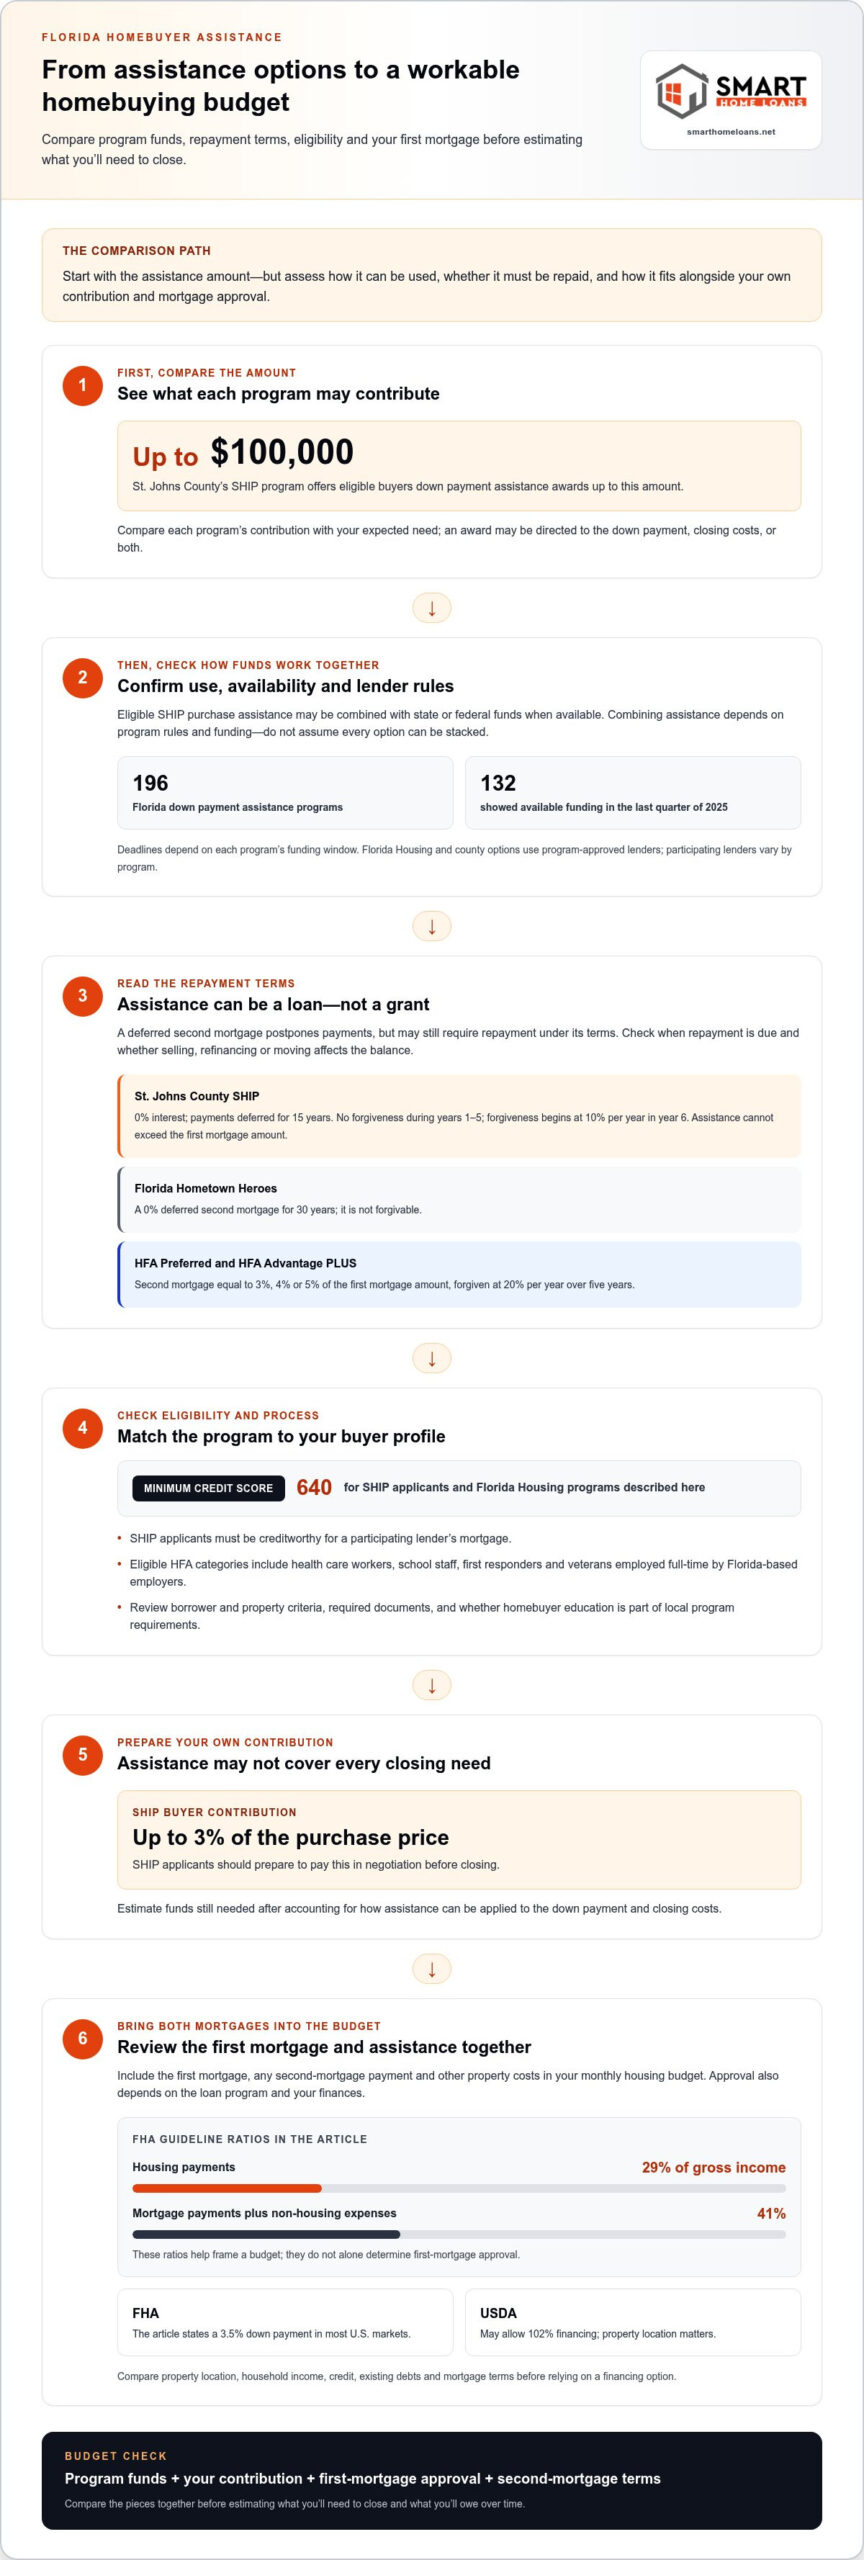
St. Johns County’s SHIP program offers down payment assistance awards of up to $100,000, according to St. Johns County. Eligible SHIP purchase assistance funds may be combined with state or federal funds when available. Compare the amount each program contributes with its use: down payment, closing costs, or both. That distinction helps borrowers estimate the funds still needed to close.
Assistance Types and Repayment Terms
Assistance may come as a grant, a deferred second mortgage, or a forgivable second mortgage. A deferred loan postpones payments, but it can still require repayment under its terms. Florida Hometown Heroes provides a 0% deferred second mortgage for 30 years; it is not forgivable. Before accepting any payment assistance, review when repayment is due and whether selling, refinancing, or moving affects the balance.
Florida Housing Assistance Options
Florida Housing programs described here require a minimum credit score of 640. HFA Preferred and HFA Advantage PLUS offer a second mortgage equal to 3%, 4%, or 5% of the first mortgage amount, forgiven at 20% per year over five years. Eligible categories include health care workers, school staff, first responders, and veterans employed full-time by Florida-based employers.
Funding, Deadlines, and Local Assistance
Florida had 196 down payment assistance programs, with 132 showing available funding in the last quarter of 2025. Application deadlines depend on each program’s funding window; there is no single deadline for St. Augustine programs. SHIP offers local down payment assistance, while participating lenders vary by program. Florida Housing and county options use program-approved lenders, so match the lender to the assistance option before starting an application. Homebuyer education may also be part of local program requirements.
Required buyer contribution and first-mortgage approval
Plan for your own contribution alongside assistance. SHIP applicants need a minimum credit score of 640, must be creditworthy for a participating lender’s mortgage, and should prepare to pay up to 3% of the purchase price in negotiation before closing.
Affordability also depends on monthly income, existing debts, and housing costs. FHA guidelines use 29% of gross income for housing payments and 41% for mortgage payments combined with non-housing expenses. These ratios help frame the budget, but first-mortgage approval also depends on the loan program and the borrower’s finances.
USDA financing may allow 102% financing, but property location matters. Check how the property, household income, and mortgage terms fit together before relying on a zero-down option.
For Florida Housing programs described here, the minimum credit score is 640. A credit score alone doesn’t determine approval, and SHIP applicants must also qualify for their first mortgage through a program lender. If your credit history needs attention, credit profile support can be part of preparing for that application.
Understand the SHIP second mortgage before accepting assistance. It carries 0% interest and is deferred for 15 years. Forgiveness begins at 10% per year in year 6, with no forgiveness during years 1 through 5. The assistance can’t exceed the first mortgage amount, so compare both balances and the repayment terms before closing.
Florida Homeownership Loan Program
Florida’s Homeownership Loan Program is one option among first-time home buyer programs in St. Augustine. Florida Housing’s Homebuyer Loan Program also offers eligible first-time buyers 30-year fixed-rate mortgages.
Look at the first mortgage and assistance together. A fixed-rate mortgage keeps its interest rate steady over the loan term, while assistance adds a separate second-mortgage obligation. Include that payment in your monthly housing budget alongside the first mortgage and other property costs.
As you compare first-time home buyer programs in St. Augustine, use these steps:
- Compare the first mortgage’s interest rate and payment with the second mortgage’s monthly obligation.
- Review how assistance can be applied to the down payment and closing costs.
- Ask participating lenders how the application handles both mortgages and which documents they need.
- Complete required homebuyer education and review borrower and property criteria.
Don’t assume assistance is a grant. A second mortgage is a separate loan, so understand its payment terms and how it fits your income and plans. Florida Housing and St. Johns County assistance may have different eligibility rules and funding processes. Comparing those terms can help you choose which first-time home buyer programs in St. Augustine fit your purchase.
Compare down payment assistance options alongside the first-mortgage choices available for your purchase.
Smart Home Loans: FHA Home Loans
Smart Home Loans can help you compare FHA Home Loans with your down payment and closing-cost plans. Consider its mortgage options as you weigh first-mortgage choices alongside assistance program requirements.
An FHA option may suit buyers considering a lower down payment. The research for this guide states that FHA loans allow a 3.5% down payment in most U.S. markets. Your overall plan still needs to account for credit, income, monthly payments, and any second-mortgage terms attached to assistance.
Smart Home Loans also offers VA Loans, USDA Loans, and Jumbo Loans. Each option serves different financing needs, so compare program criteria with the property and your budget before choosing a direction. A side-by-side review can help clarify how the first mortgage fits with local or Florida assistance.
For help weighing your mortgage options, contact Smart Home Loans.
Make Your Next Move With a Clear Plan
Your next step is to turn the options into a financing plan that fits your budget. List your available funds, expected monthly housing costs, and any assistance terms to account for. Then compare the first mortgage and assistance together, rather than as separate decisions. This can help you see which first time home buyer programs in St. Augustine align with your plans and what questions to resolve before applying.
Smart Home Loans offers FHA Home Loans, VA Loans, and USDA Loans. If you’re ready to discuss which mortgage direction may suit your purchase, contact Smart Home Loans. A thoughtful first conversation can help you take the next step with greater clarity and confidence.
Frequently Asked Questions
How do I get started?
Start by setting a purchase budget and gathering details about your income, savings, debts, and target property. Then identify which assistance rules match your situation and ask about the application sequence. For St. Johns County SHIP, complete the required homebuyer education and obtain a counselor certificate within 365 days of applying. Keep your documents organized as you compare options.
How much of a down payment do I need to buy a house in Florida?
The down payment can range from 0% to 20% of the home price, depending on the mortgage program. For example, FHA financing generally allows a 3.5% minimum down payment. Assistance may help cover eligible upfront expenses, but your cash needed also depends on the loan, property, closing costs, and program rules. Build your budget around the specific financing option you pursue.
What first-time home buyer programs are available in St. Augustine, Florida?
Options include St. Johns County SHIP assistance and Florida Housing programs, including the Homeownership Loan Program, Hometown Heroes, HFA Preferred, and HFA Advantage PLUS. Buyers can also explore FHA, VA, and USDA mortgage programs. These differ in eligibility, financing structure, and assistance terms, so compare property and borrower requirements before choosing a path.
What are the income and purchase price limits for St. Johns County homebuyer assistance?
SHIP assistance is available to eligible households with incomes up to 120% of area median income. The home’s purchase price cannot exceed 70% of the current SHIP Purchase Price Limit. Eligibility calculations include income from household members aged 18 or older who will live in the property. Applicants must also live or work in St. Johns County for 12 consecutive months.
How much down payment assistance is available in St. Augustine, and is it a grant or a loan?
St. Johns County’s SHIP program offers awards of up to $100,000, according to St. Johns County. Assistance may be structured as a grant or a second mortgage, so the award amount alone doesn’t tell you whether repayment applies. For example, Florida’s Homeownership Loan Program provides assistance through a second mortgage. Review each program’s repayment and forgiveness terms before budgeting.