Could a 3.5% down payment still leave you short at closing? Yes. If you’re exploring an FHA loan low down payment Florida option, remember that the minimum down payment is only one part of your upfront budget. Eligible borrowers with credit scores of 580 or higher may qualify for FHA’s 3.5% minimum, but closing costs and prepaid expenses add to the cash you’ll need.
Start by estimating the full cash to close, not just the down payment, then consider whether assistance could help cover some upfront costs. This guide explains how credit relates to FHA’s minimum, which other expenses to include, and how to explore Florida assistance options for Saint Augustine-area buyers. You’ll also learn what to review before relying on assistance and which details to gather for a borrower-specific estimate.
Key Takeaways
- Learn what an FHA loan low down payment Florida option may require, and why the minimum down payment isn’t the full amount you’ll need at closing.
- Build a clearer cash-to-close estimate by accounting for upfront expenses beyond the down payment.
- Use Florida Housing as a starting point to explore assistance, then review current eligibility, funding, lender rules, and repayment terms.
- Gather your income, savings, monthly debts, and likely purchase details to support a borrower-specific planning discussion with Smart Home Loans.
FHA loan low down payment in Florida: what the minimum does, and does not, cover
An FHA loan is a mortgage insured by the Federal Housing Administration and made by an FHA-approved lender. The insurance protects the lender, while qualified buyers may be able to put down less than with some other loan options. For background, see this overview of an FHA insured loan.
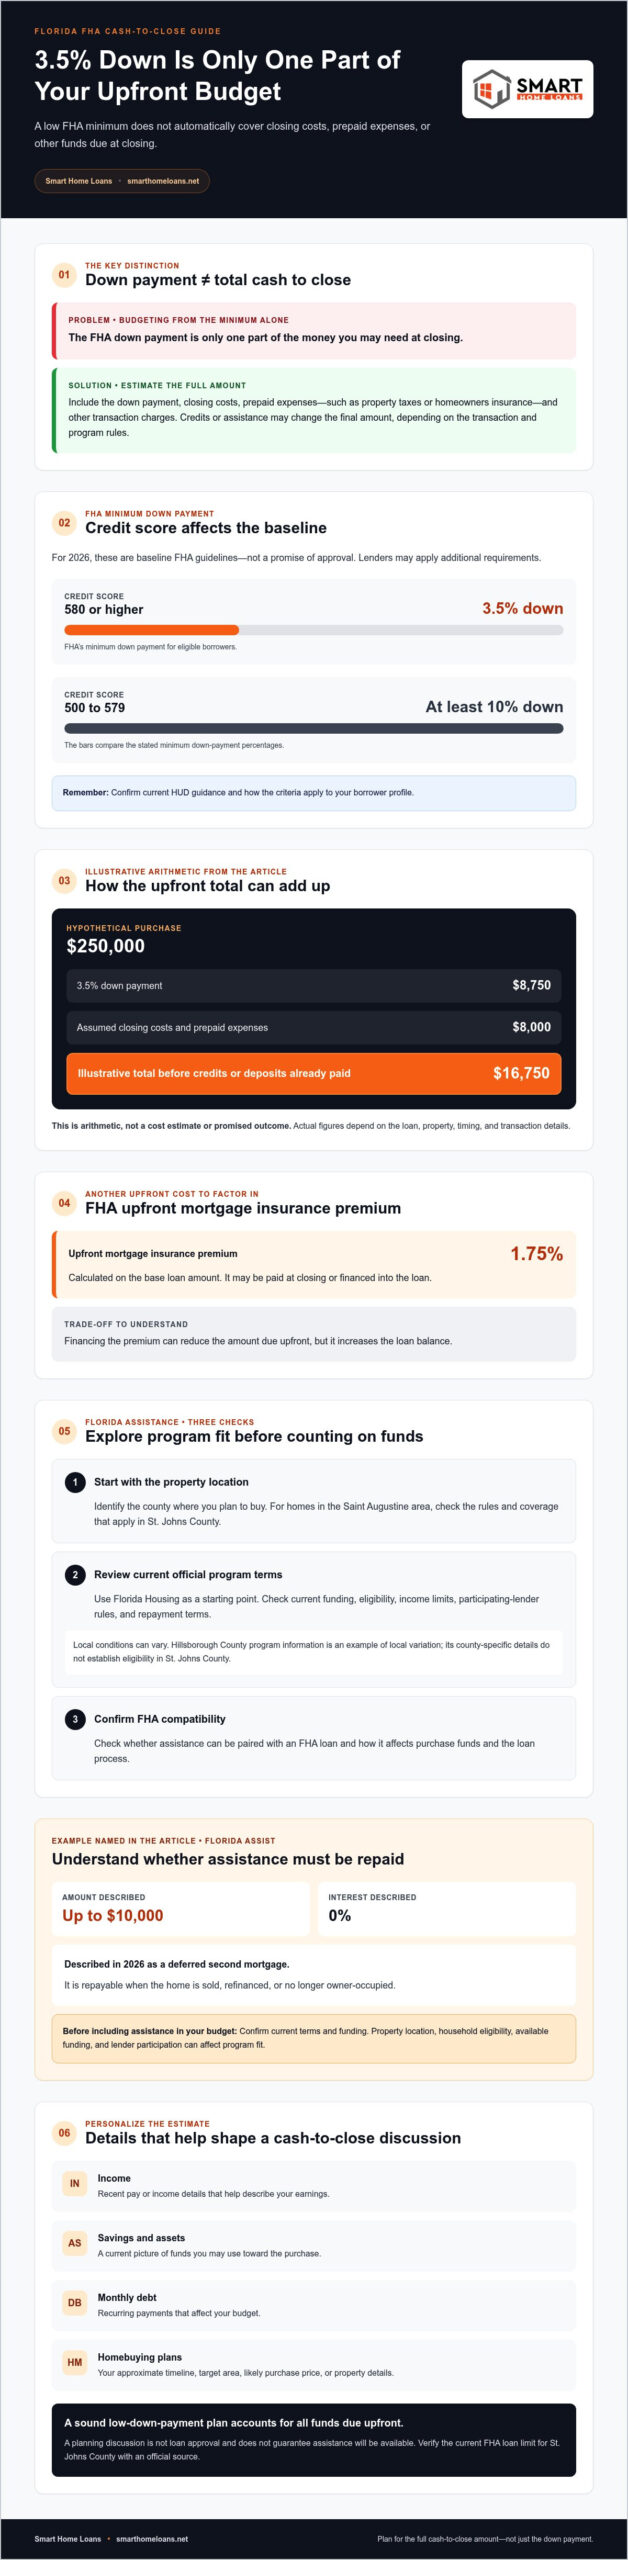
For 2026, the FHA minimum down payment is generally 3.5% for borrowers with credit scores of 580 or higher. Borrowers with scores from 500 to 579 may qualify with at least 10% down. These are baseline FHA guidelines, not a promise of approval, and lenders may apply additional requirements. Confirm current HUD guidance and review how the criteria apply to your borrower profile.
The minimum down payment is only one part of cash to close. Your estimate may also include closing costs, prepaid expenses such as property taxes or homeowners insurance, and other transaction charges. FHA’s upfront mortgage insurance premium is 1.75% of the base loan amount. It may be paid at closing or financed into the loan. Financing it can reduce the amount due upfront, but increases the loan balance.
Does a low FHA down payment mean buying with no money upfront?
No. A low minimum doesn’t automatically cover closing costs or other funds due at closing. Credits or assistance may change the final amount, depending on the transaction and program rules.
The down payment is one part of total cash to close, not the total itself.
Hypothetical example: Assume a $250,000 purchase, a borrower who qualifies for 3.5% down, and $8,000 in assumed closing costs and prepaid expenses. The down payment would be $8,750, making the illustrative total $16,750 before credits or deposits already paid. This is arithmetic, not a cost estimate or promised outcome. Actual figures depend on the loan, property, timing, and transaction details.
How Florida buyers can explore FHA down payment assistance
Assistance may help with upfront funds, but a program’s name alone doesn’t show whether it fits your purchase. For an FHA loan low down payment Florida plan, work through these steps before including assistance in your budget:
- Start with the property location. Identify the county where you plan to buy. For homes in the Saint Augustine area, check the rules and coverage that apply in St. Johns County.
- Review official program terms. Use Florida Housing as a starting point, then look for current funding, eligibility, income limits, participating-lender rules, and repayment terms. The Florida FHA down payment assistance programs information from Hillsborough County is a useful example of how local program conditions can vary. Its county-specific details don’t establish eligibility in St. Johns County.
- Assess FHA compatibility. Confirm whether the assistance can be paired with an FHA loan and understand how it affects the purchase funds and loan process. Smart Home Loans can review FHA financing and down payment assistance with you in light of your borrower qualifications.
What should Saint Augustine-area buyers check before counting on assistance?
First, find out whether assistance is a grant or a repayable loan. For example, Florida Assist is described in 2026 as a 0% deferred second mortgage of up to $10,000, repayable when the home is sold, refinanced, or no longer owner-occupied. Program funding and terms can change, so confirm the current details before including it in your budget.
Property location, household eligibility, available funding, and lender participation can all affect program fit. Also verify the current FHA loan limit for St. Johns County against an official source. If credit is a separate concern, review FHA loans with bad credit in Florida. Smart Home Loans offers FHA loans and down payment assistance. You can explore FHA loan guidance as you prepare your next steps.
Build a realistic Florida FHA cash-to-close plan with Smart Home Loans
A useful plan starts with your finances and the home you’re considering, not just a down payment percentage. Smart Home Loans can review FHA financing, potential assistance, and the factors that may shape your cash to close. That discussion can turn an FHA loan low down payment Florida goal into a clearer estimate and practical next steps.
What to bring to an FHA financing conversation
Gather recent income and asset information, a list of recurring debts, and an approximate homebuying timeline. If you have a target area, likely purchase price, or property details, bring those too. These details help shape a conversation around your circumstances. An initial discussion is for planning, not loan approval or a guarantee that assistance will be available.
- Income: Recent pay or income details that help describe your earnings.
- Savings and assets: A current picture of funds you may use toward the purchase.
- Monthly debt: Recurring payments that affect your budget.
- Homebuying plans: Your approximate timeline and likely purchase details.
Cash to close can include more than the down payment. Reviewing the Understanding Cash to Close for FHA Loans breakdown can help you see how closing costs and prepaid expenses fit into an estimate. Then, explore Florida’s mortgage process from pre-approval to closing to understand where budgeting fits into the broader process.
A sound low-down-payment plan accounts for all the funds due upfront. For a borrower-specific conversation about FHA financing and potential assistance, explore your options with Smart Home Loans.
Take your next step with a clearer plan
Your next move doesn’t need to be a commitment to buy. Start by comparing your goals with the funds you may have available, then identify what you need to prepare. A practical plan can help you decide which questions to resolve and what steps to take next.
If you’re considering an FHA loan low down payment Florida option, Smart Home Loans can discuss FHA financing and potential down payment assistance based on your circumstances. Sean manages the brokerage and holds NMLS ID 1734077. A conversation can help you identify a sensible next step, but it cannot guarantee loan approval or assistance.
Explore your Florida FHA loan options with Smart Home Loans and start building a clearer plan.
Frequently Asked Questions
Is the FHA minimum down payment the same for every Florida homebuyer?
No. The applicable minimum depends on current FHA rules and borrower qualifications, including credit-related criteria. Treat any quoted percentage as a starting point, then confirm current guidance and review how the requirements apply to your loan details. If you’re planning an FHA loan low down payment Florida purchase, also estimate closing costs and other funds that may be due.
Can I use down payment assistance with an FHA loan in Florida?
Possibly. Some assistance may work alongside FHA financing, but each program has its own conditions, and availability can change. For a home in Saint Augustine, check whether the property’s location is covered and whether the program’s lender and loan rules fit your FHA plan. Don’t include assistance in your budget until you understand how it will be provided and any repayment obligations.
Do I have to be a first-time buyer to get an FHA loan in Florida?
No. FHA financing isn’t limited to first-time buyers. Assistance is a separate question: a program may use its own definition of “first-time buyer” or set other eligibility conditions. For example, a repeat buyer might still explore FHA financing but find that a particular assistance option has a different test. Review the FHA requirements and assistance rules separately before deciding what may fit.
Can gift funds help cover an FHA down payment?
They may, if the gift and its documentation meet current FHA requirements. A family member’s transfer, for example, shouldn’t be assumed eligible simply because the funds are available. Keep records showing where the money came from, and understand what documentation may be needed before moving funds. Smart Home Loans can explain how acceptable gift funds affect your cash-to-close estimate.