If you’re asking how to get pre-approved for a mortgage, it’s understandable to want clear answers before sharing financial details or agreeing to a credit check. A pre-approval may help you make an offer, but it is not a promise of financing. Preparing a few key details can make the process more manageable.
This checklist covers information lenders commonly request, questions to ask when comparing loan options, and what to clarify about credit inquiries. You’ll also see how prequalification, pre-approval, and final approval differ. Use a pre-approval letter as a planning tool, not a final decision. For a home purchase in Saint Augustine, the specific property and your current financial details will still need review.
Key Takeaways
- Learn how to get pre-approved for a mortgage by organizing key financial details before speaking with lenders.
- Compare lenders by how clearly they explain loan options, documentation, assumptions, and conditions.
- Understand the differences between prequalification, pre-approval, and final underwriting before relying on a lender’s assessment.
- Keep your lender informed of important financial changes and ask when your pre-approval needs updating.
Mortgage Pre-Approval: Your Financial Checklist
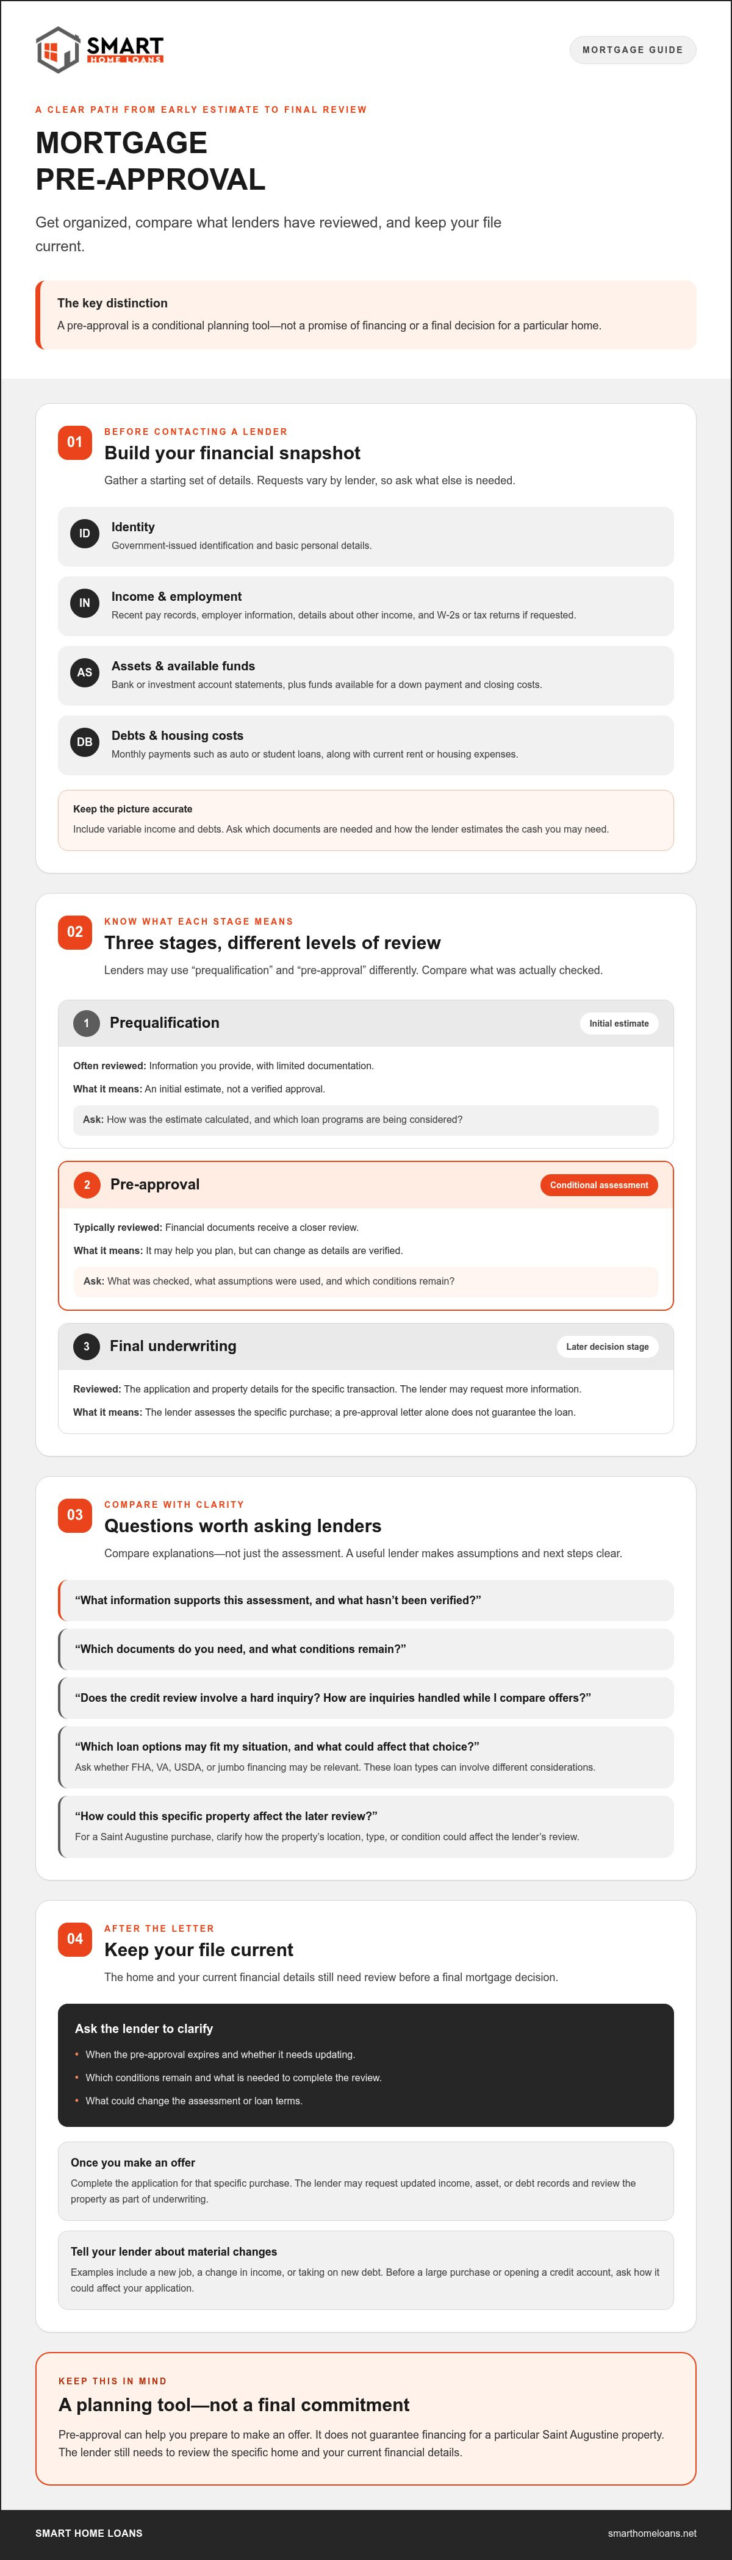
Before your first lender conversation, gather a snapshot of your finances and ask what else is needed. Pre-approval is conditional: it is an early assessment, not a promise that a loan will be approved or that a particular property will qualify.
What should you gather before contacting a mortgage lender?
To understand how to get pre-approved for a mortgage, start by organizing details a lender may use to review your application. Document requests vary, so use this as a starting point rather than a fixed checklist:
- Identity: Government-issued identification and basic personal details.
- Income and employment: Recent pay records, W-2s or tax returns if requested, employer information, and details about other income.
- Assets: Bank or investment account statements and information about funds available for a down payment and closing costs.
- Debts and housing costs: Monthly debt payments, such as auto or student loans, plus current rent or housing expenses.
Be accurate and include details about variable income and debts. Ask which loan options may fit your situation, which documents are needed, and how the lender estimates the cash you may need. FHA, VA, USDA, and jumbo loans can involve different considerations. Ask the lender to explain the assumptions relevant to your application rather than relying on a general estimate.
Before authorizing a credit review, ask whether it involves a hard inquiry and how the lender handles inquiries if you’re comparing offers. For a neutral overview of the term and its role in buying a home, read this explanation of mortgage pre-approval. Understanding what the lender has reviewed will make it easier to compare assessments.
Compare Mortgage Pre-Approval Options Without Confusing It With Final Approval
Lenders may use “prequalification” and “pre-approval” differently. Compare what each lender actually reviewed, what remains uncertain, and how clearly they explain the next steps. Even a pre-approval based on reviewed documents is not final underwriting or a guarantee of financing for a specific property.
| Stage | What’s reviewed and discussed | What it means |
|---|---|---|
| Prequalification | Often based on information you provide, with limited documentation. Ask how the estimate was calculated and which loan programs are being considered. | An initial estimate, not a verified approval. |
| Pre-approval | Typically includes a closer review of financial documents. A useful lender explains what was checked, what assumptions were used, and what conditions remain. | A conditional assessment that may help you plan, but can change as details are verified. |
| Final underwriting | The lender reviews the application and property details for the specific transaction, and may request additional information. | The later decision stage. A pre-approval letter alone doesn’t guarantee the loan. |
What questions help you compare lenders and loan programs?
Ask, “What information supports this assessment, and what hasn’t been verified?” Then compare how clearly lenders explain documentation, conditions, communication, and available loan options. If relevant, ask whether FHA, VA, USDA, or jumbo financing may fit your circumstances, and what factors could affect that choice.
For a Saint Augustine purchase, ask how the property’s location, type, or condition could affect the lender’s later review. Clarify what depends on the specific property so you don’t treat a pre-approval as a decision that applies to any home.
To discuss your circumstances and possible loan options, visit Smart Home Loans.
After Mortgage Pre-Approval: Keep Your File Current and Know Your Next Steps
A pre-approval letter comes with conditions. Ask when it expires, whether it needs updating, and what could change the assessment. It does not guarantee financing for a particular Saint Augustine property. The home and your current financial details still need review.
What happens between pre-approval and a final mortgage decision?
After you make an offer, you’ll complete the application for that specific purchase. Your lender may request updated income, asset, or debt records and review the property as part of the process. Underwriting checks your application against the lender’s requirements, and property-related findings may affect the decision or loan terms.
Keep your lender informed of material changes, such as a new job, a change in income, or taking on new debt. Before making a large purchase or opening a credit account, ask how it could affect your application. A change does not automatically mean a problem, but the lender needs accurate information to reassess your file.
As you learn how to get pre-approved for a mortgage, remember that the letter is a starting point, not a final commitment. Ask which conditions remain and what the lender needs to complete the review. If you’re considering an FHA or another government-backed loan, confirm how that program’s requirements apply to your application. A Florida mortgage process guide or program-specific loan guide can help you prepare, while your lender can explain how the details apply to your purchase.
For help understanding the next steps, talk through your pre-approval questions with Smart Home Loans.
Take the Next Step With a Clearer Plan
Knowing how to get pre-approved for a mortgage starts with organizing your finances, asking clear questions, and understanding what a lender’s review does and doesn’t confirm. A pre-approval can help you plan, but it remains conditional. Keep your information current and check with your lender before relying on the letter for a specific property.
Smart Home Loans is managed by Sean, NMLS ID 1734077. The brokerage offers FHA, VA, USDA, and jumbo options to explore based on your circumstances. Credit repair and down payment assistance are also listed services. Ask about their availability and terms, and confirm current NMLS status and applicable licensing details when discussing your options.
Ready to discuss your mortgage pre-approval and possible loan options in Saint Augustine? Talk with Smart Home Loans about your next step.
Frequently Asked Questions
How long does it take to get pre-approved for a mortgage?
Timing varies by lender and by how quickly you provide complete information. If you’re planning how to get pre-approved for a mortgage, gather requested records and ask which review steps remain and when to expect an update. Treat any time estimate as a guide, not a guaranteed deadline. A lender may need more time if documents are unclear or require additional verification.
Does getting pre-approved for a mortgage hurt your credit?
A lender may review your credit during pre-approval. The effect depends on how the inquiry is handled and your credit profile. Before authorizing a review, ask whether it involves a hard inquiry and how the lender will use it. Don’t assume every lender follows the same process or that the impact will be identical for every borrower.
Is mortgage pre-approval a guarantee that I will get a loan?
No. Pre-approval is an early assessment based on the information available at that point, not a final lending decision. The lender may still verify your documents, review the property, and assess updated financial details. Ask which conditions remain and what changes you should report before closing. For a Saint Augustine purchase, confirm how the specific property will be reviewed.
Can I get pre-approved for a mortgage with a credit setback?
A credit setback doesn’t automatically determine whether you can qualify. Lenders consider the full application and the requirements of the loan program being reviewed. Ask a mortgage professional to discuss your situation and possible next steps. Smart Home Loans lists credit repair among its services, but that doesn’t guarantee results or loan eligibility. Saint Augustine borrowers can ask what may apply to their circumstances.
Pingback: Florida Mortgage Process: Steps from Pre-Approval to Closing