The FHA loan limit isn’t the maximum price of a home you can buy. It sets a ceiling on the FHA-insured loan amount, so your down payment affects how the limit fits your budget. If you’re checking FHA loan limits St. Johns County, make sure you use the figure for the property’s number of units.
It’s useful to know the county limit before you start planning, but that figure alone doesn’t determine whether you’ll qualify for an FHA loan. Your finances and the property matter, too.
This guide explains how to find the official 2026 St. Johns County limit, how it relates to a home’s purchase price, and what to review next. A mortgage professional can help you understand how the limit applies to your situation and whether another loan type may be worth discussing.
Key Takeaways
- Check HUD’s official FHA loan limits for St. Johns County and match the figure to the property’s unit count.
- The FHA limit applies to the base loan amount, not the home’s purchase price. Your down payment helps determine how the two relate.
- The county limit doesn’t guarantee approval. Credit, income, debts, assets, and lender review also matter.
- Gather your financial and property details before speaking with a mortgage professional so you can discuss your budget and next steps.
What Is the 2026 FHA Loan Limit in St. Johns County?
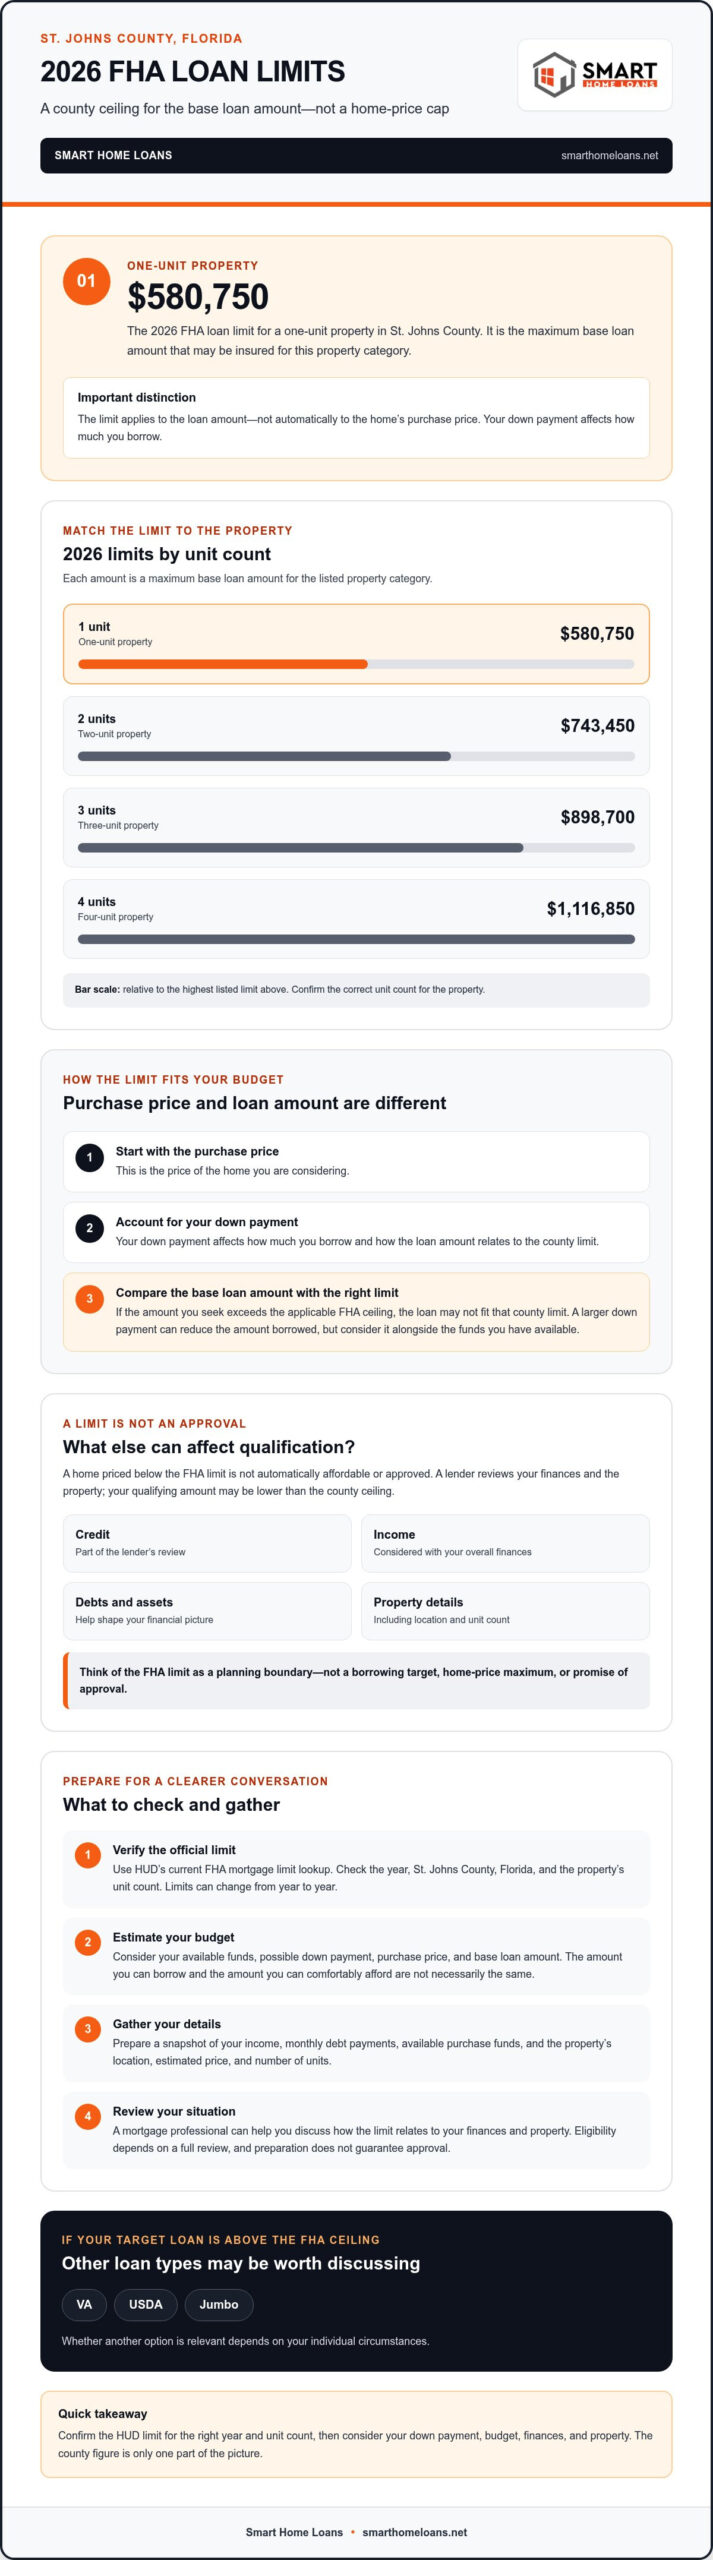
The 2026 FHA loan limit for a one-unit property in St. Johns County is $580,750. Before using this figure, confirm the year, county, and property category in HUD’s current county limit lookup. FHA limits can change from year to year, and the applicable amount depends on the number of units in the property.
In plain English: HUD’s 2026 FHA loan limit for a one-unit property in St. Johns County is the maximum base loan amount that may be insured under the FHA program for that category. The FHA insured loan program provides background on how FHA insurance works.
The limit applies to the loan amount, not automatically to the home’s purchase price. Your down payment affects how much you borrow, while your approved amount depends on a lender’s review of your finances and the property. The county limit is a planning boundary, not a promise of approval or a maximum home price.
Where to verify the St. Johns County FHA limit
Use HUD’s current FHA mortgage limit lookup and check that it shows 2026, St. Johns County, Florida, and the correct unit count. The listed 2026 limits are $580,750 for one unit, $743,450 for two, $898,700 for three, and $1,116,850 for four. Match the unit count to the property you’re considering before making plans.
For a quick reference, HUD lists a 2026 FHA loan limit of $580,750 for a one-unit property in St. Johns County. Checking the official entry helps you avoid relying on a figure for a different year or property type.
How the St. Johns County FHA Limit Affects Your Homebuying Budget
The county limit is one part of your budget, not a home-shopping price target. Your purchase price and down payment help determine the base loan amount you’re seeking. If that amount exceeds the applicable FHA limit, the loan may not fit the FHA program’s county ceiling. A larger down payment can reduce the amount borrowed, but consider that alongside the funds you have available for the purchase.
A home priced below the limit isn’t automatically affordable or approved. Your budget also needs to account for your income, debts, assets, credit, and other costs of owning the home. The Consumer Financial Protection Bureau explains FHA loan features, including down payment considerations and mortgage insurance, to help you understand the broader picture.
Does the FHA limit determine how much you can borrow?
No. FHA loan limits in St. Johns County set the maximum base loan amount for the relevant property category. Your personal qualifying amount may be lower, depending on the lender’s review of your finances, the property, and your down payment. Treat the limit as a boundary to check, not a borrowing target or approval decision.
For a clearer estimate, gather details about your income, monthly debts, available assets, and the property you’re considering. A mortgage professional can help you review how those details relate to the FHA limit without assuming you’ll qualify. To discuss your FHA loan options, you can connect with Smart Home Loans. If your target loan amount is above the applicable FHA limit, ask whether another option, such as a VA, USDA, or jumbo loan, may be relevant to your situation.
Next Steps for St. Johns County Buyers Checking FHA Loan Limits
Use the FHA loan limits in St. Johns County as a starting point, then build a fuller picture of what may work for you. These steps can make your next mortgage conversation more focused:
- Confirm the current limit. Use HUD’s FHA Loan Limit Lookup Tool and select the right year, county, and property unit count.
- Estimate your budget. Consider your available funds, possible down payment, and the purchase price you’re exploring. The base loan amount and the amount you can comfortably afford aren’t necessarily the same.
- Review your situation with a mortgage professional. Eligibility depends on a full review, not the county limit alone.
What to prepare before discussing an FHA loan
Gather a clear snapshot of your finances and the property you’re considering. Useful details include:
- Income and monthly debt payments
- Available funds for the purchase
- Property location, estimated price, and number of units
For more preparation tips, look for 2026 Mortgage Pre-Approval: A Practical Checklist. Having these details ready can make the discussion more specific, though it doesn’t guarantee approval.
If your target loan amount may exceed the applicable FHA ceiling, ask about alternatives such as VA, USDA, or jumbo loans. The right fit depends on your individual circumstances. Saint Augustine-area buyers can discuss their options with Smart Home Loans after checking HUD’s official limit.
Take the Next Step Toward a Clearer FHA Plan
The FHA loan limits in St. Johns County give you a county-specific borrowing boundary, not a home-price target or a guarantee of approval. Check HUD’s current limit for the property’s unit count, then consider how your down payment, income, debts, assets, and the property itself shape your budget and eligibility.
Smart Home Loans offers FHA home loans and serves Saint Augustine. If your target loan amount may exceed the applicable FHA ceiling, the brokerage also offers other mortgage options, including VA, USDA, and jumbo loans, to discuss based on your circumstances.
Talk with Smart Home Loans about your FHA options. A conversation can help you understand what to check next and move forward with greater clarity.
Frequently Asked Questions
Is the FHA loan limit the same as the maximum home price?
No. The limit applies to the maximum base loan amount insured for the applicable county and property category, not the home’s purchase price. A buyer may purchase a home priced above the limit if a larger down payment keeps the base loan amount within the applicable ceiling. Make sure the down payment also fits your overall budget.
Does meeting the St. Johns County FHA loan limit mean I qualify?
No. The county limit sets a program ceiling; it doesn’t confirm that you’ll be approved or that the loan is affordable for you. A lender reviews factors such as your credit, income, debts, assets, and property details. Ask a mortgage professional to assess your individual situation and explain what may affect your eligibility.
What can I do if the home I want would require a loan above the FHA limit?
First, consider whether your down payment could bring the base loan amount within the FHA ceiling without stretching your budget. If not, ask a mortgage professional about other possibilities. Smart Home Loans serves Saint Augustine and offers VA, USDA, and jumbo loans. These options aren’t right for everyone, so discuss your circumstances and eligibility before deciding.
Pingback: Florida Mortgage Process: Steps from Pre-Approval to Closing