Could a home fit your budget and still fall short of FHA approval? The FHA loan requirements St. Augustine FL buyers need to review involve more than credit and cash to close. Your income, monthly debts, the property’s condition, and the St. Johns County loan limit all matter. Before making an offer, it helps to understand where you stand, especially because an FHA appraisal does not confirm that a home is move-in ready.
Use this checklist to review likely eligibility and identify details that depend on your loan file or the property. For 2026, the FHA limit for a one-unit property in St. Johns County is $580,750. The sections below cover credit and down payment guidance, income and debts, local property standards, and the records to gather before applying. Smart Home Loans offers FHA home loans and can help you review your options.
Key Takeaways
- Use the FHA loan requirements St. Augustine FL checklist to review credit, documented income, employment history, debts, available funds, and owner-occupancy plans before you shop.
- Separate FHA program guidelines from lender approval requirements. Your complete financial picture helps shape the decision.
- Match the St. Johns County loan limit to the property’s unit count, and consider the home’s condition as you search.
- Gather income and asset records, debt details, identification, and property information before applying. Smart Home Loans also offers credit repair support and down payment assistance.
FHA Loan Requirements in St. Augustine, FL: Start with This Borrower Checklist
FHA insurance helps protect approved lenders if a borrower defaults. It does not mean the government approves every application. The Federal Housing Administration (FHA) sets program guidelines, while the lender reviews your full financial picture and decides whether you meet its requirements. Meeting a published FHA threshold is a starting point, not a promise of approval.
Before applying, organize these details:
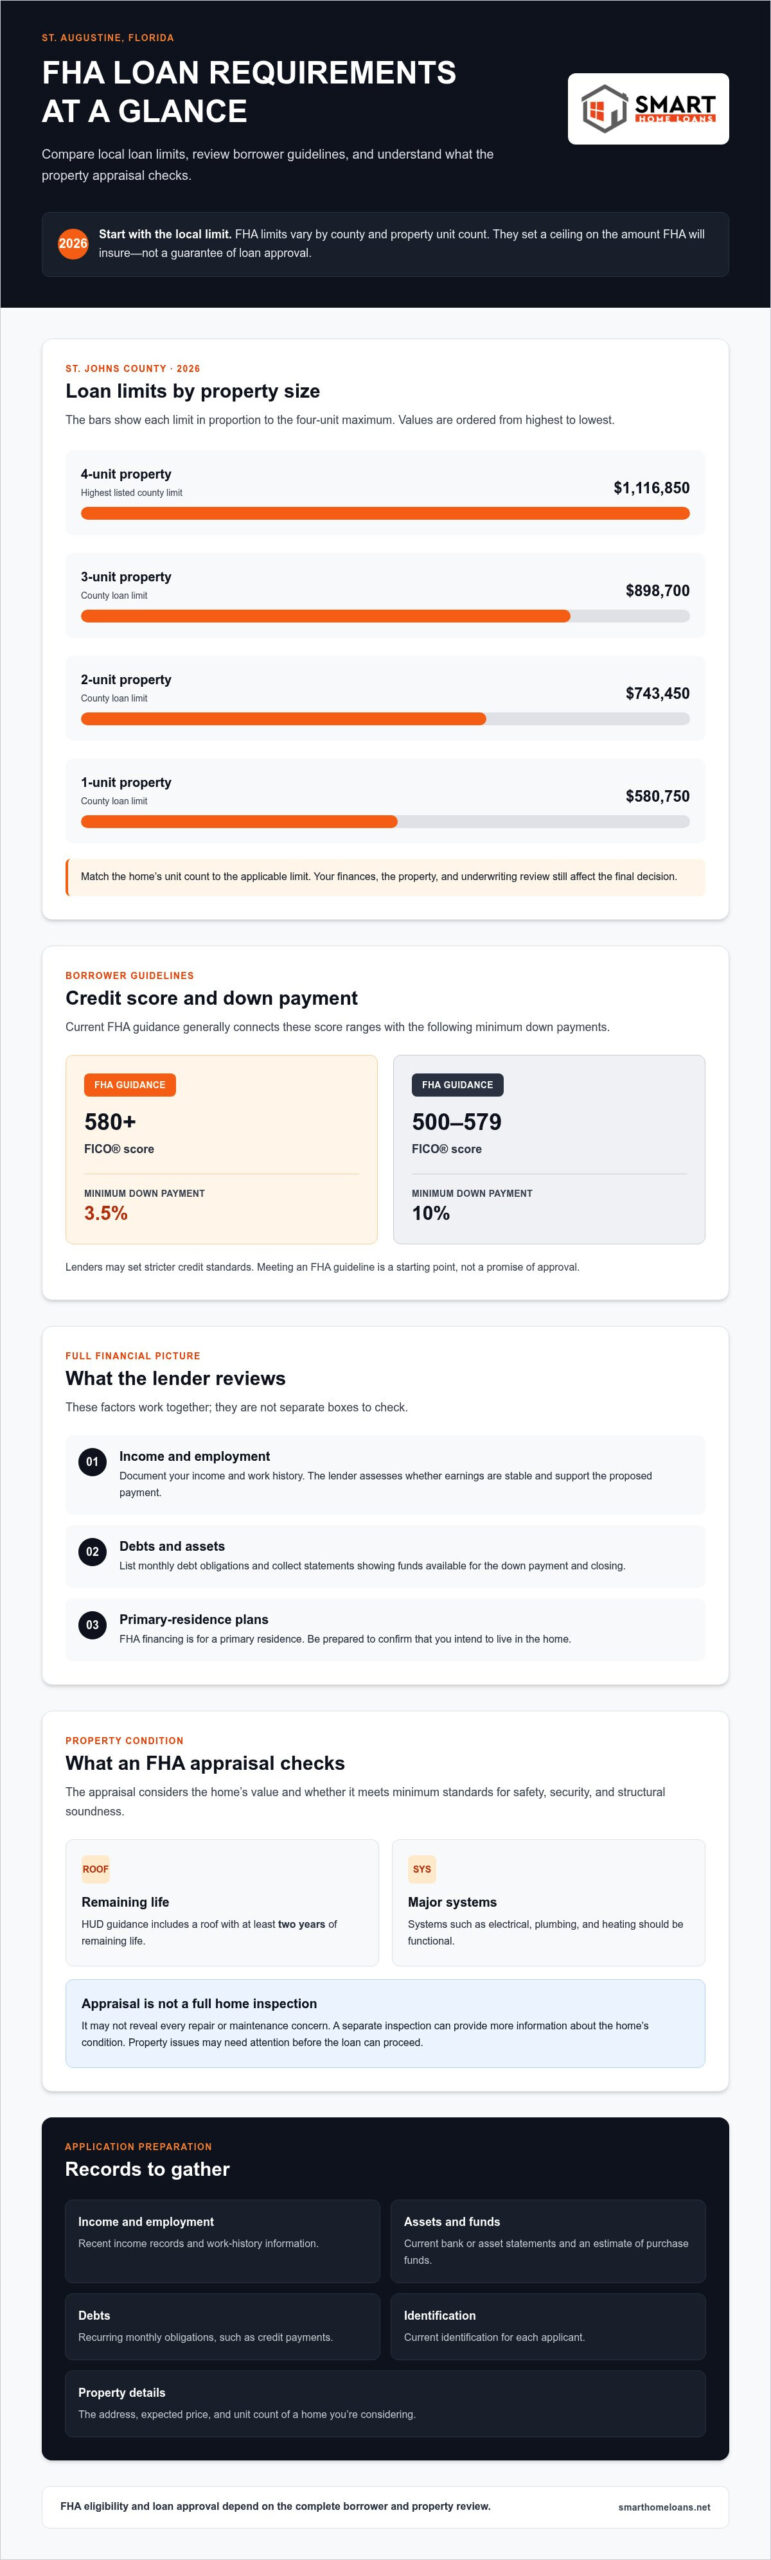
- Credit: Current FHA guidance generally allows a 3.5% minimum down payment with a FICO® score of 580 or higher. Scores from 500 to 579 generally require at least 10% down. Lenders may set stricter credit standards.
- Income and employment: Gather records documenting your income and work history. The lender assesses whether your earnings are stable and support the proposed payment.
- Debts and assets: List monthly debt obligations and collect statements showing funds available for the down payment and closing. Lenders consider debts, assets, and income together, not as separate boxes to check.
- Occupancy plans: FHA financing is for a primary residence. Be prepared to confirm that you intend to live in the home.
What should St. Augustine buyers check before applying?
Start with your credit and available funds, then review the full application rather than relying on one score or down payment figure. FHA minimums can differ from a lender’s own approval standards, sometimes called overlays. If credit is a concern, read our FHA loan with bad credit guide. Smart Home Loans can review your FHA options and help you identify the documents to prepare.
How St. Johns County Loan Limits and FHA Appraisals Affect Your Home Search
Your budget should account for both the FHA loan limit and the home’s condition. Limits vary by county and property type, so match the property’s unit count to the applicable St. Johns County limit. For 2026, the verified limits are $580,750 for a one-unit property, $743,450 for two units, $898,700 for three units, and $1,116,850 for four units.
These limits set a ceiling on the amount FHA will insure; they do not guarantee approval for a particular loan. HUD also outlines general eligibility requirements. Your loan file still depends on the property, your finances, and underwriting review.
Can the home itself affect FHA financing in St. Augustine?
Yes. An FHA appraisal considers the home’s value and whether it meets minimum standards for safety, security, and structural soundness. HUD guidance includes a roof with at least two years of remaining life and functional major systems, such as electrical, plumbing, and heating. The appraisal is not a comprehensive home inspection, so it may not reveal every repair or maintenance concern. Consider a separate inspection to learn more about the home’s condition.
An appraisal that supports the transaction does not guarantee financing. Underwriting reviews the full application, and property issues may need attention before the loan can proceed. For an overview of the steps from preapproval to closing, read our Florida mortgage process guide. FHA loan requirements St. Augustine FL buyers face depend on both borrower qualifications and the specific property. Smart Home Loans can help you review FHA options as you weigh a home.
Your Next Steps to Apply for an FHA Loan in St. Augustine
Turn the checklist into a plan. Review your credit, regular income, monthly debts, savings, and estimated funds for the purchase. Organize your records and discuss your financial picture with a mortgage professional. This early review can help identify questions to address before you make an offer, but it is not a loan approval.
Gather these details to prepare for a complete application:
- Income and employment: Recent income records and information about your work history.
- Assets and funds: Current bank or asset statements, plus an estimate of funds available for the purchase.
- Debts: A list of recurring monthly obligations, such as credit payments.
- Identification: Current identification for each applicant.
- Property details: The address, expected price, and unit count of a home you’re considering.
Before settling on a search range, use HUD’s lookup tool to compare the home’s unit count with the current St. Johns County loan limits. This local detail can help make your planning conversation more specific. Preapproval can clarify a potential budget, while final underwriting still depends on the complete borrower and property review.
What information helps prepare an FHA application?
Keep your records together and note changes in income, employment, savings, or monthly debt. These details help shape a useful conversation about FHA loan requirements St. Augustine FL buyers may encounter. Smart Home Loans offers FHA options, credit repair support, and down payment assistance. Eligibility for a loan or assistance depends on the individual review.
Smart Home Loans can help you review your options for an FHA home loan in St. Augustine. Explore FHA home loan options and prepare for your next application step.
Take the Next Step Toward Your St. Augustine Home
Start with a clear picture of your finances, then match your plans to the property and the current St. Johns County FHA loan limit. The FHA loan requirements St. Augustine FL buyers need to review include credit, down payment, income, debts, available funds, occupancy plans, and the home’s condition.
Smart Home Loans offers FHA home loans to buyers in St. Augustine. We can review your FHA options and discuss credit repair support or down payment assistance based on your circumstances. Eligibility and loan approval depend on your specific application.
Ready to take a practical next step? Talk with Smart Home Loans about your FHA options.
Frequently Asked Questions
What credit score do you need for an FHA loan in Florida?
For the minimum 3.5% down payment, FHA guidance generally requires a FICO® score of at least 580. Scores from 500 to 579 generally require at least 10% down. These are FHA program thresholds, not a promise of lender approval. A lender may apply stricter credit standards and will review your income, debts, assets, and complete application.
How much down payment is required for an FHA loan in St. Augustine?
The minimum is generally 3.5% of the purchase price with a qualifying FICO® score of 580 or higher. With a score from 500 to 579, FHA guidance generally calls for at least 10% down. Lender requirements may be stricter, and closing funds are separate. Smart Home Loans can review your FHA options and discuss down payment assistance.
What is the 2026 FHA loan limit in St. Johns County, Florida?
For 2026, the St. Johns County FHA limit is $580,750 for a one-unit property. The limit is $743,450 for two units, $898,700 for three, and $1,116,850 for four. St. Augustine buyers should match the limit to the property’s unit count. The applicable limit caps the FHA-insured loan amount; it does not determine borrower approval.
Does an FHA appraisal mean a St. Augustine home has passed inspection?
No. An FHA appraisal assesses the home’s value and checks whether it meets minimum standards for safety, security, and structural soundness. It is not a comprehensive home inspection and may not identify every maintenance issue. Consider a separate inspection to learn more about the home’s condition. An appraisal also does not guarantee loan approval, since underwriting reviews the full application.