Could your Saint Augustine home purchase require jumbo financing, even if the home’s price doesn’t make it obvious? The deciding factor is generally the loan amount, not the purchase price. For 2026, the conforming loan limit for a one-unit property in St. Johns County is $832,750, so a loan above that amount is generally considered jumbo.
Qualifying can raise questions about income, credit, cash reserves, and the ongoing cost of owning a home. This guide explains when jumbo financing may apply, what lenders evaluate, and how to prepare a clear application. You’ll also learn how property details and recurring housing expenses can shape your options, then see how to compare mortgage choices with Smart Home Loans, a mortgage brokerage serving Saint Augustine.
Key Takeaways
- A jumbo loan Saint Augustine FL buyers consider depends on the loan amount, property location, and applicable year, not just the home’s purchase price.
- Gather income, employment, asset, debt, and credit details before applying so your financial picture is easier to review.
- Build a full housing budget that includes taxes, insurance, and other property-related costs that may apply.
- Compare mortgage options by clarifying your goals, reviewing loan structure and documented terms, and assessing your readiness with a local mortgage broker.
When does a jumbo loan make sense for a Saint Augustine home purchase?
A higher-priced home doesn’t automatically require jumbo financing. The mortgage amount is generally what determines the loan type, so your down payment and other financing details matter alongside the purchase price. A jumbo mortgage exceeds the conforming loan limit set by the Federal Housing Finance Agency (FHFA). For background on how jumbo and conforming loans differ, see this overview of the jumbo mortgage.
How the conforming loan limit affects Saint Augustine buyers
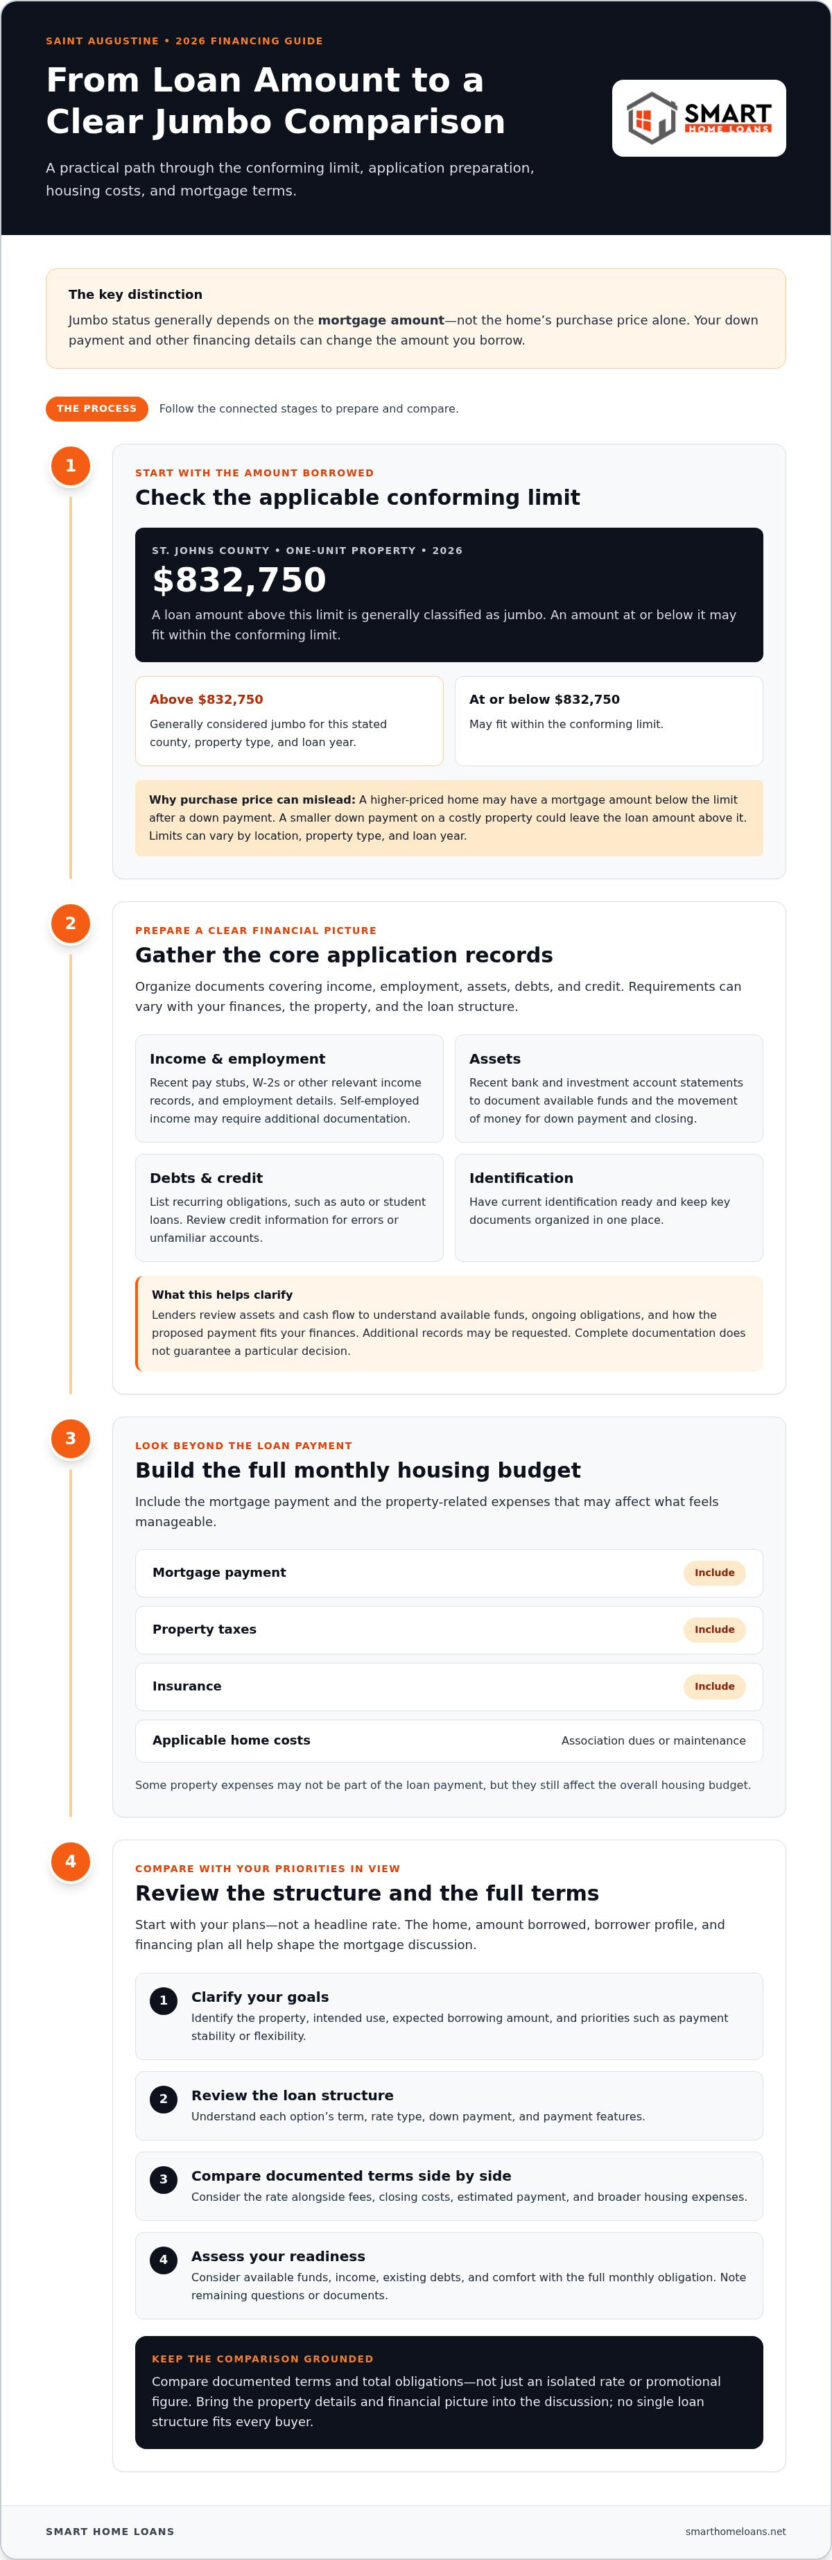
Saint Augustine is in St. Johns County. For 2026, the FHFA conforming loan limit for a one-unit property in the county is $832,750. A loan amount above that limit is generally classified as jumbo; an amount at or below it may fit within the conforming limit. Limits can vary by location, property type, and loan year, so use the figure that applies to your specific scenario.
For example, a home’s purchase price could exceed the limit while the mortgage amount stays below it after the down payment. A smaller down payment on a costly property, on the other hand, could leave a loan amount above the limit. That’s why the purchase price alone doesn’t determine whether you’ll need a jumbo loan Saint Augustine FL buyers may consider.
Jumbo financing is one option to compare, not an automatic fit for every higher-priced home. Start with the amount you expect to borrow, then weigh your goals, available funds, and financing structure. For broader context, review the 2026 jumbo loans in Florida buyer’s guide, then compare mortgage options that suit your scenario.
What should you prepare before applying for a jumbo loan in Saint Augustine?
An organized application makes it easier to review your finances and identify questions early. Before discussing a jumbo loan Saint Augustine FL purchase, gather records that show your income, employment, assets, debts, and credit history. Requirements vary with your finances, the property, and the loan structure, so use this as a preparation checklist rather than a universal approval formula.
A practical jumbo mortgage application checklist
- Income and employment: Collect recent pay stubs, W-2s or other relevant income records, and employment details. Self-employed income may require additional documentation.
- Assets: Gather recent bank and investment account statements. These help document available funds and the movement of money for a down payment and closing.
- Debts and credit: List recurring obligations, such as auto or student loans, and review your credit information for errors or unfamiliar accounts.
- Identification: Have current identification ready and keep key documents organized in one place.
Lenders review assets and cash flow to understand your available funds, ongoing obligations, and how the proposed payment fits your finances. They may ask for additional records depending on your situation. Complete documentation helps present a clear picture, but it doesn’t guarantee a particular decision.
Build a realistic monthly housing budget, too. Include the mortgage payment, property taxes, insurance, and applicable costs tied to the home, such as association dues or maintenance. These expenses affect what feels manageable, even when they aren’t part of the loan payment.
For an overview of the steps from pre-approval through closing, read the Florida mortgage process guide. To discuss your goals and financial readiness, connect with Smart Home Loans.
How can you compare jumbo loan options and move forward in Saint Augustine?
Start a useful comparison with your plans, not a headline rate. The right structure depends on the home, the amount you plan to borrow, and what fits your finances. Use these steps to keep the discussion focused:
- Clarify your goals. Identify the property, intended use, expected borrowing amount, and priorities, such as payment stability or flexibility.
- Review the loan structure. Understand how each option is set up, including its term, rate type, down payment, and payment features.
- Compare documented terms. Review written details side by side. Consider the rate alongside fees, closing costs, estimated payment, and your broader housing expenses.
- Assess your readiness. Consider your available funds, income, existing debts, and comfort with the full monthly obligation. Note any questions or documents you still need to address.
For a jumbo loan Saint Augustine FL comparison, property details matter, too. The home’s type and intended use, your borrower profile, and your financing plan all help shape the mortgage discussion. Bringing a clear picture of the property and your finances makes it easier to compare suitable options without assuming one loan structure fits every buyer.
From financing comparison to a clear next step
Compare documented terms and total obligations, not just an isolated rate or promotional figure. Smart Home Loans can help you discuss jumbo financing alongside other mortgage options, taking your goals and financial picture into account. Bring your questions and the property details you have so far. Discuss your Saint Augustine mortgage options with Smart Home Loans to take a practical next step toward choosing a financing path.
Take your next step toward the right financing
A jumbo loan may be relevant when your mortgage amount exceeds the applicable conforming limit, but a higher home price alone doesn’t determine the loan type. Your down payment, finances, and property details all help shape the picture. Prepare income, asset, debt, and credit records, then compare loan structures and full housing costs, not just a headline rate.
If you’re considering a jumbo loan Saint Augustine FL, Smart Home Loans can help you discuss your goals and compare mortgage options. The Saint Augustine-serving brokerage is managed by Sean, NMLS ID 1734077. Bring your questions and financial details to start a focused conversation about what may fit your plans.
Talk with Smart Home Loans about your Saint Augustine jumbo loan options. An organized application and a clear view of your priorities can help you move forward with confidence.
Frequently Asked Questions
What is a jumbo loan in Saint Augustine, Florida?
A jumbo loan is a mortgage amount above the conforming limit set for the property’s location and loan year. In 2026, the Federal Housing Finance Agency’s one-unit limit for St. Johns County, which includes Saint Augustine, is $832,750. A loan above that amount is generally jumbo. The limit applies to the amount borrowed, not simply the home’s purchase price.
How do I know if I need a jumbo loan to buy a home in Saint Augustine?
Compare the amount you expect to borrow with the applicable conforming limit, not just the home’s price. A purchase price above the limit may still result in a conforming-size loan after your down payment. A smaller down payment could leave a loan above the limit. For a jumbo loan Saint Augustine FL buyers should use the limit that applies to the property type and loan year.
What documents are typically needed for a jumbo mortgage?
Prepare records that describe your finances and the property, though requested documents vary by borrower and loan structure. Common items include recent pay stubs, W-2s or tax returns, employment details, bank or investment statements, a list of debts, credit information, identification, and property records. Keep documents organized and be ready to explain large deposits or changes in income.
Can I compare a jumbo loan with other mortgage options?
Yes. Comparing a jumbo loan with other mortgage options can help you see which structure aligns with your finances and the property. Review documented terms, including rate type, loan term, costs, down payment, and the full housing obligation. Smart Home Loans can discuss your Saint Augustine property details, borrower profile, goals, and relevant loan options without assuming one choice fits everyone.